Insights
Weekly Market Map - 10 October, 2026
Weekly Market Map
In this article
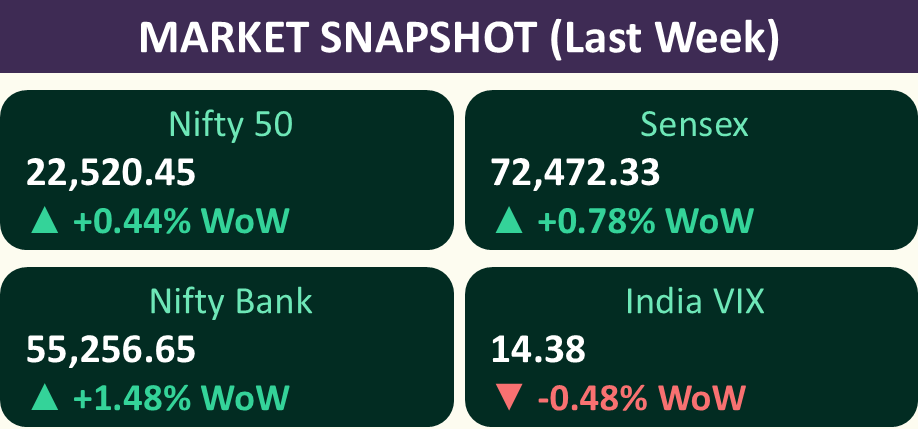
- Nifty snaps losing streak, rises 0.44% WoW
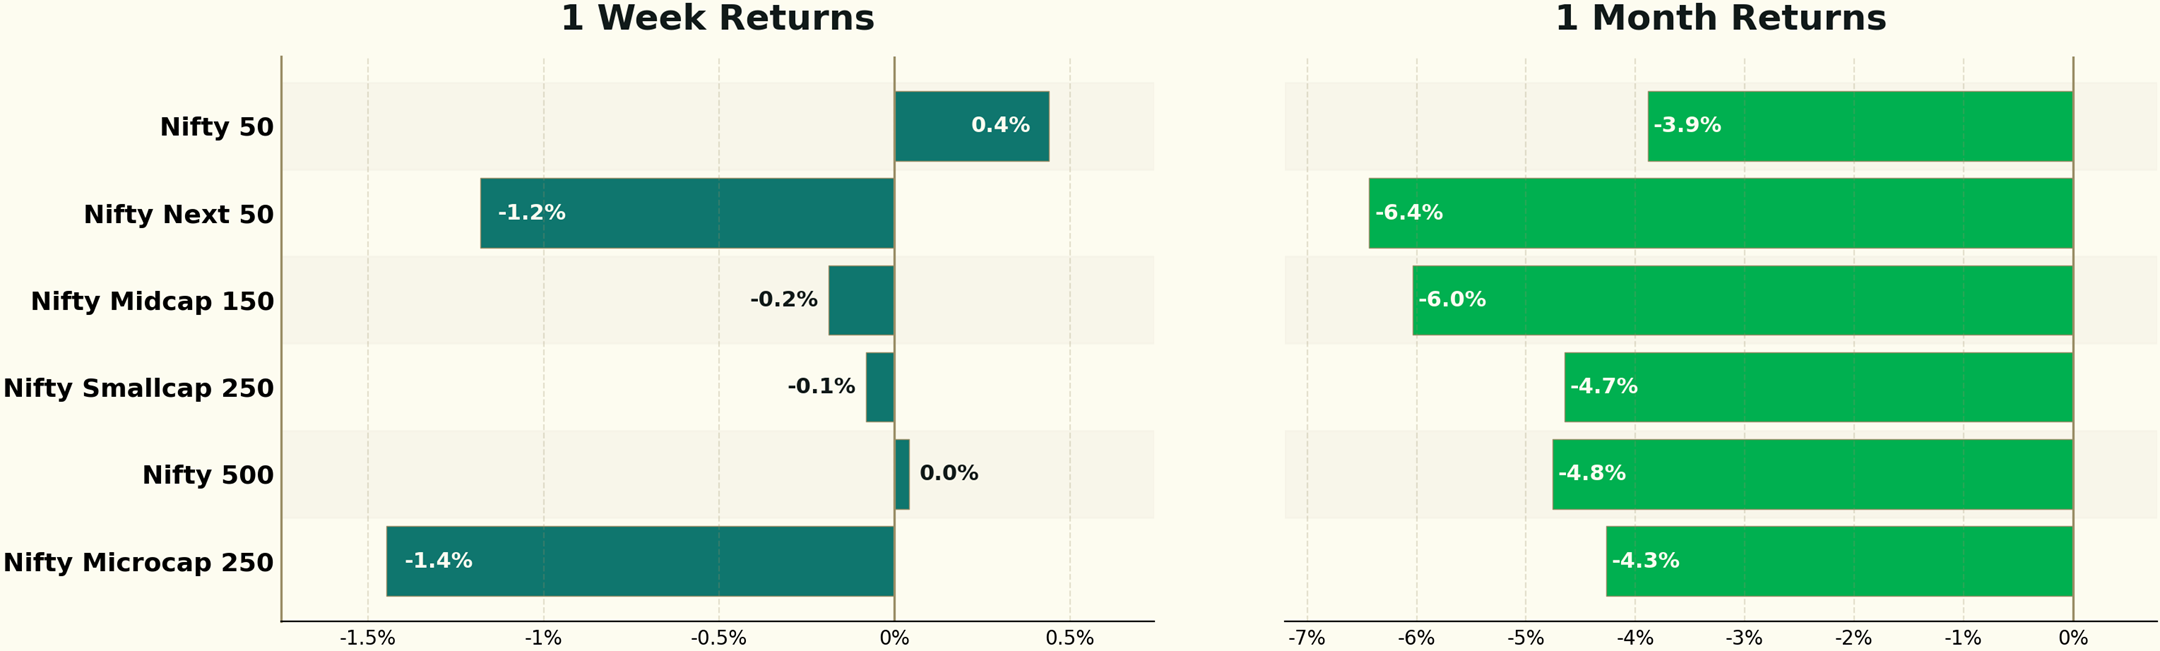
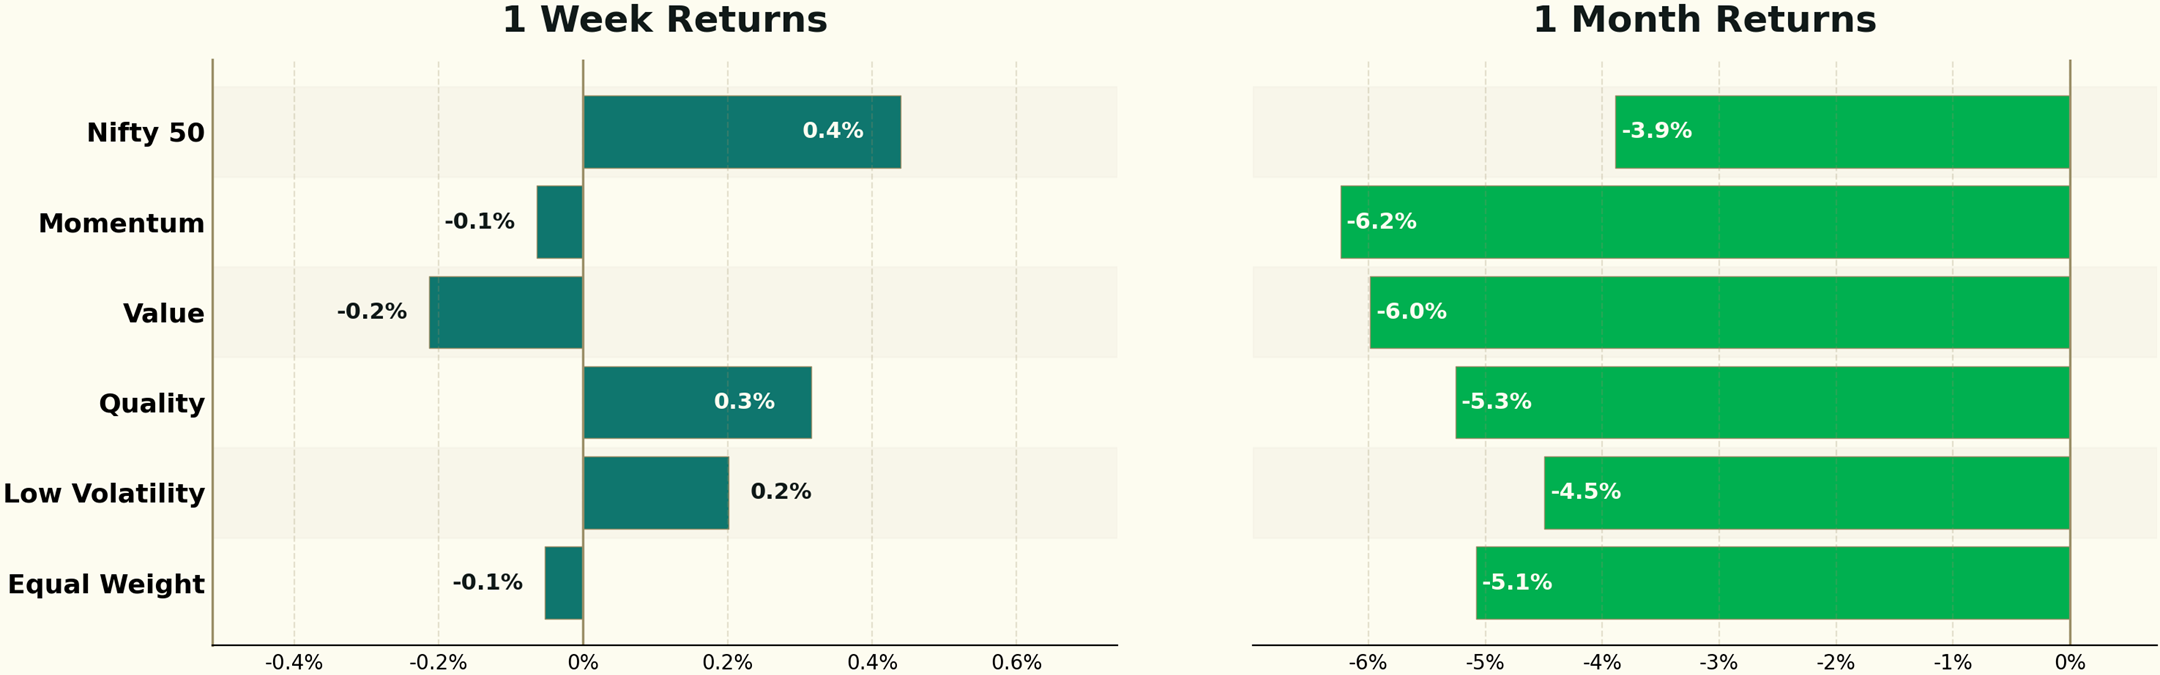
- Nifty 50 edges up this week – broader markets still lag; In Factors – Quality leads this week, Value lags
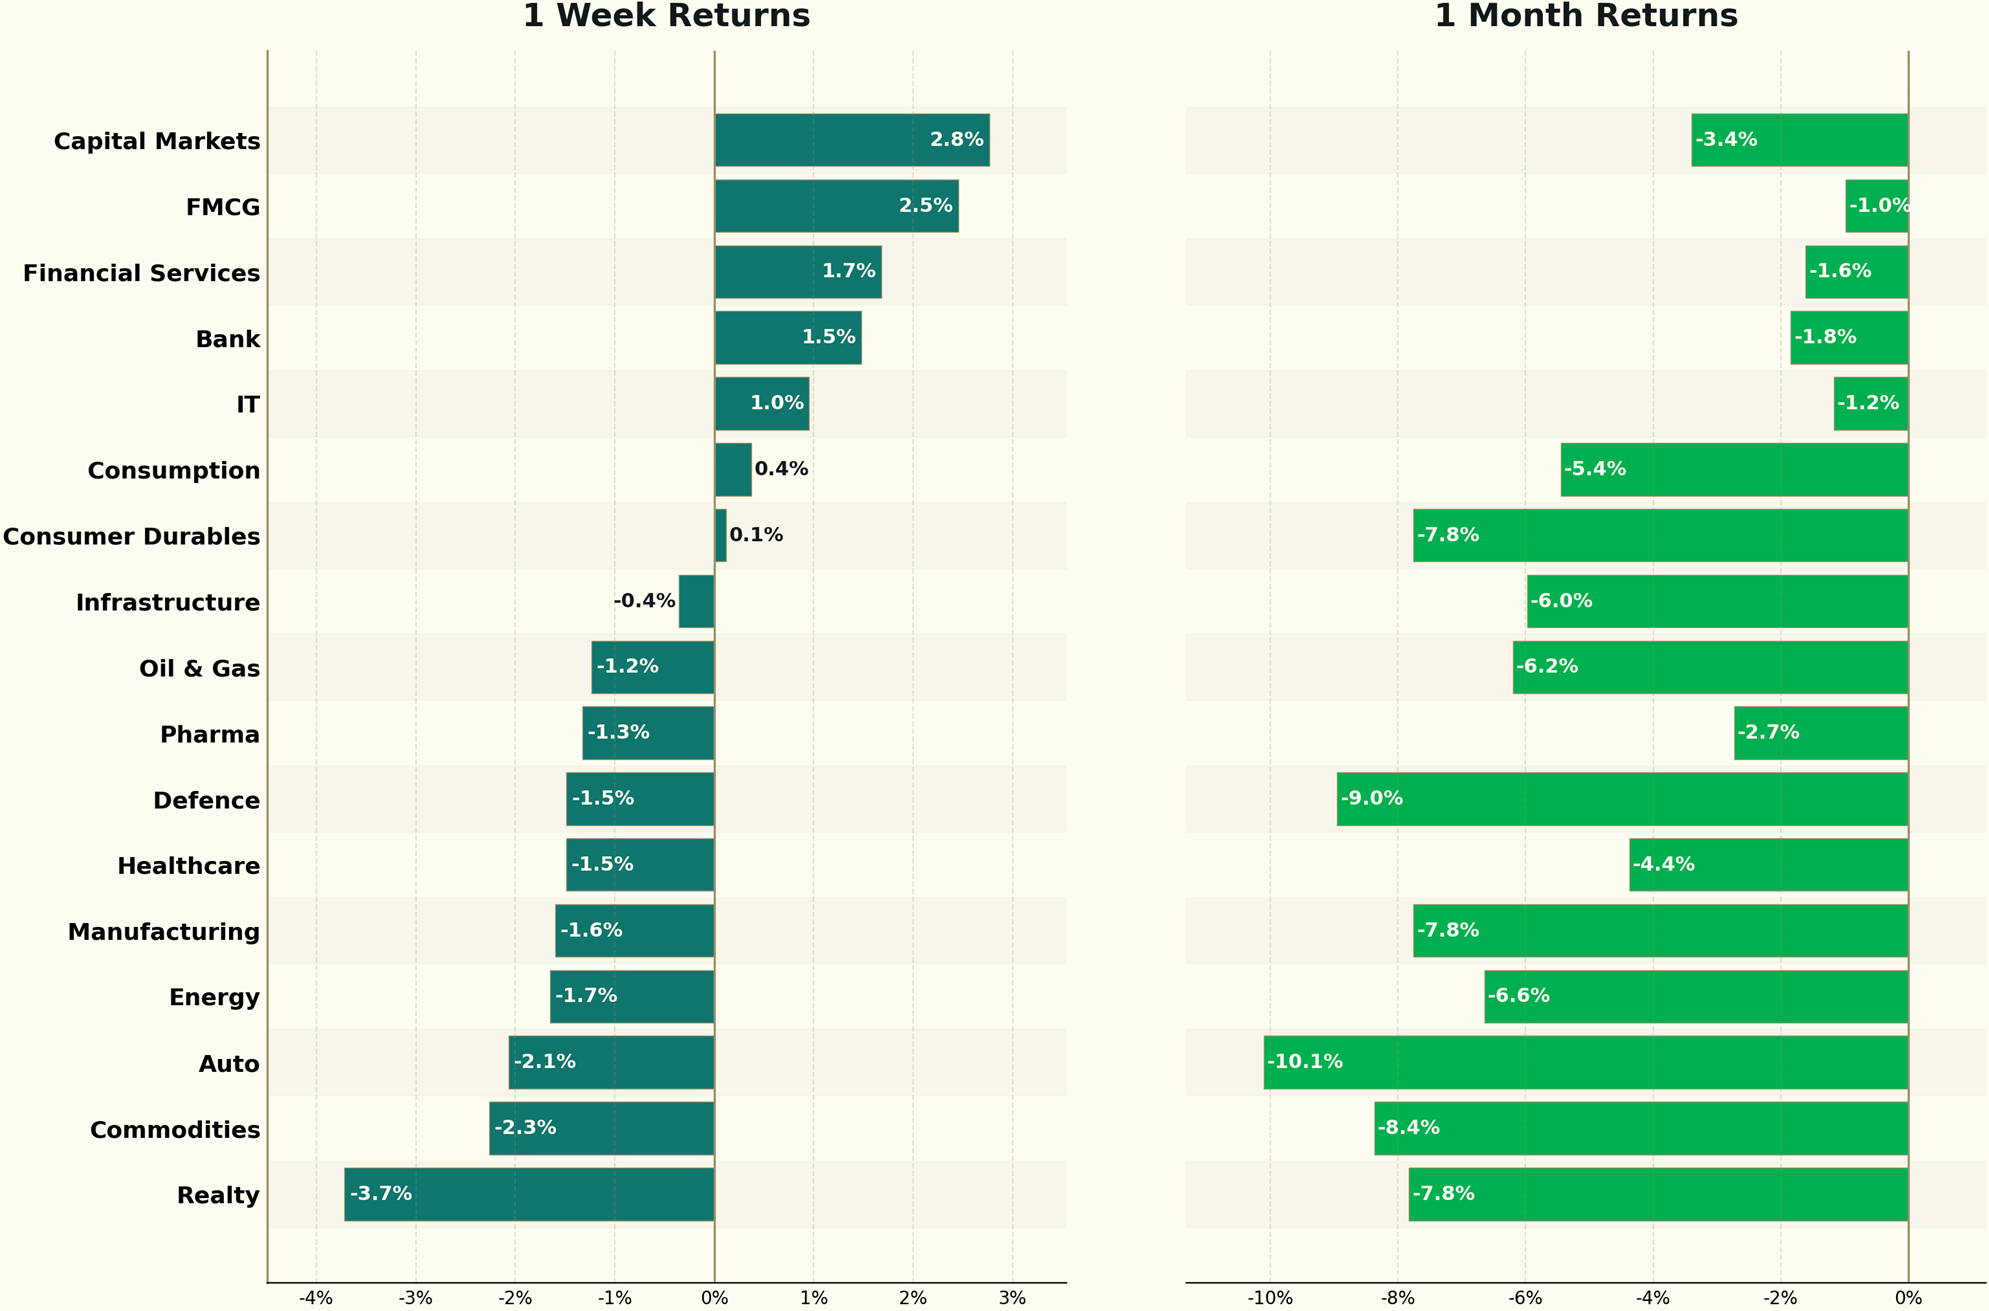
- Capital Markets, FMCG lead this week; Realty lags sharply
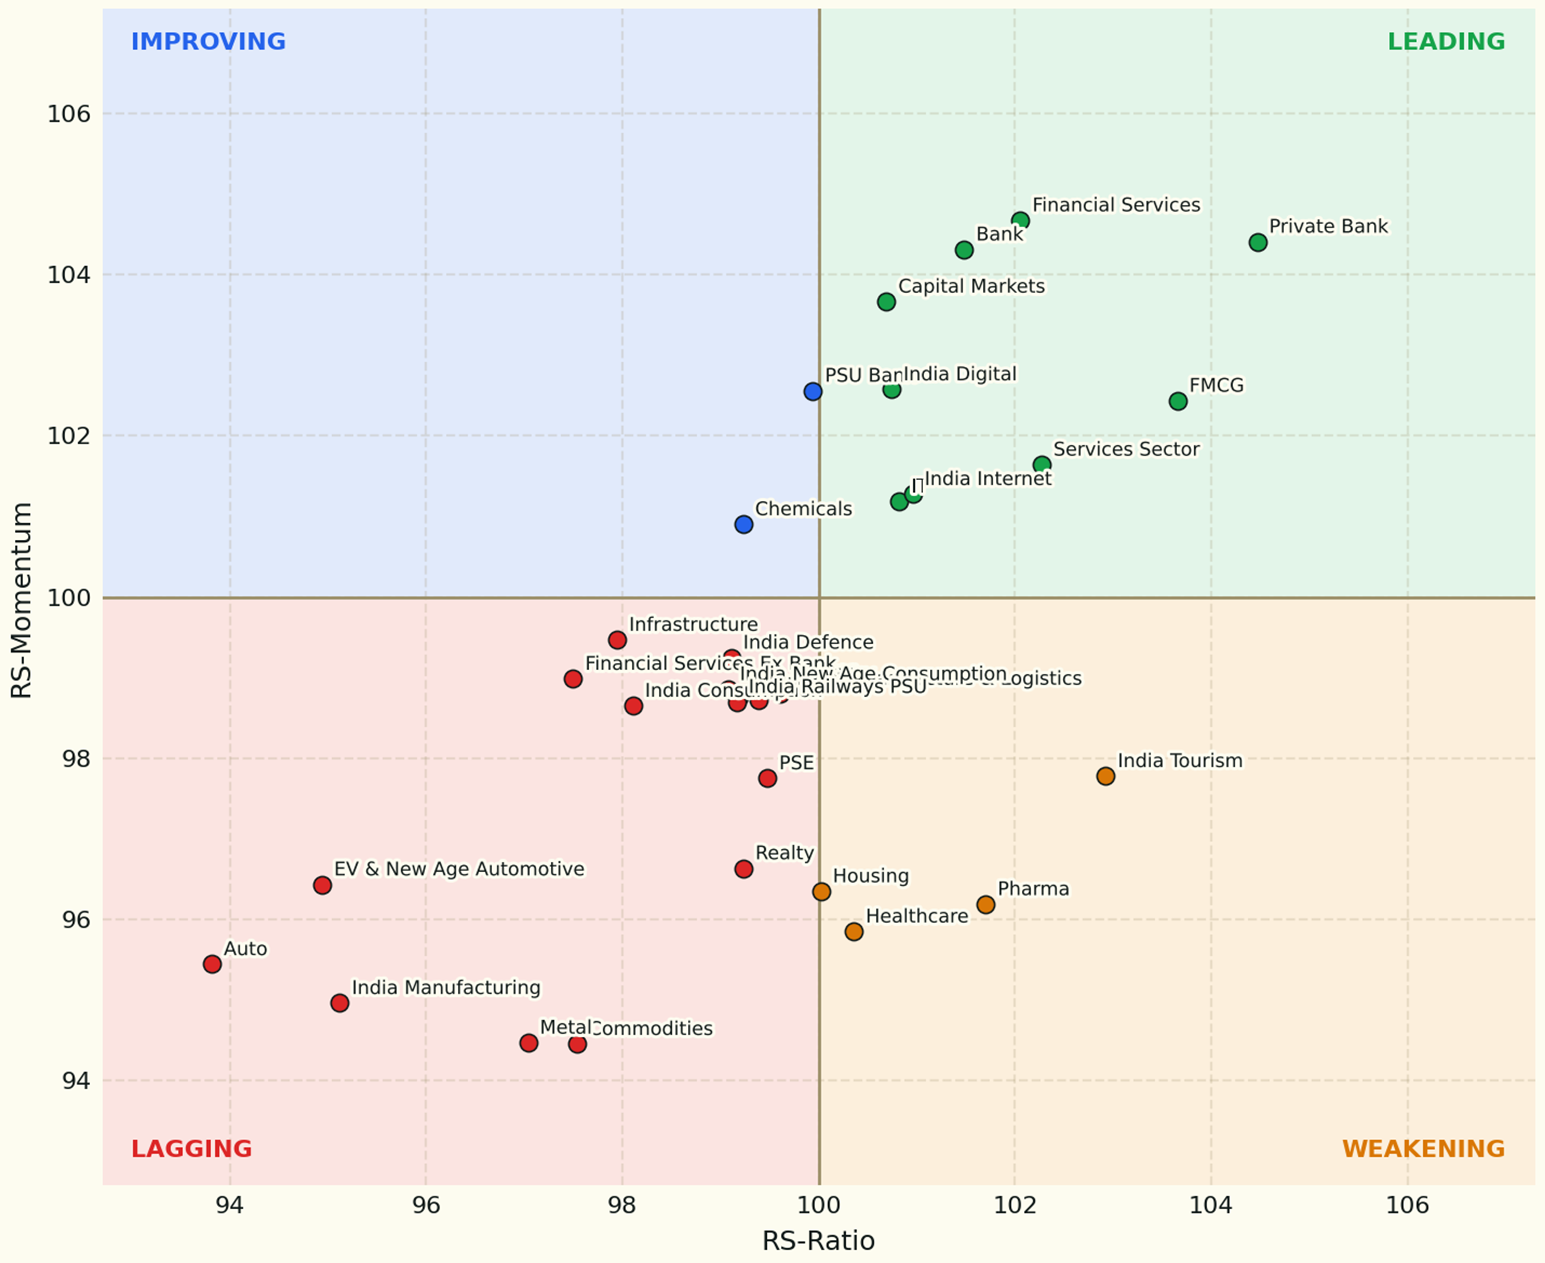
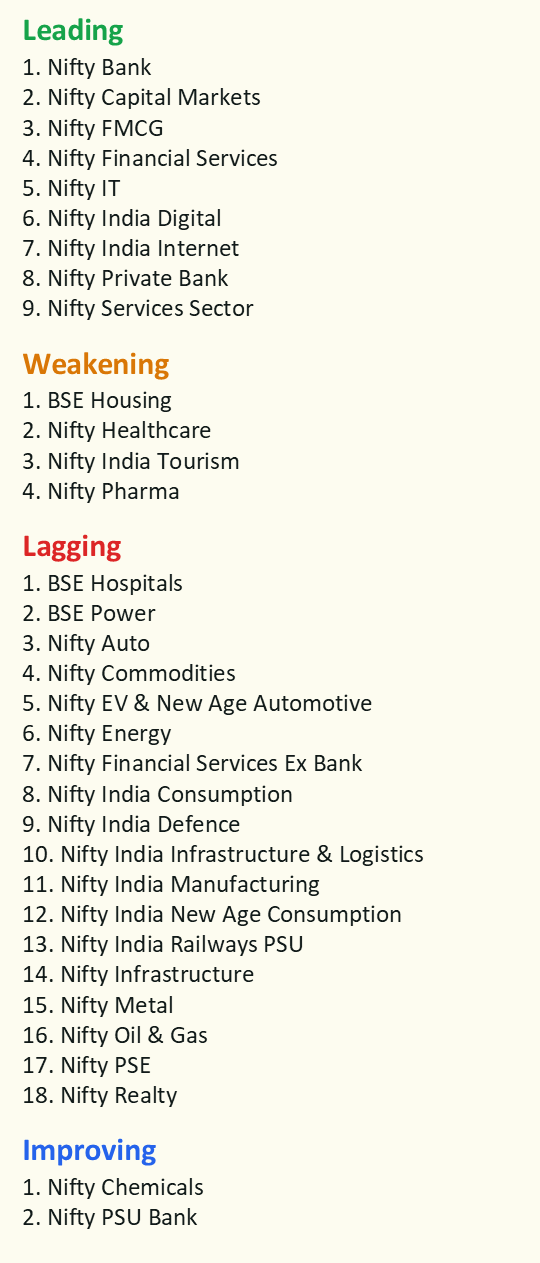
- Sector Rotation: Private Bank, Financials lead; Pharma weakens
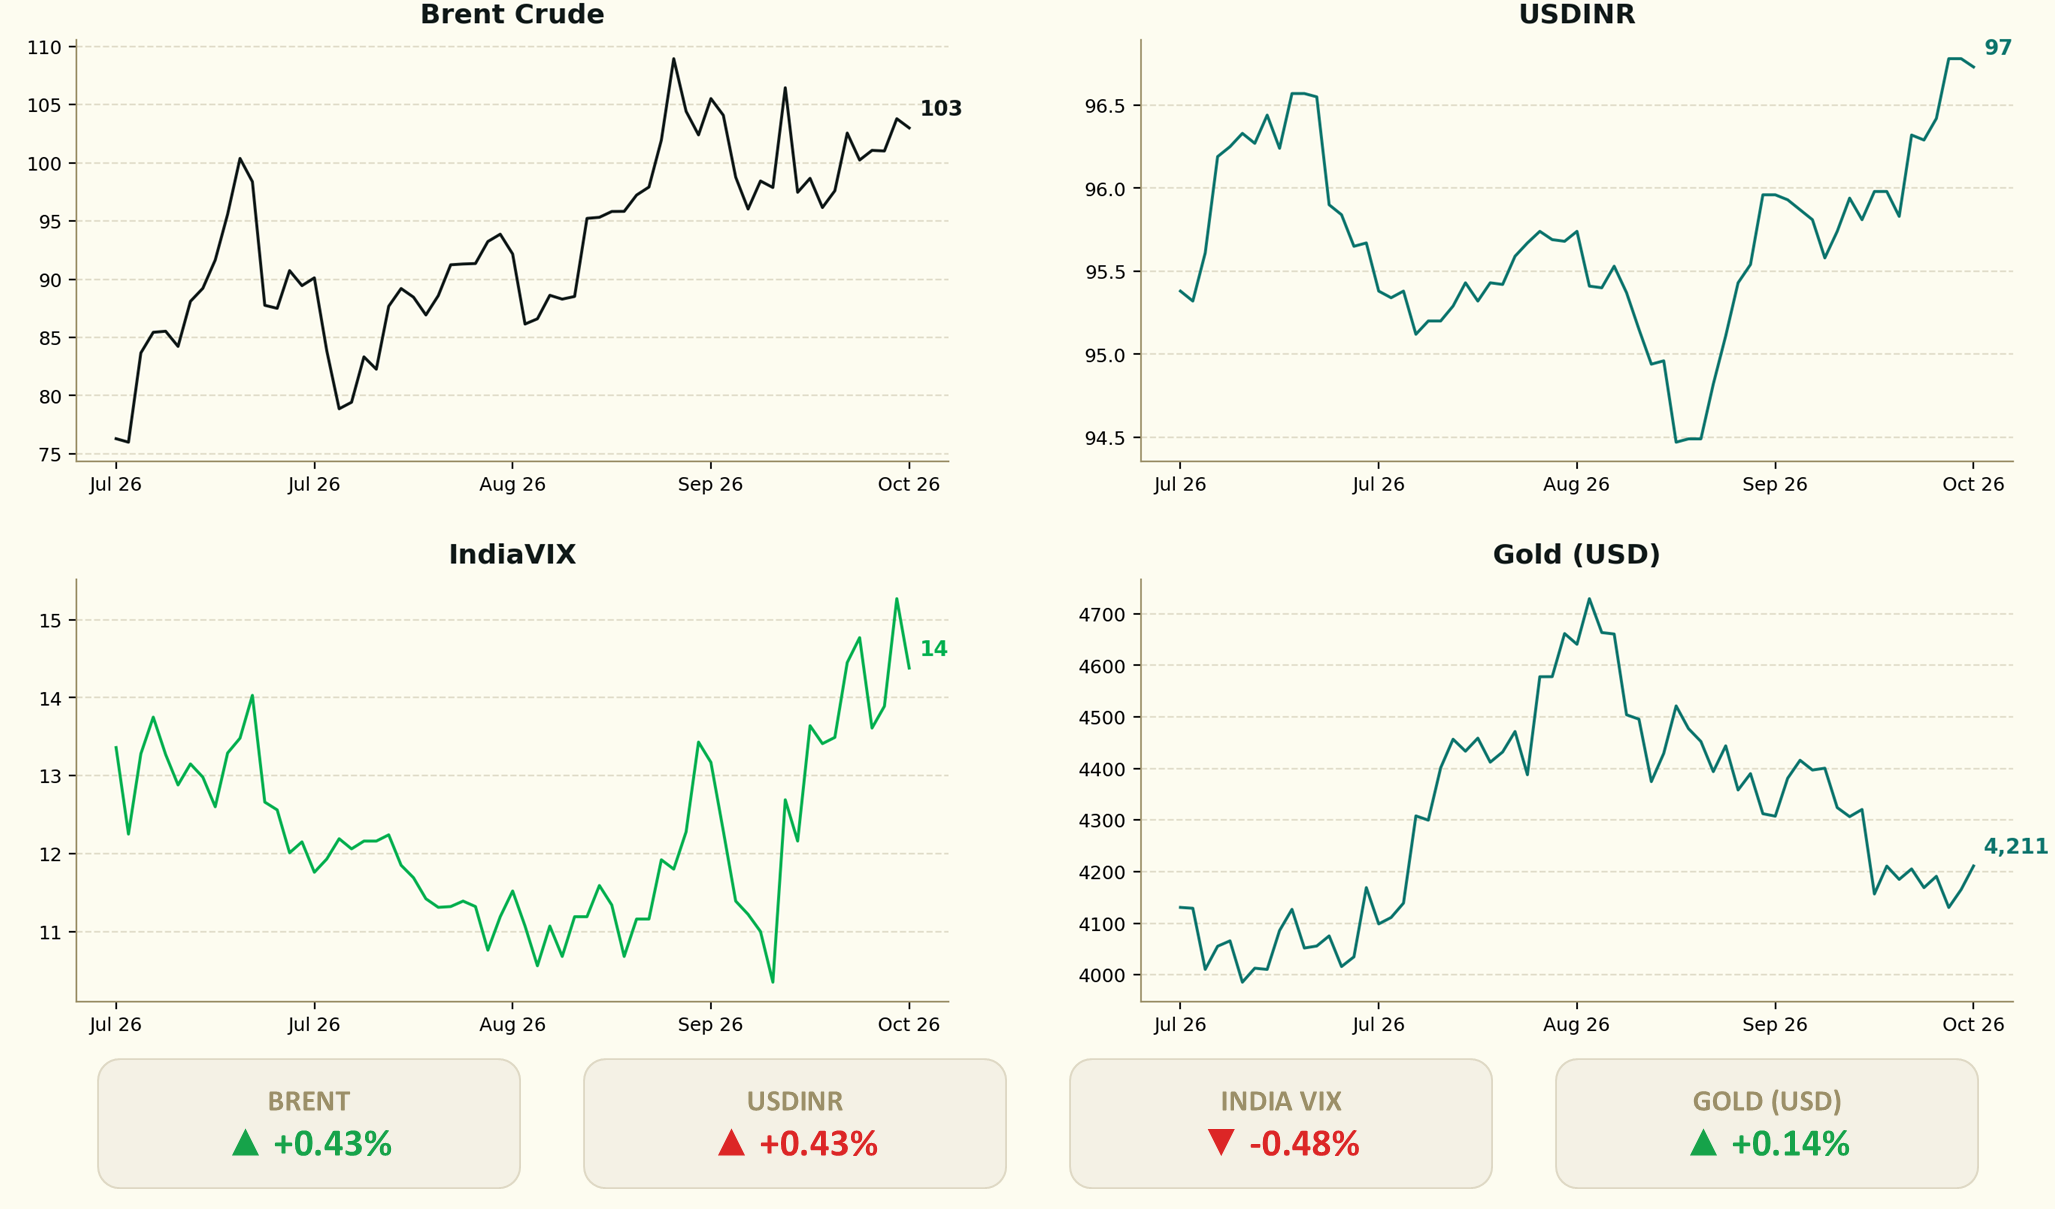
- Macro: Brent, rupee tick up; VIX eases 0.5%
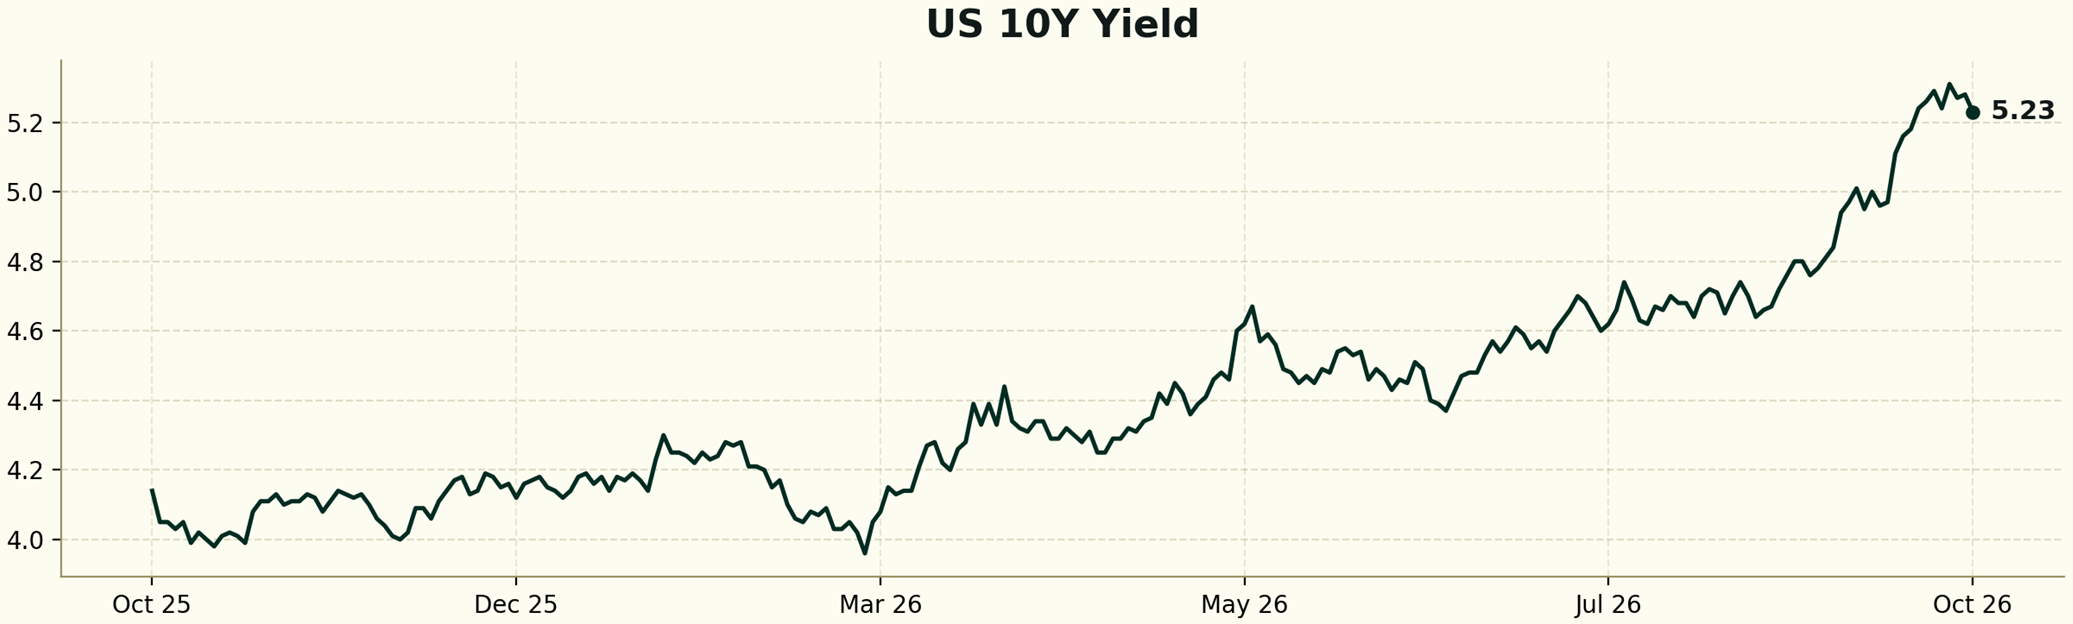
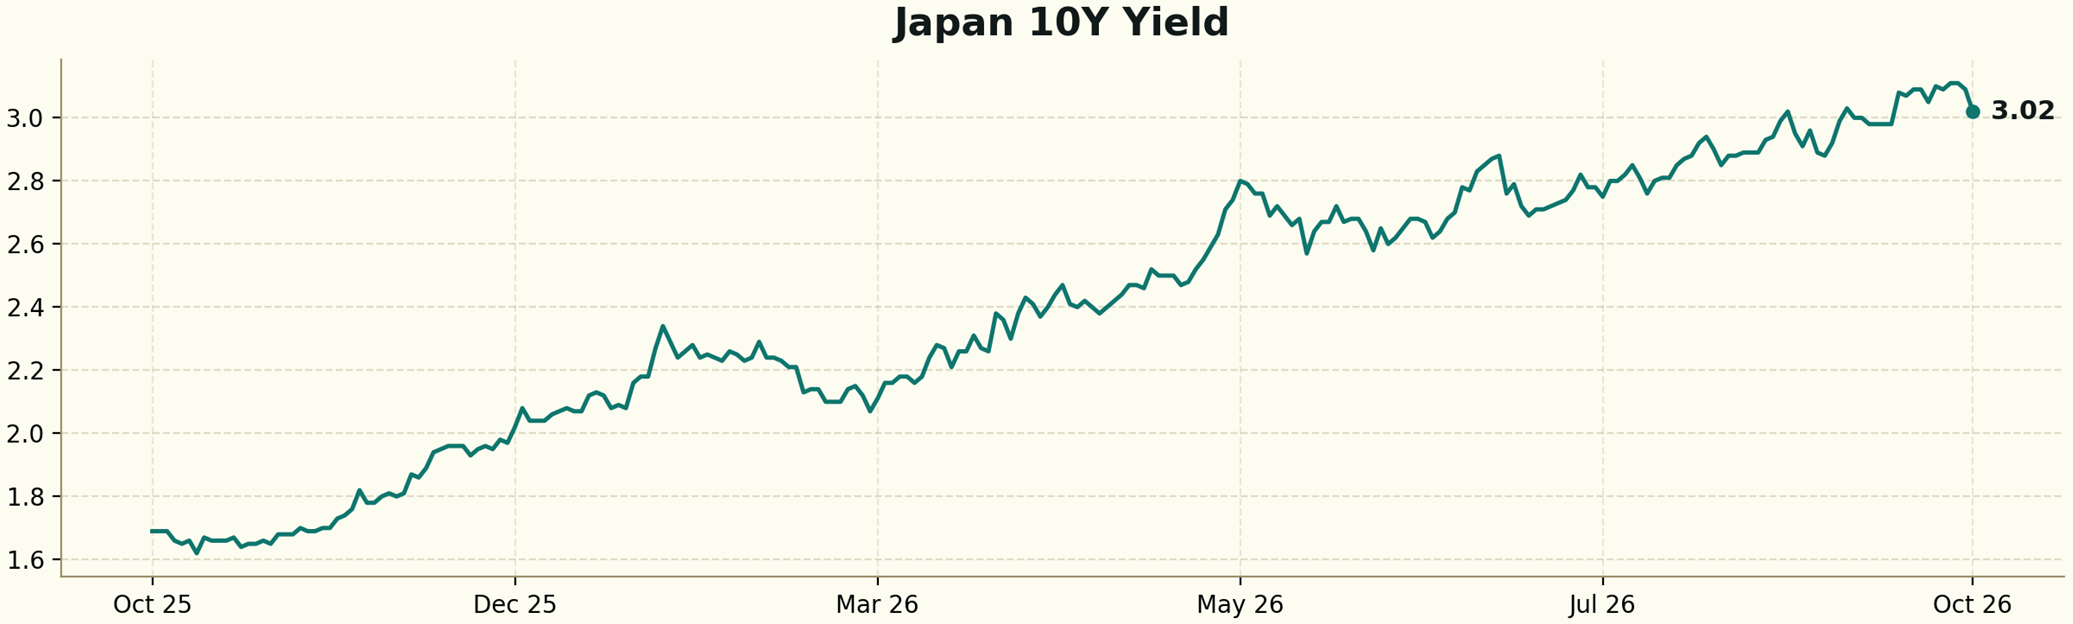
- Global 10Y Yields: US eases to 5.23% off highs; Japan near 3%
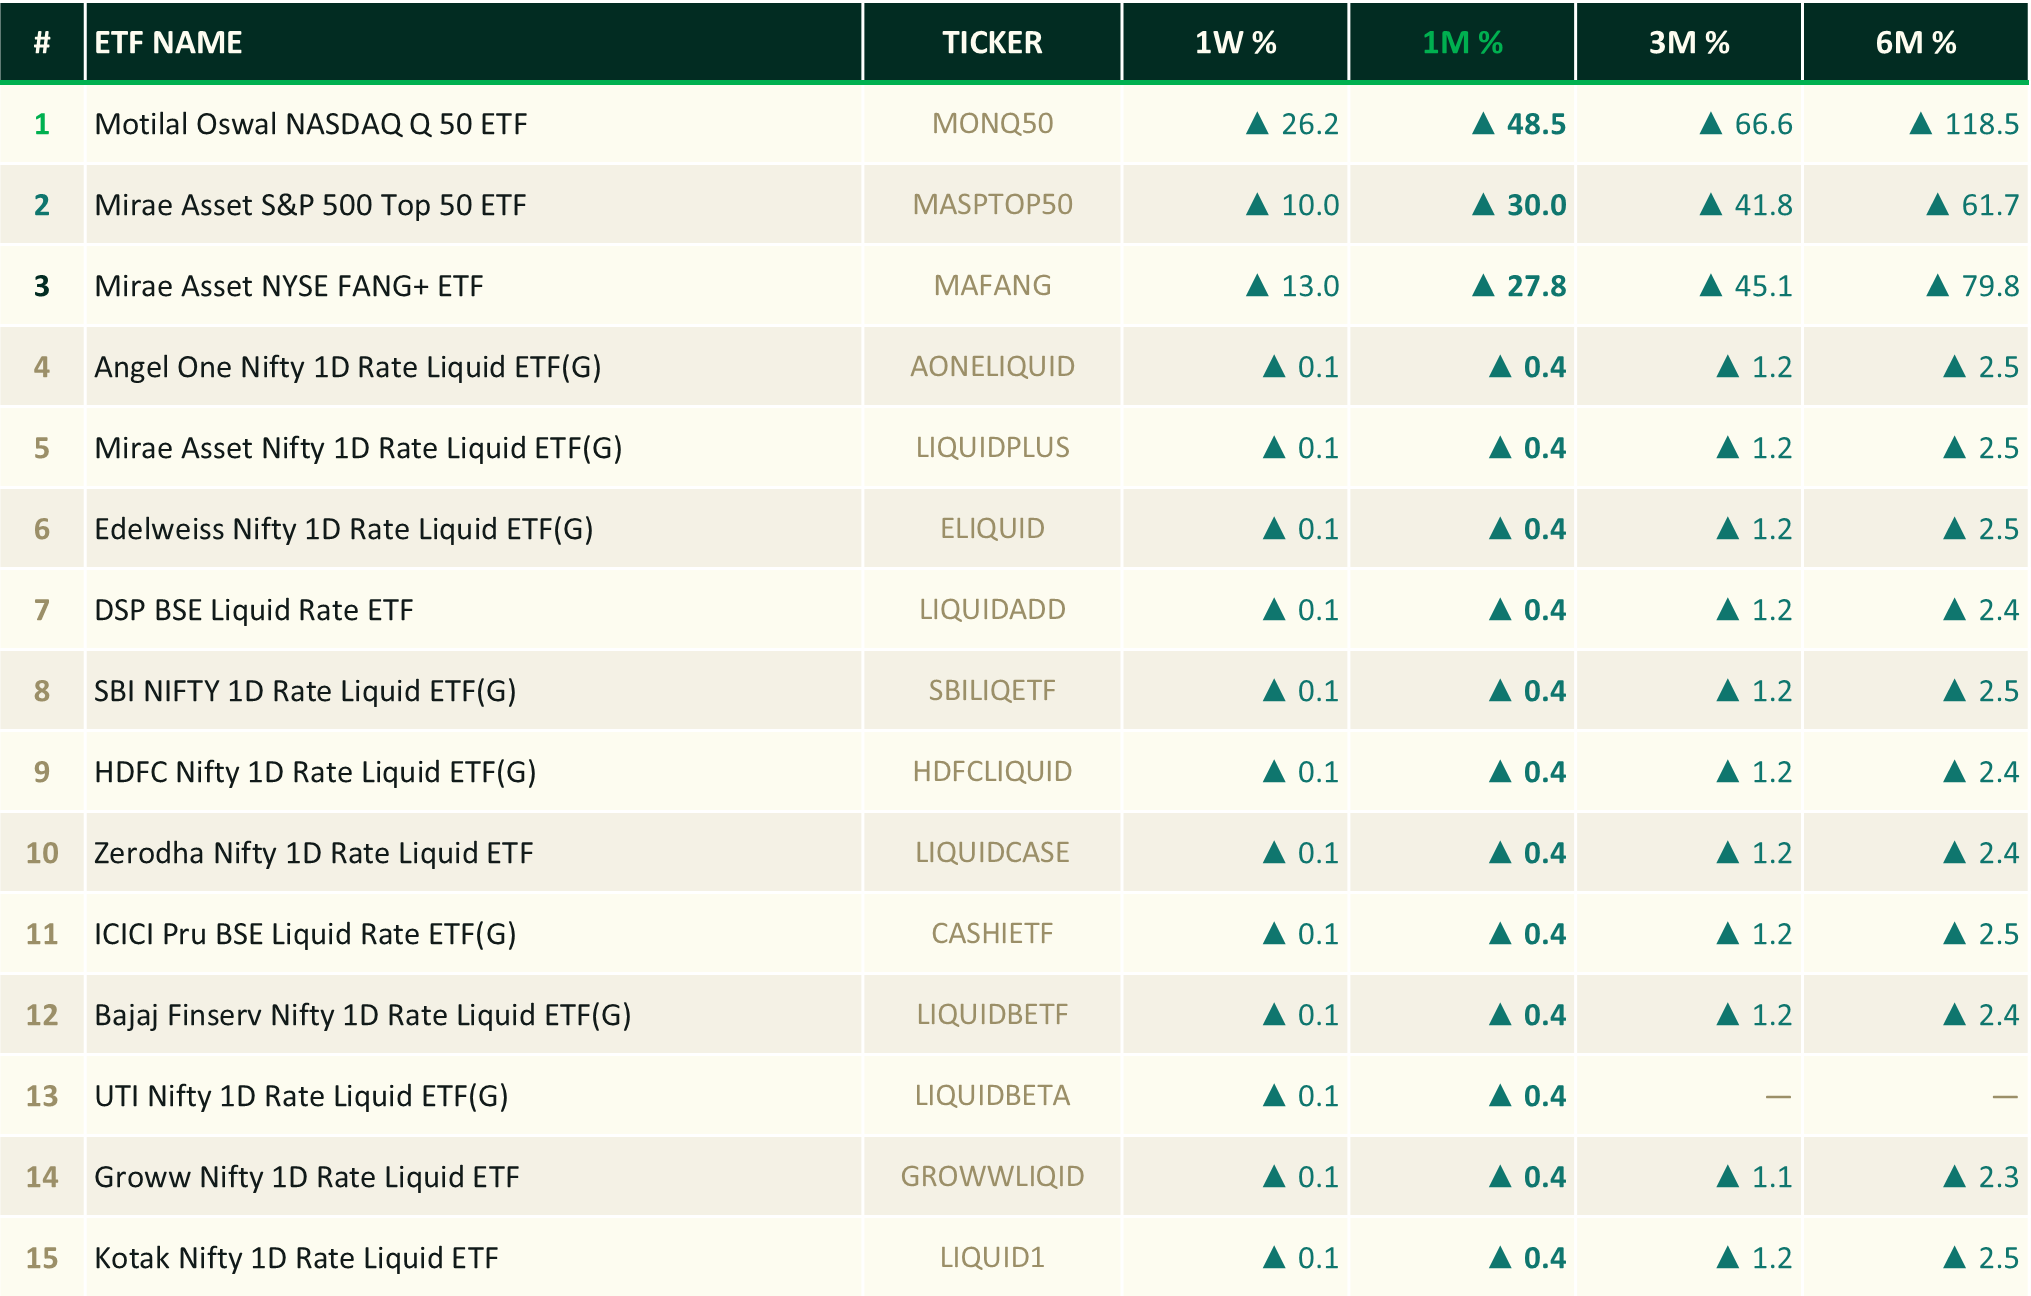
- Top 15 Performing ETFs
Nifty snaps losing streak, rises 0.44% WoW
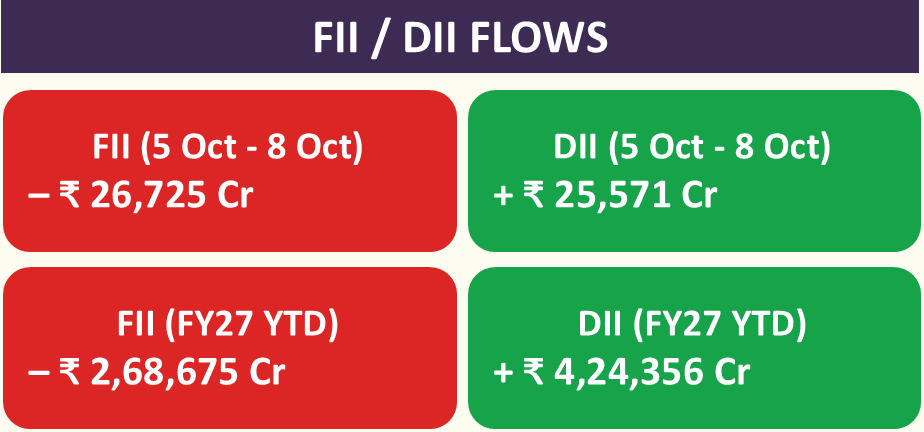
Week’s Recap
Ninth weekly decline: Nifty extended its losing streak to nine weeks, closing at 22,520.45 on persistent FII selling, high crude and global uncertainty.
RBI rate hike: The repo rate rose 25 bps to 5.50% on 7 Oct, raising borrowing-cost worries for banks, NBFCs and realty.
Crude above $100: Brent stayed elevated, threatening inflation, the import bill and corporate margins.
IT outperforms: Nifty IT bounced sharply on Friday, helped by TCS results.
Broader markets recover: Midcaps and smallcaps rebounded after heavy selling, but breadth must improve to confirm.
Rupee at fresh lows: It slid toward ₹96.80 per dollar on oil, outflows and dollar strength.
US yields elevated: Higher Treasury yields make dollar assets more attractive and weigh on emerging markets.
Next Week Ahead
India CPI inflation and IIP data (12 Oct): September inflation shows the oil and rate hike impact; IIP gauges manufacturing strength.
India WPI inflation (14 Oct) and trade data (around 15 Oct): WPI signals input-cost pressures; trade data shows the energy import impact.
US inflation and Treasury yields: A surprise or further rise would weigh on global risk assets.
Crude oil and USD/INR: Brent above $100 and the rupee near ₹96.80 remain key; watch RBI intervention.
Nifty levels: Support at 22,200–22,230; resistance at 22,800, then 23,000.
Q2 results season: Gathers pace, IT majors first.
Nifty 50 edges up this week – broader markets still lag; In Factors – Quality leads this week, Value lags
Capital Markets, FMCG lead this week; Realty lags sharply
Sector Rotation: Private Bank, Financials lead; Pharma weakens
Macro: Brent, rupee tick up; VIX eases 0.5%
Global 10Y Yields: US eases to 5.23% off highs; Japan near 3%
Top 15 Performing ETFs