Insights
Weekly Market Map - 19 September, 2026
Weekly Market Map
In this article
- Nifty slips 0.22% WoW as Fed, BOJ turn hawkish
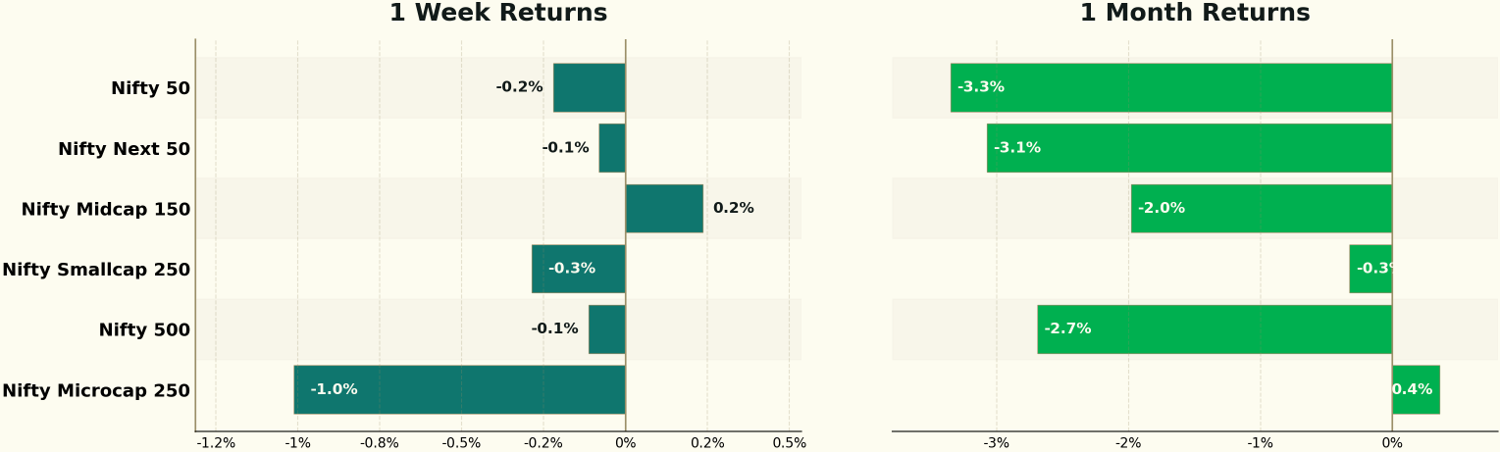
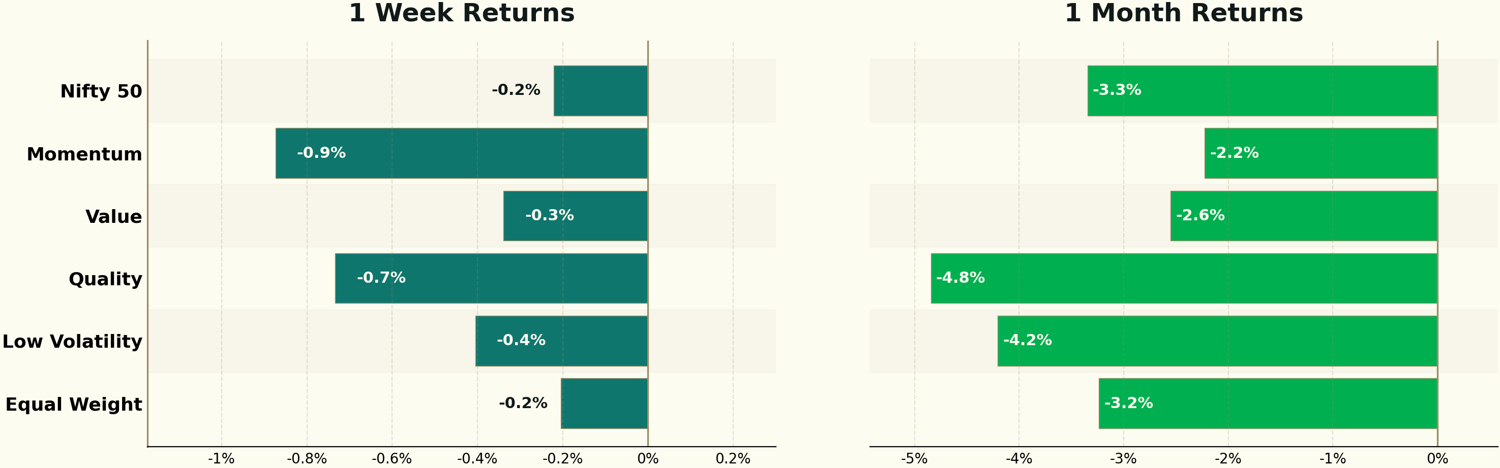
- Midcaps hold up this week – broad market mostly lower; In Factors – Equal Weight holds up best, Momentum lags
- FMCG, Healthcare, Pharma lead; Defence lags sharply
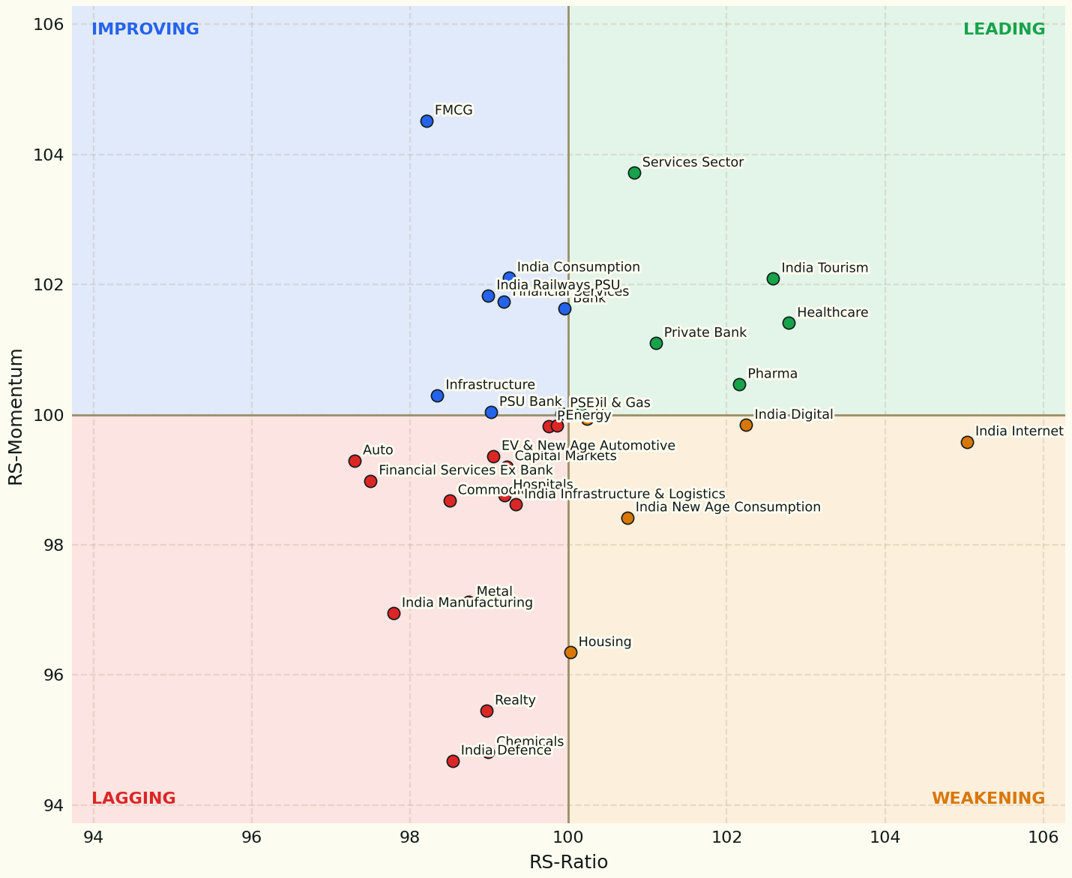
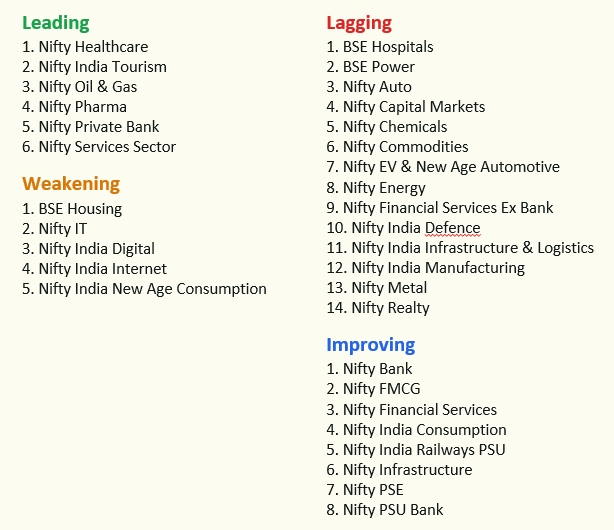
- Sector Rotation: Healthcare, Pharma lead; IT weakens further
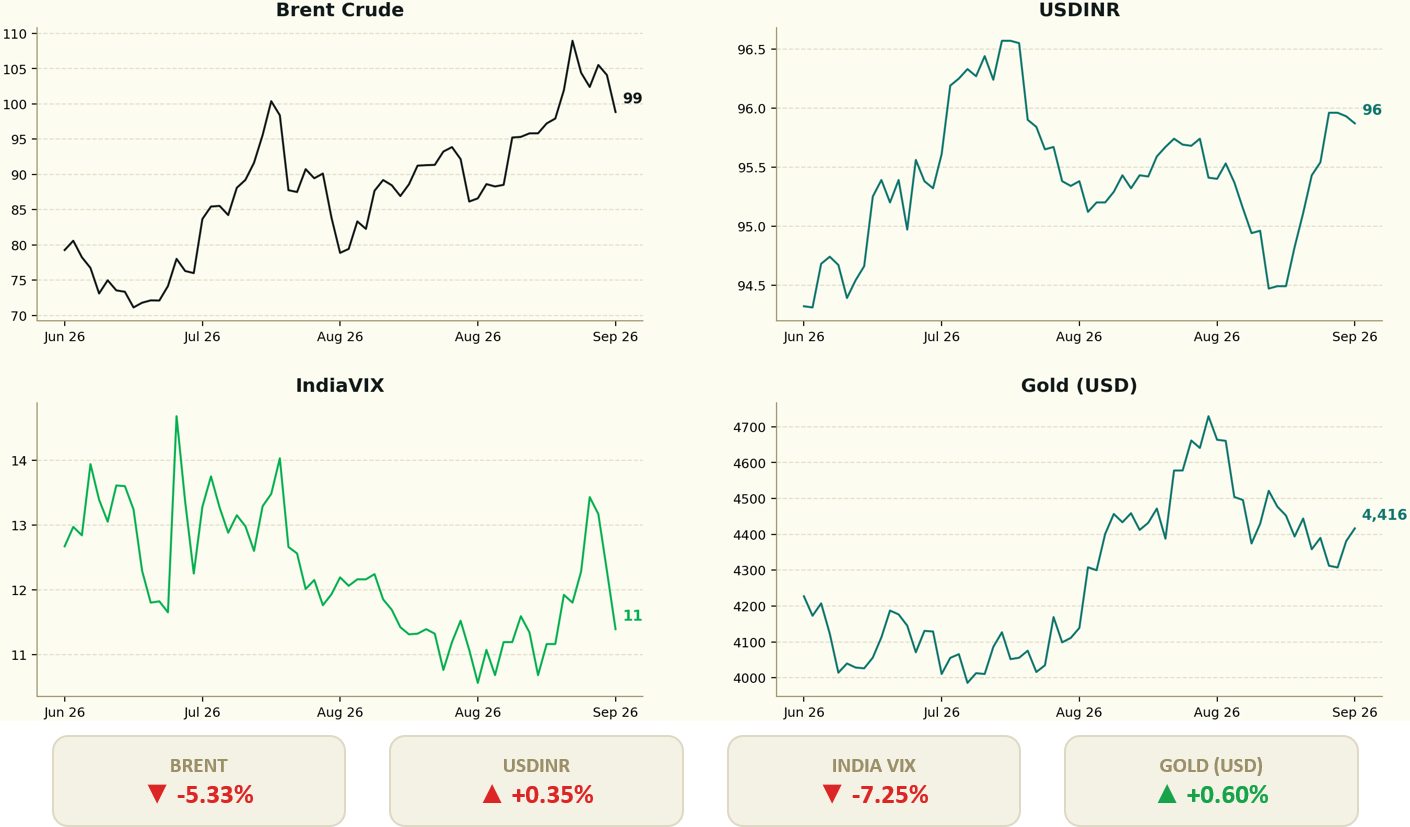
- Macro: Brent retreats 5.3% to $99; VIX cools 7.3%
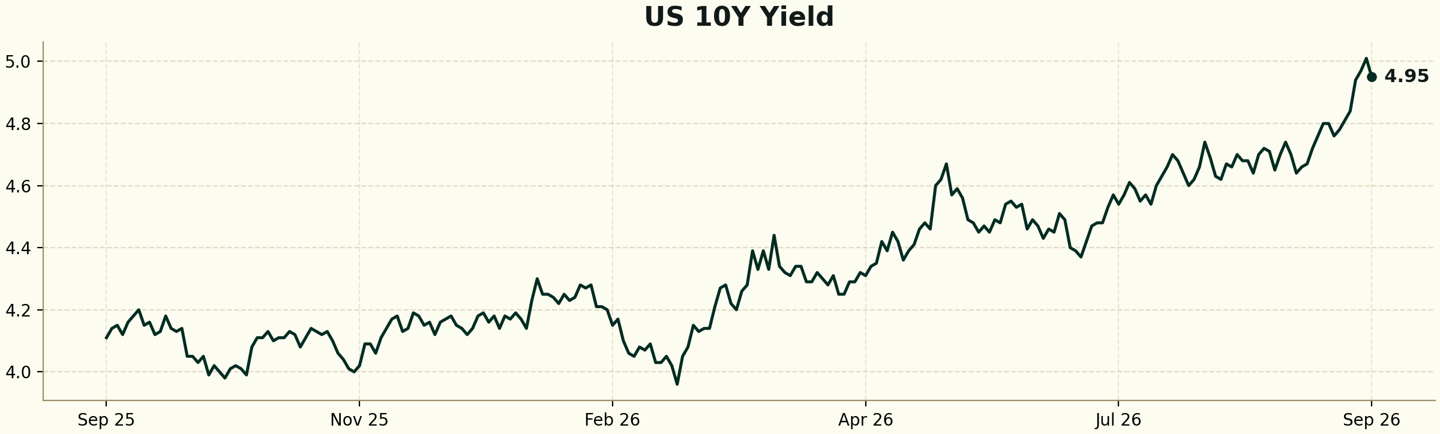
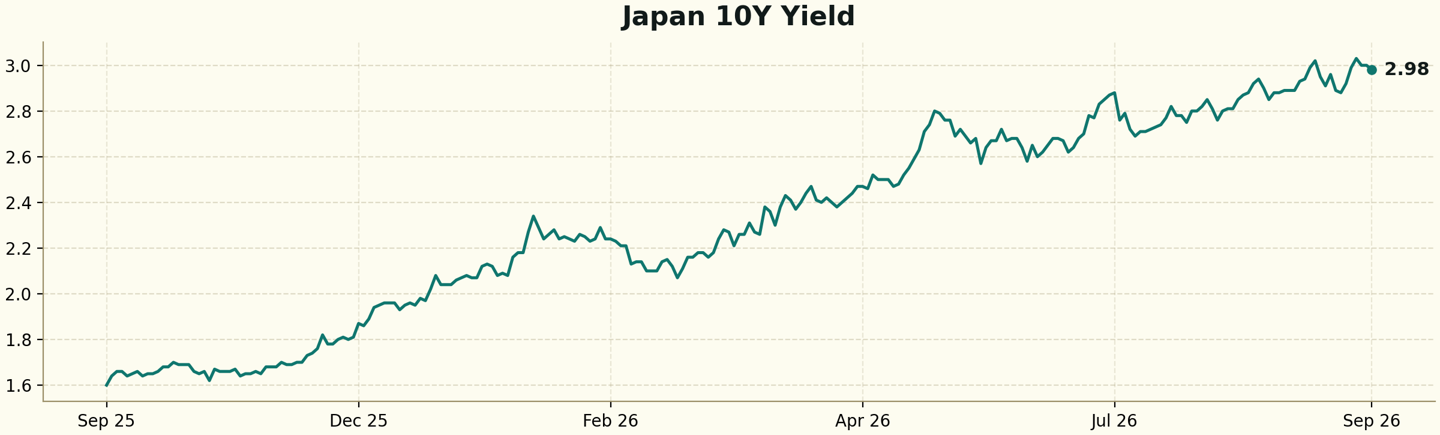
- Global 10Y Yields: US hits fresh high at 4.95%; Japan near 3%
- Stocks Showing Positive Quant Signals
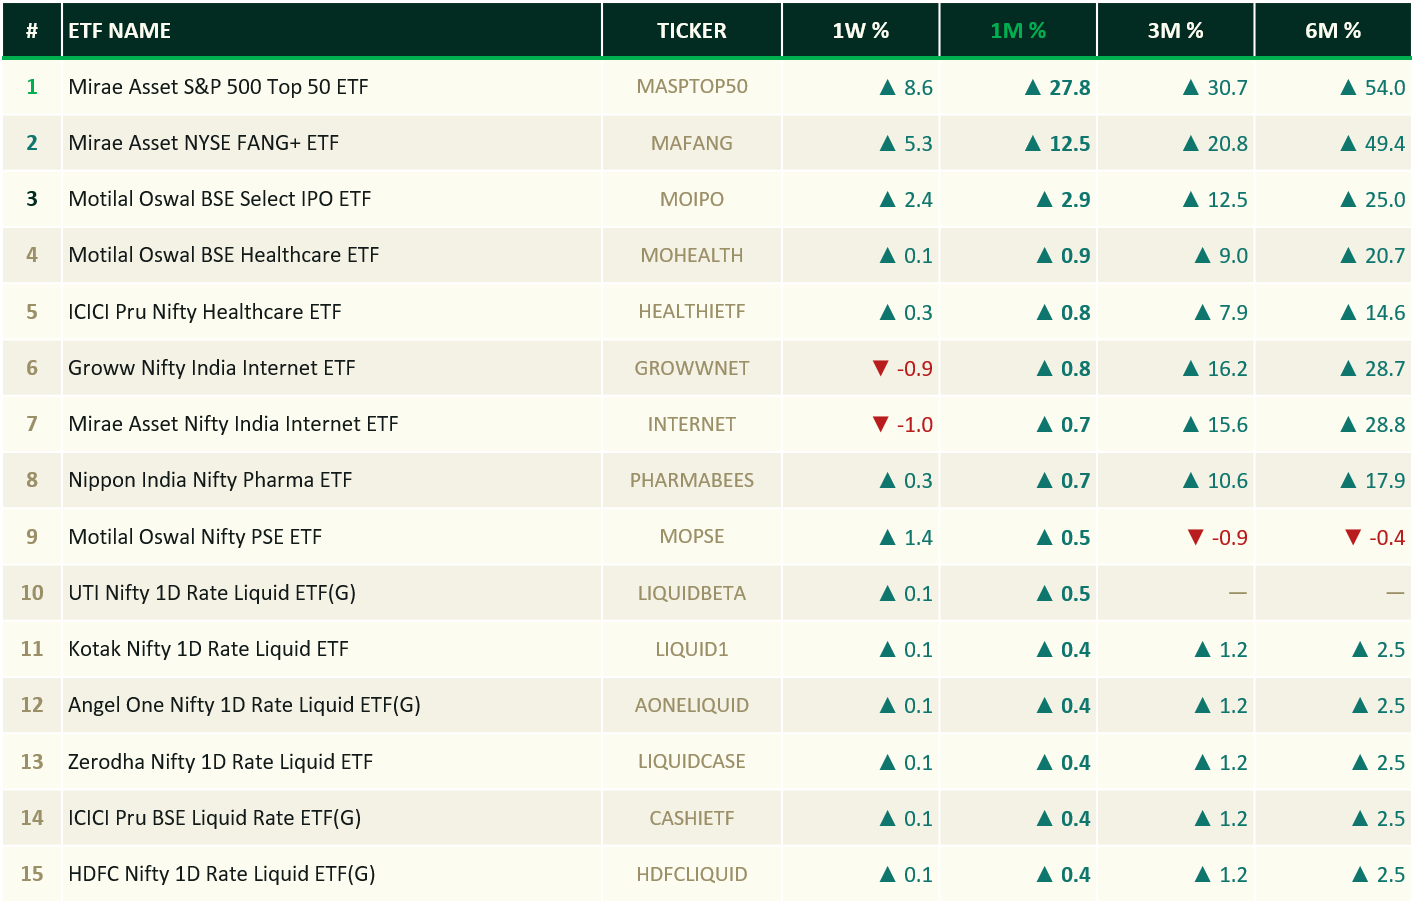
- Top 15 Performing ETFs
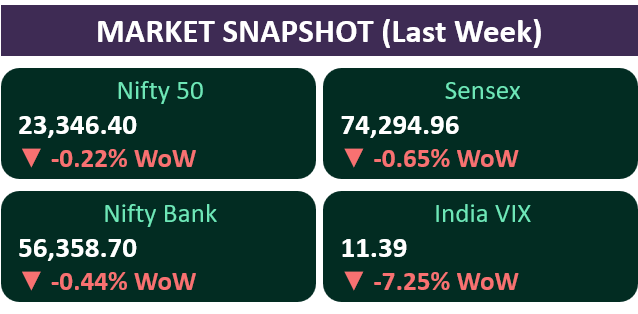
Nifty slips 0.22% WoW as Fed, BOJ turn hawkish
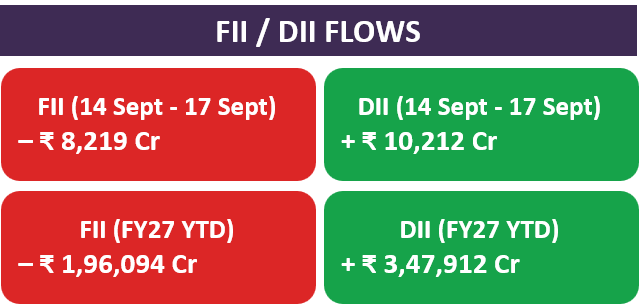
Week’s Recap
Nifty stayed under pressure, trading around 23,300–23,400, extending market weakness.
Crude oil stayed a key risk — Brent above $100/barrel, raising concerns over inflation and trade deficit.
Rupee remained weak — USD/INR near ₹95.8–96/$, pressured by high crude, FII outflows, and dollar strength.
Global central banks turned hawkish — The US Fed raised rates by 25 bps to 3.75%–4.00%, and the BOJ hiked by 25 bps to 1.25% (a multi-decade high), pressuring global liquidity and carry trades.
Stock-specific approach gaining importance — With 10 of 16 sectors posting weekly losses, focus shifts to individual companies, earnings, and sector catalysts.
Breadth improved toward the weekend — midcap and smallcap indices outperformed during Friday's session.
Next Week Ahead
SNB rate decision (24 Sept) — Deposit rate likely held at 0.0%; Schlegel's press conference in focus for tone.
PBOC rate decision (21 Sept) — 1-year LPR likely held at 3.00%; a surprise could ripple into Asian equity sentiment.
Crude oil / Middle East — Fresh escalation could keep Brent elevated, pressuring India's inflation, rupee, and oil-sensitive sectors.
Small & midcaps — Watch for a rebound vs. continued underperformance against large caps amid elevated volatility.
IPO / primary market activity — NSE listing plus new launches and allotments — a gauge of retail and institutional risk appetite.
Nifty support — Holding 23,300–23,500 is key; a break risks a slide toward 23,000, while reclaiming 23,700–23,900 signals bullish momentum.
Midcaps hold up this week – broad market mostly lower; In Factors – Equal Weight holds up best, Momentum lags
FMCG, Healthcare, Pharma lead; Defence lags sharply
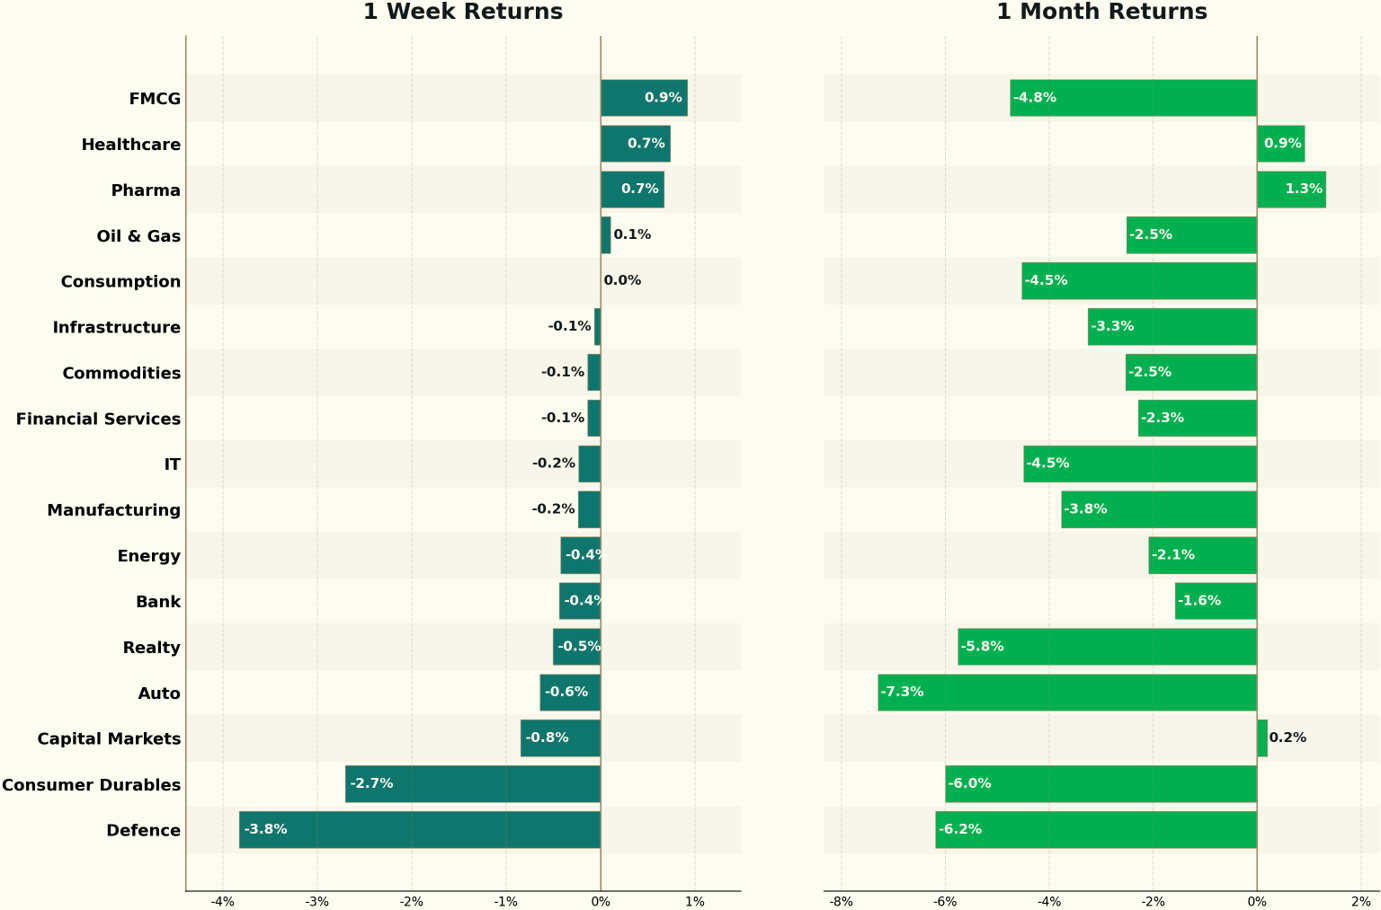
Sector Rotation: Healthcare, Pharma lead; IT weakens further
Macro: Brent retreats 5.3% to $99; VIX cools 7.3%
Global 10Y Yields: US hits fresh high at 4.95%; Japan near 3%
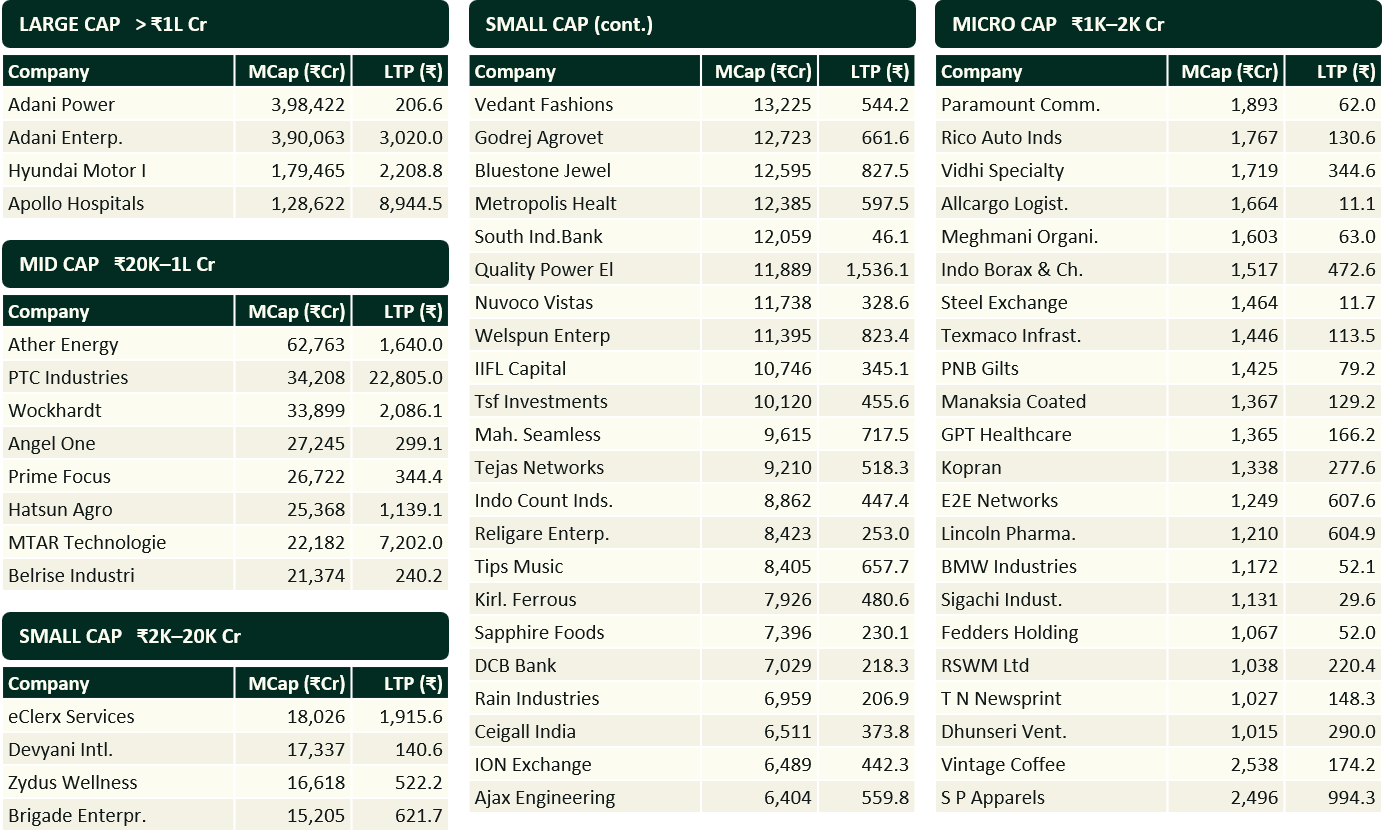
Stocks Showing Positive Quant Signals
Week of 14 September – 18 September • Native Quant Score – 85 Stocks flagged
Stage2 Stocks which entered between April-August, 2026 delivered Avg.
Annualized Return of 34.9% with avg. holding period of 35 days
Top 15 Performing ETFs