Insights
Weekly Market Map - 2 October, 2026
Weekly Market Map
In this article
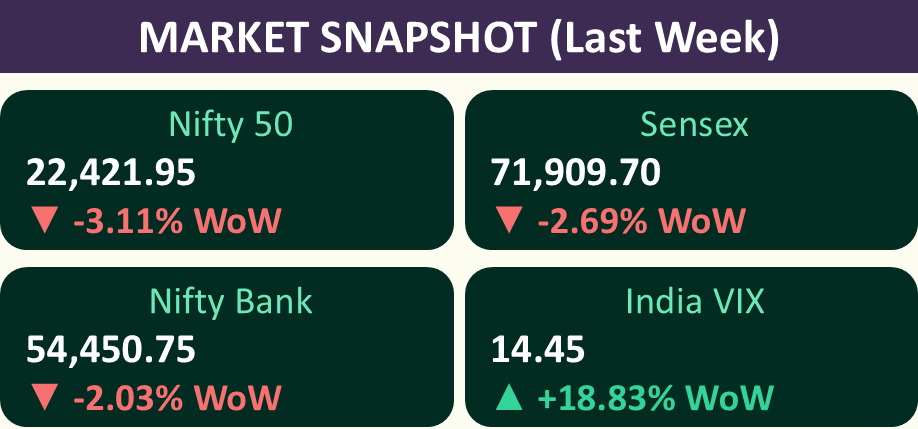
- Nifty falls 3.11% WoW, eighth straight weekly loss
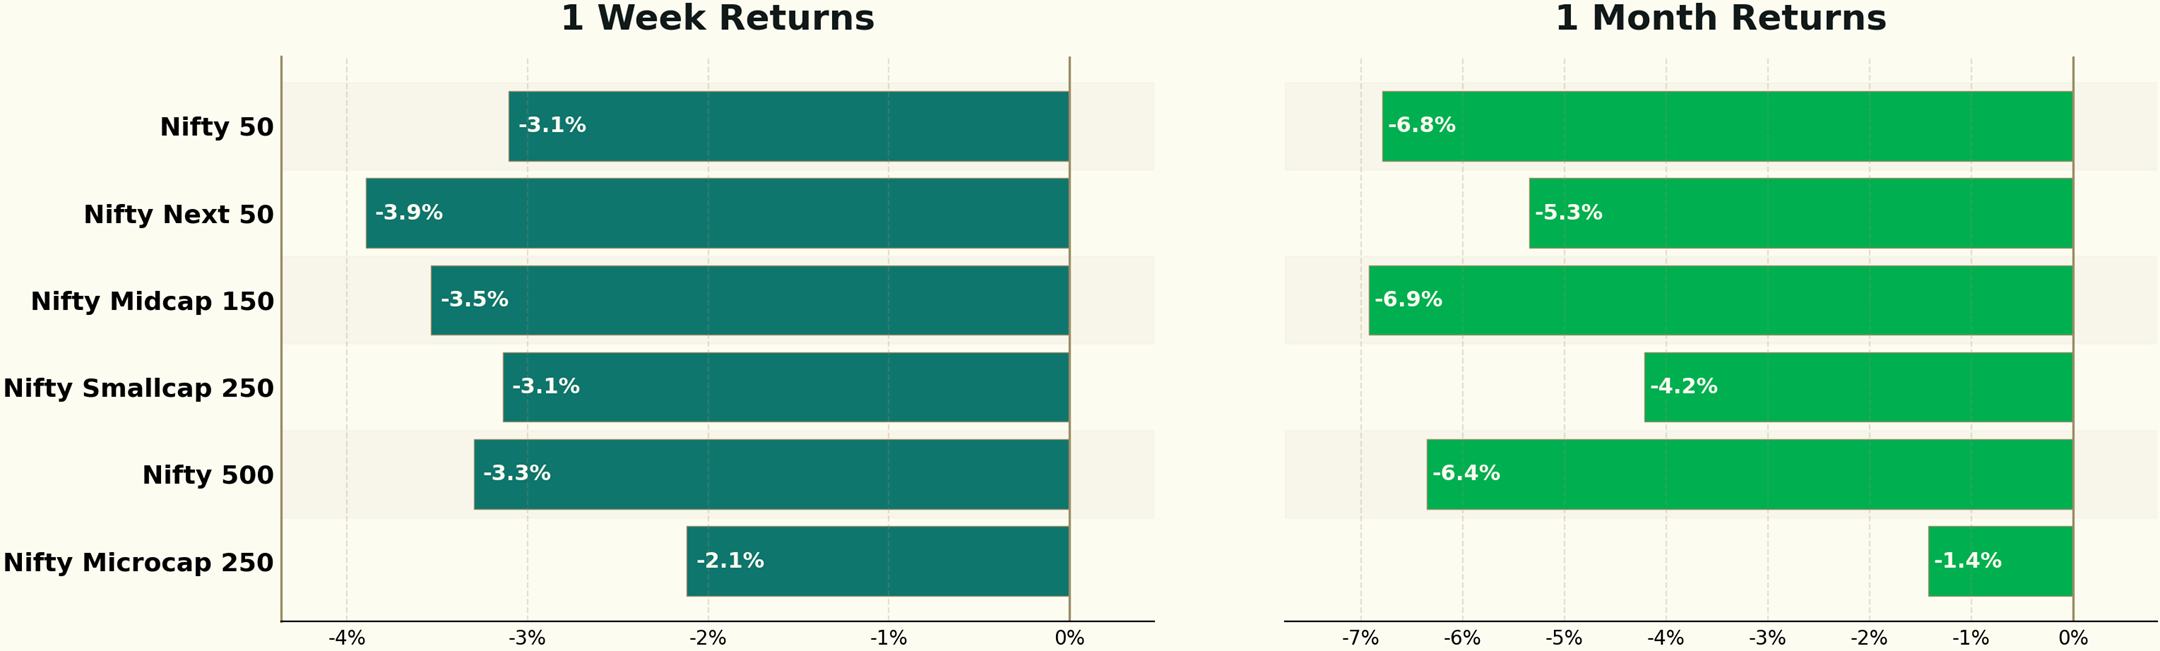
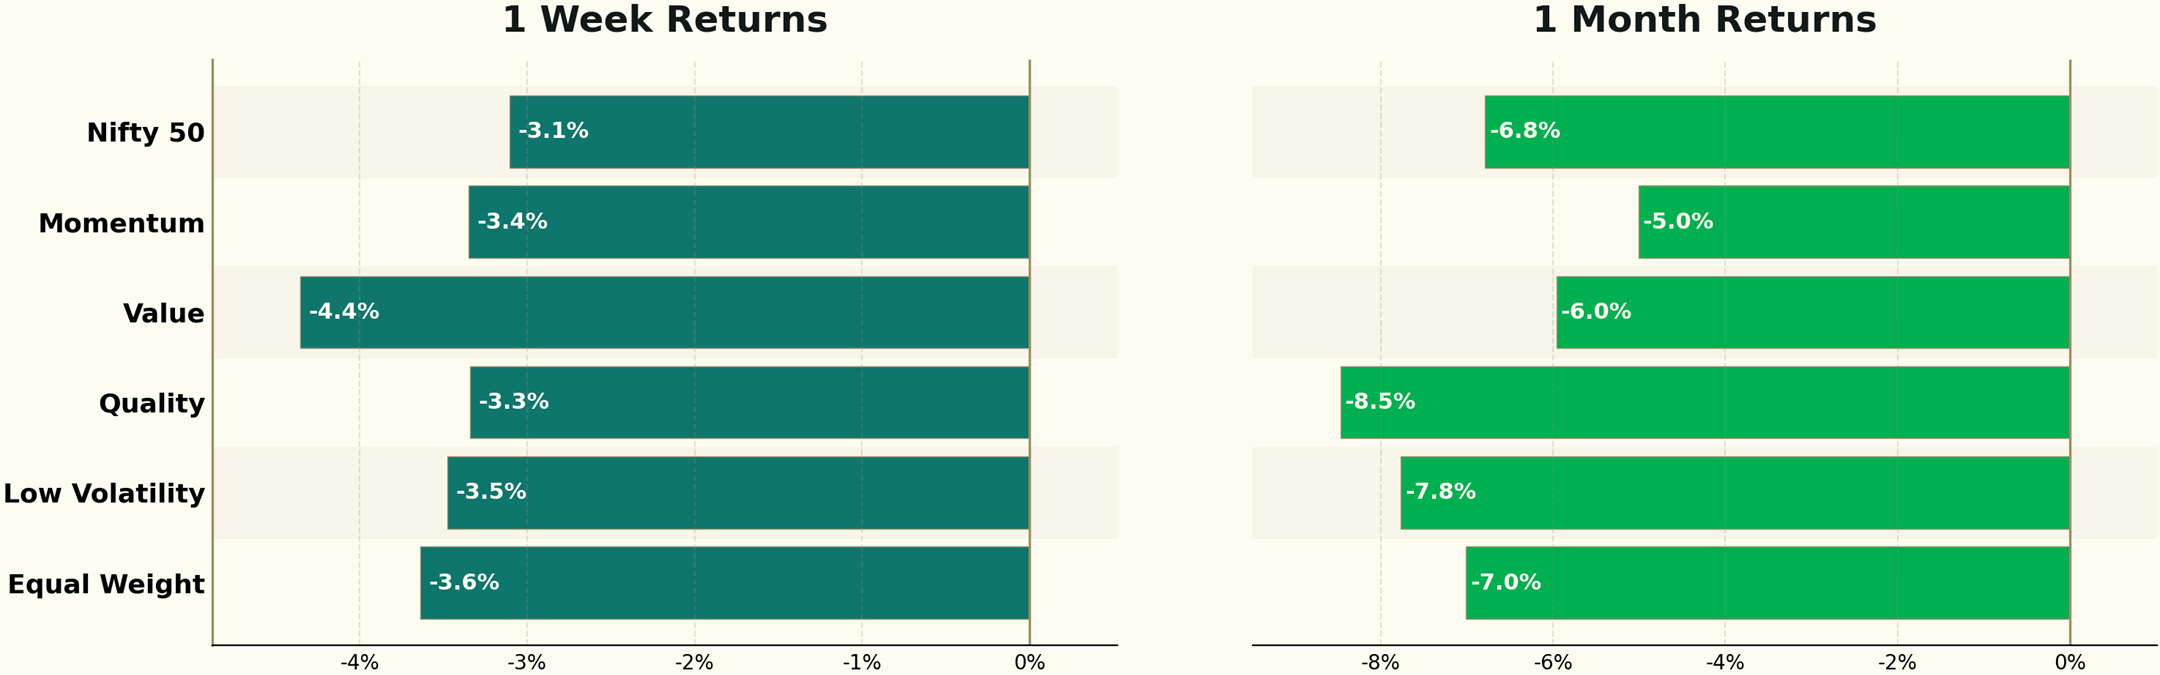
- Broad market falls across the board this week – microcaps least hurt; In Factors – Momentum holds up best this week, Value lags
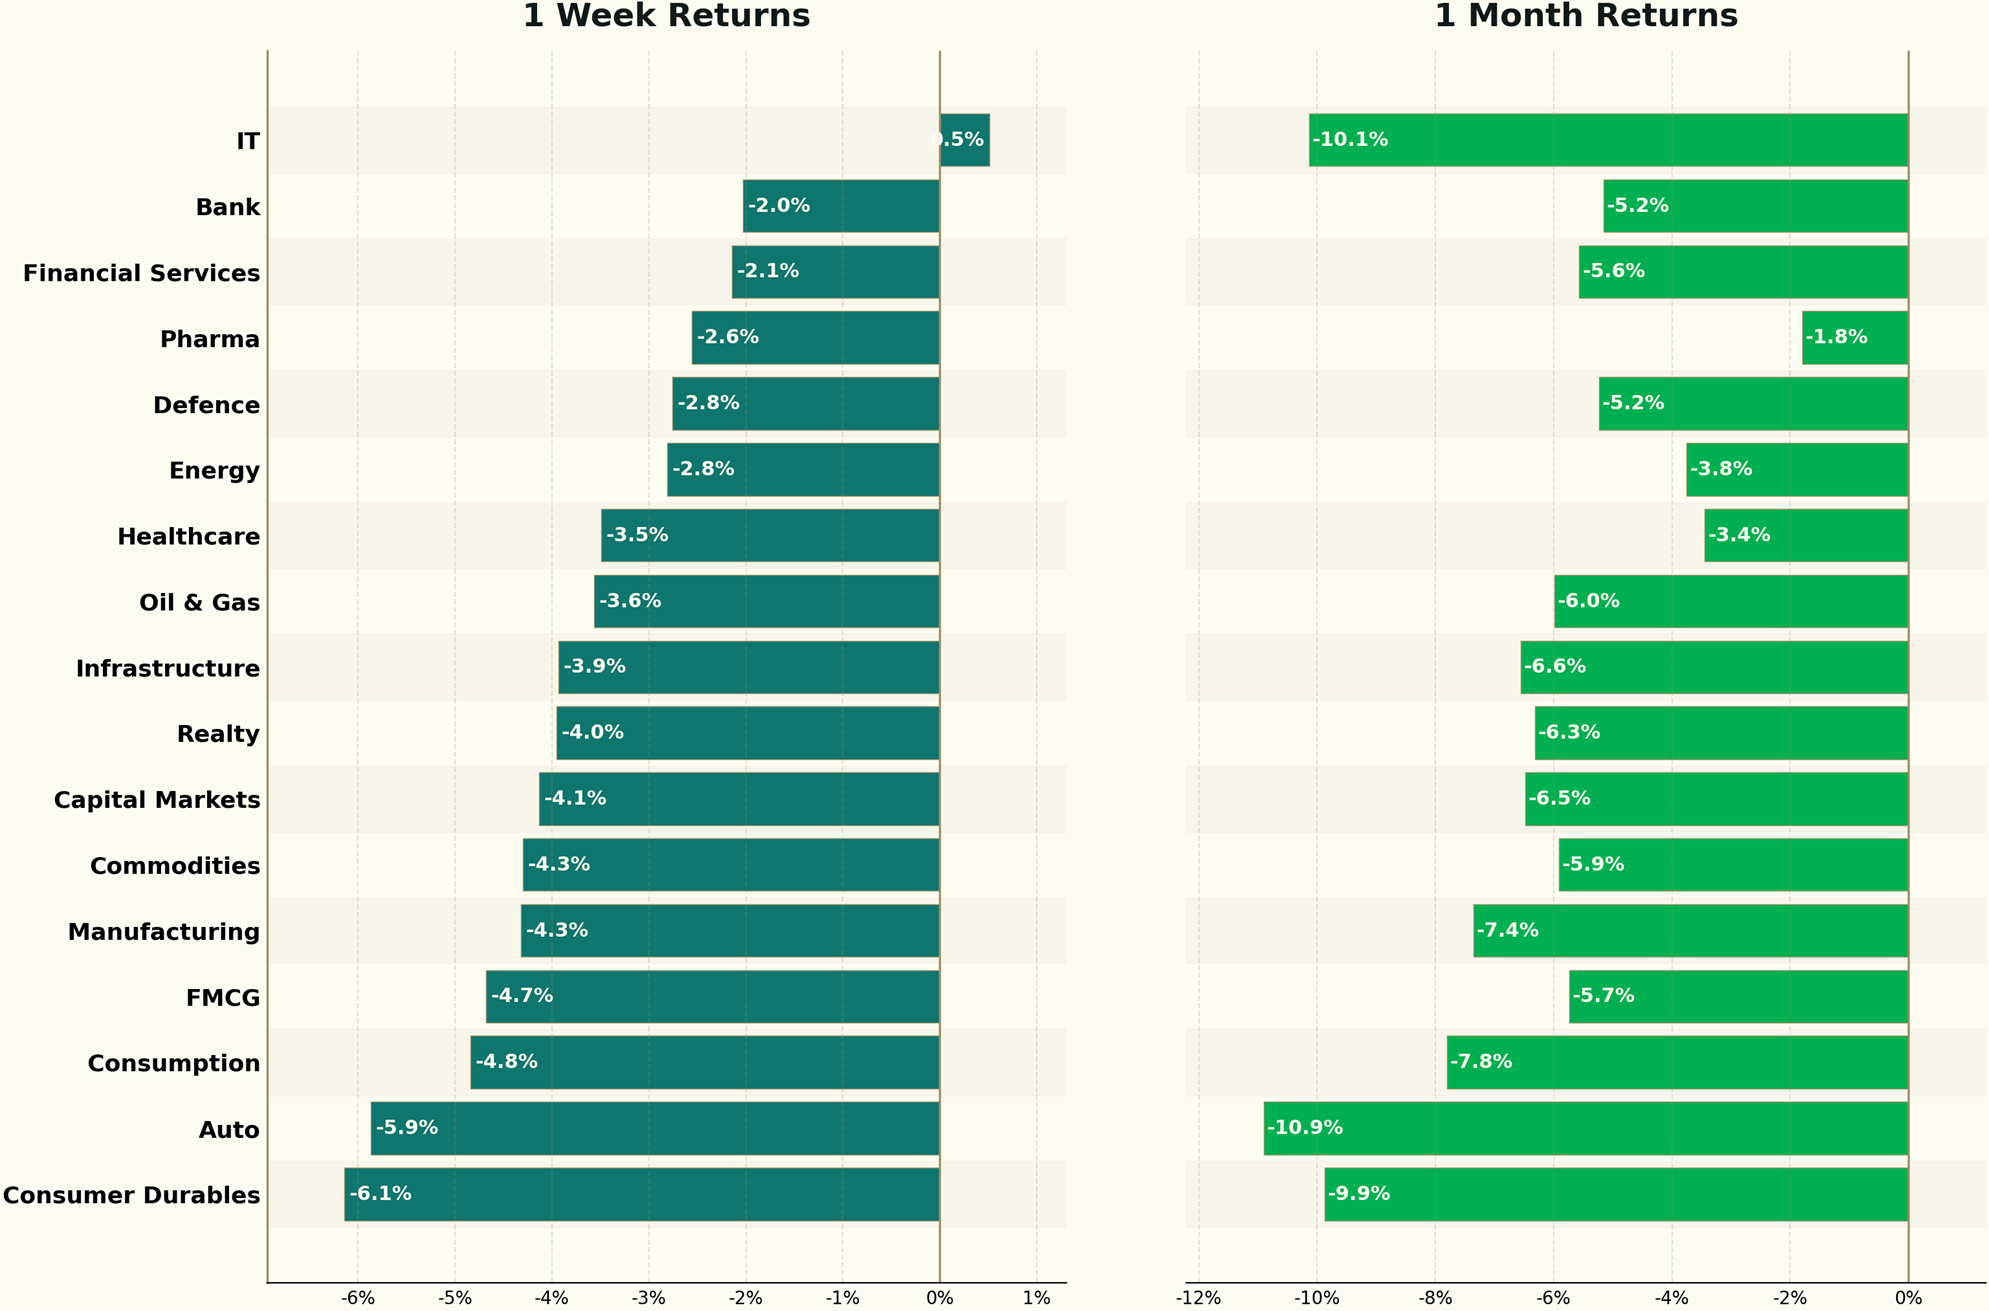
- IT only sector in green this week; Auto, Durables lag sharply
- Sector Rotation: Power, Energy, FMCG lead; Healthcare weakens
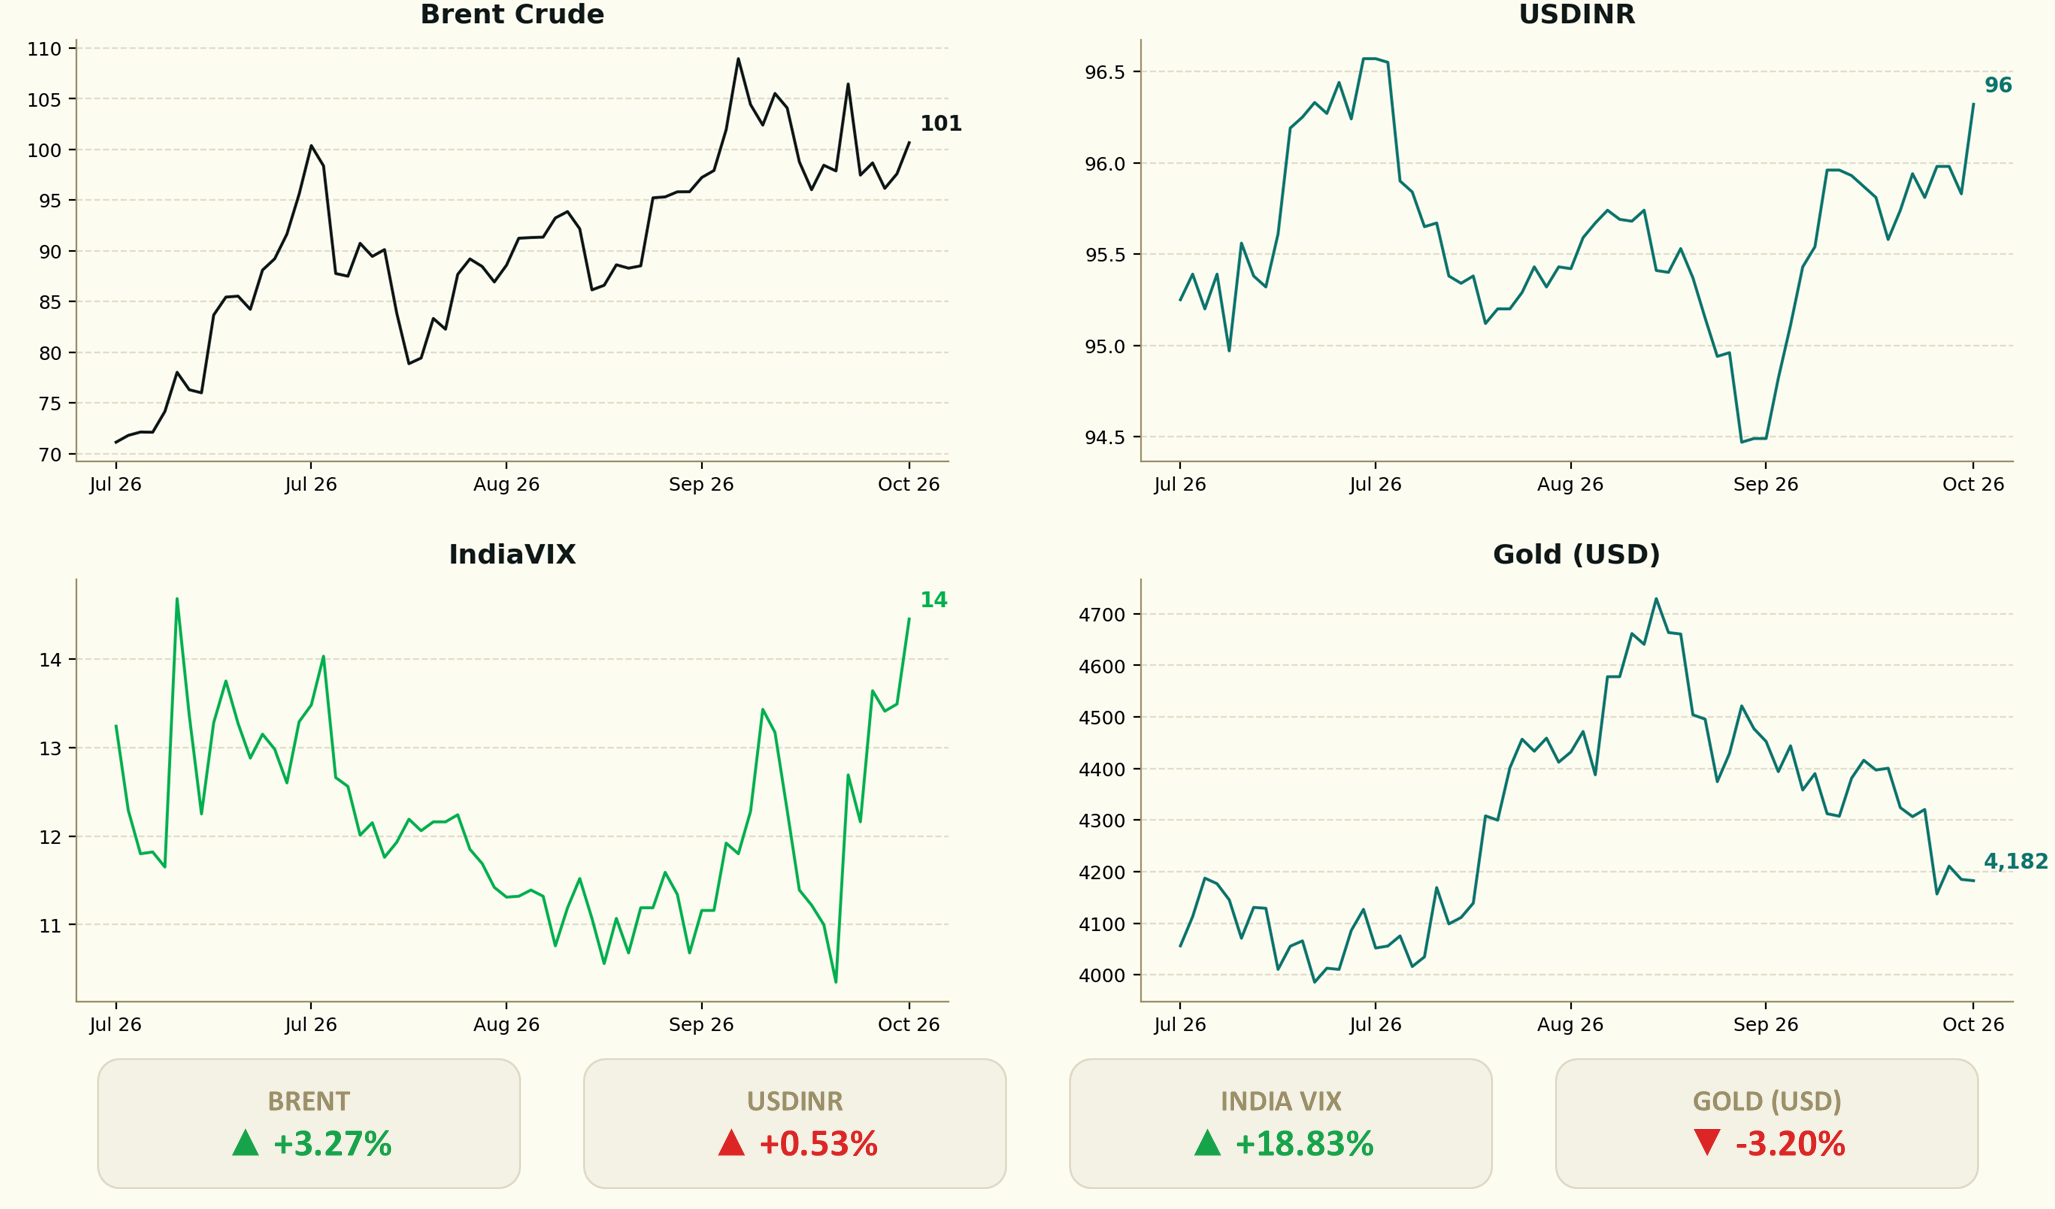
- Macro: Brent rises 3.3% to $101; VIX spikes 18.8%
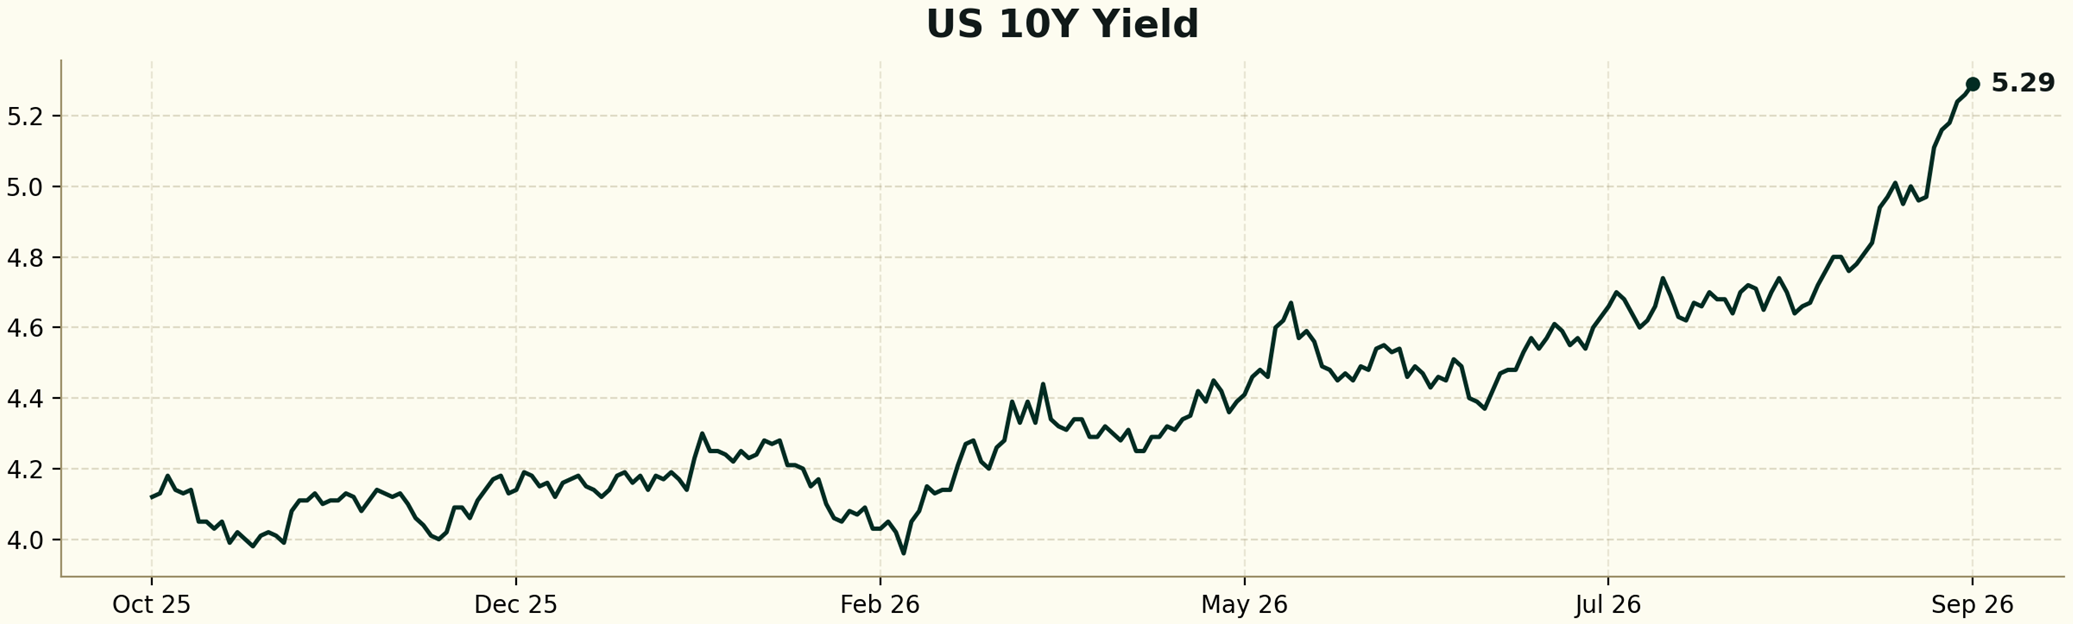
- Global 10Y Yields: US surges to 5.29%, multi-decade high
- Stocks Showing Positive Quant Signals
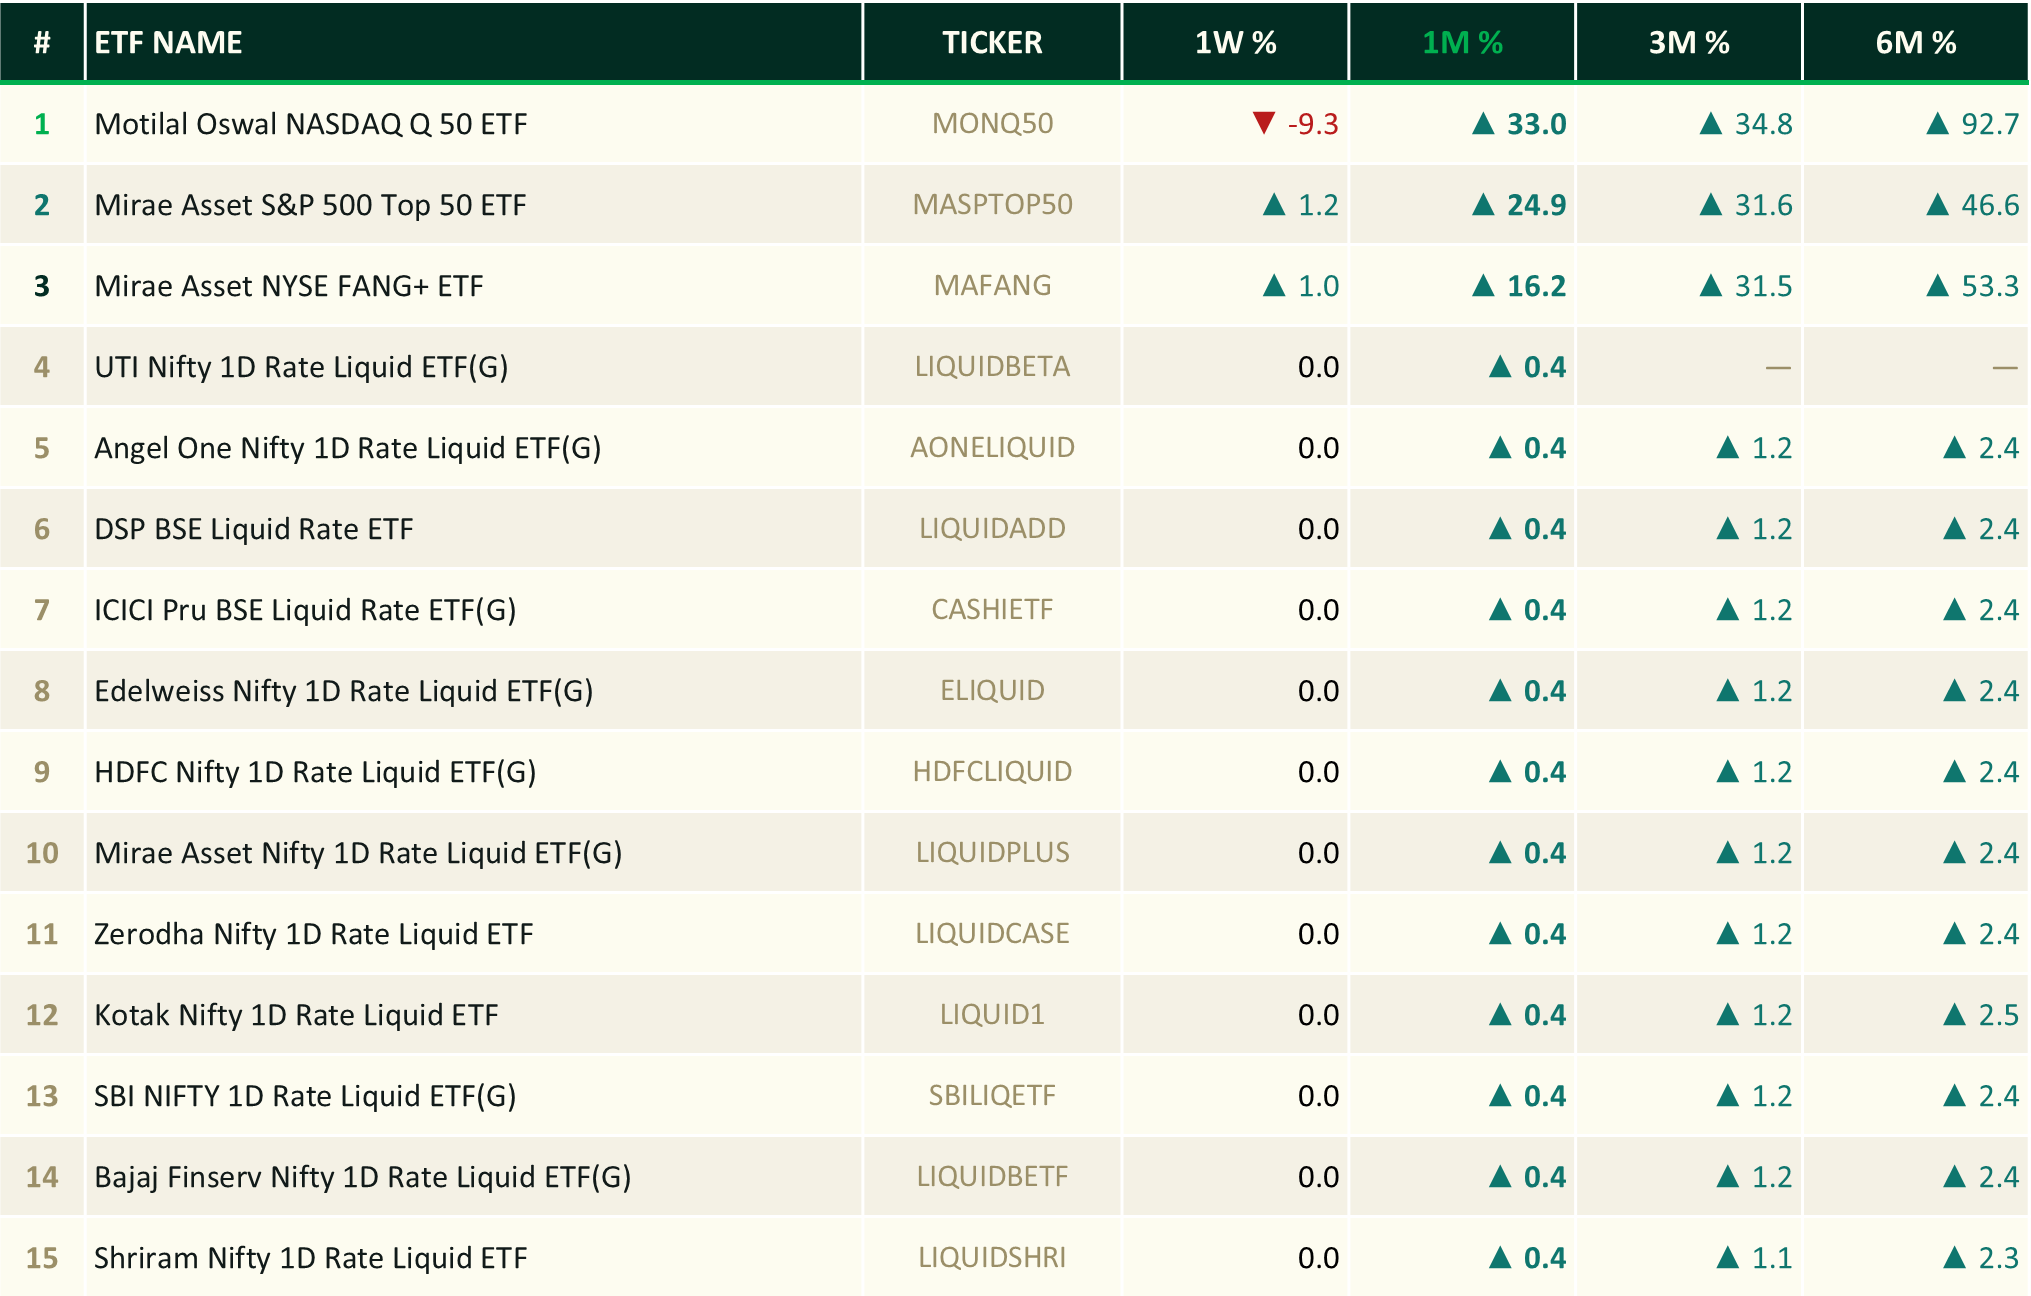
- Top 15 Performing ETFs
Nifty falls 3.11% WoW, eighth straight weekly loss
Week’s Recap
Eighth straight weekly loss: Nifty closed at 22,422, down about 3.1% for the week. It fell about 6.1% in September.
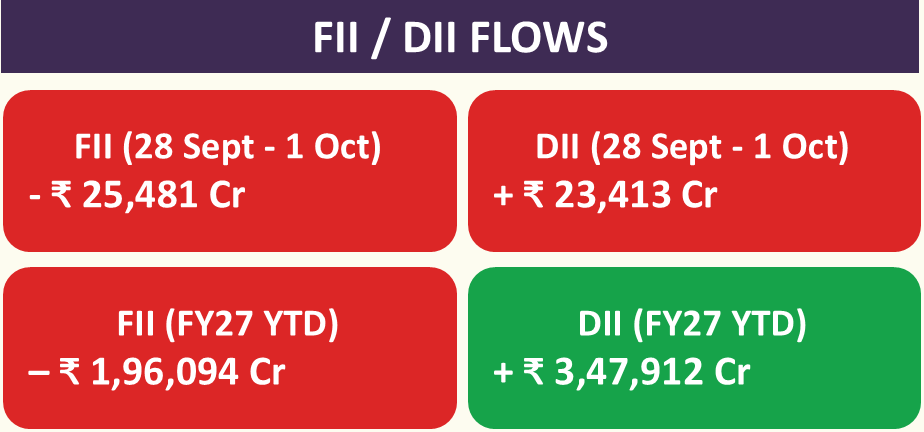
FII selling continues: FIIs sold about ₹10,000 crore on 30 Sept alone. DIIs are absorbing only part of it.
Crude stays above $100: Brent ranged $99–107 on Hormuz uncertainty.
Rupee slips past ₹96/USD: Costly crude and FII outflows are the pressure, with RBI intervention the main support.
US yields near 20-year highs: The 10-year was about 5.2–5.3% and the 30-year about 5.56%. Possible Fed hikes are pulling money out of emerging markets.
RBI hike expected: August CPI rose to 4.82% (July: 4.45%). Most economists expect a 25 bp hike to 5.50% on 7 Oct.
Auto stocks fall despite strong sales: Nifty Auto slipped 3% on Thursday even though Maruti sold 2.36 lakh units (+24.4% YoY). Crude and rates are weighing on the stocks, not demand.
Next Week Ahead
RBI MPC (5–7 Oct): The decision is on 7 Oct, and a 25 bp hike to 5.50% is expected.
US jobs report: A strong print adds to rate-hike fears.
Crude and Hormuz: A US–Iran deal would pull Brent down, and a breakdown could push it above $107.
USD/INR near ₹96: Watch for RBI intervention.
US Treasury yields: Further rises would weigh on global risk assets.
Nifty levels: Support is at 22,217. Resistance is at 22,800, then 23,000–23,100.
Q2 results season: It starts around mid-October, with IT majors first.
Broad market falls across the board this week – microcaps least hurt; In Factors – Momentum holds up best this week, Value lags
IT only sector in green this week; Auto, Durables lag sharply
Sector Rotation: Power, Energy, FMCG lead; Healthcare weakens
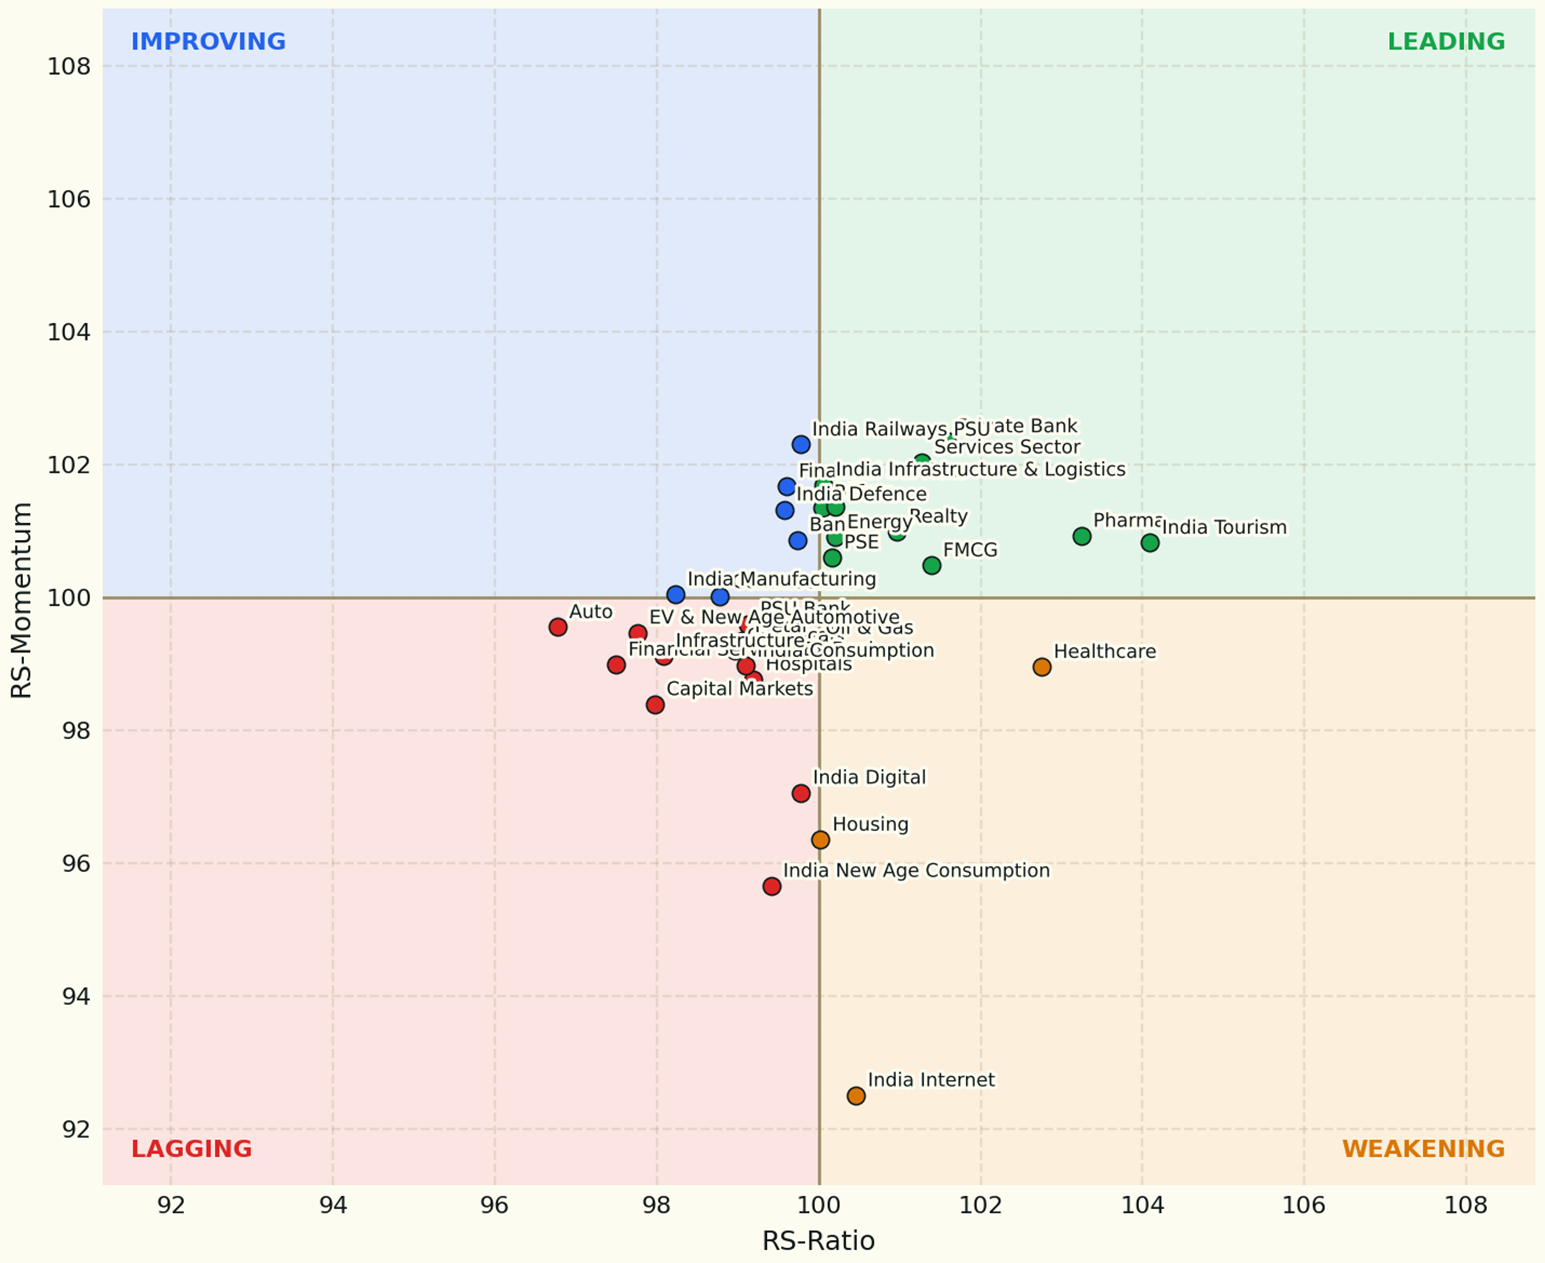
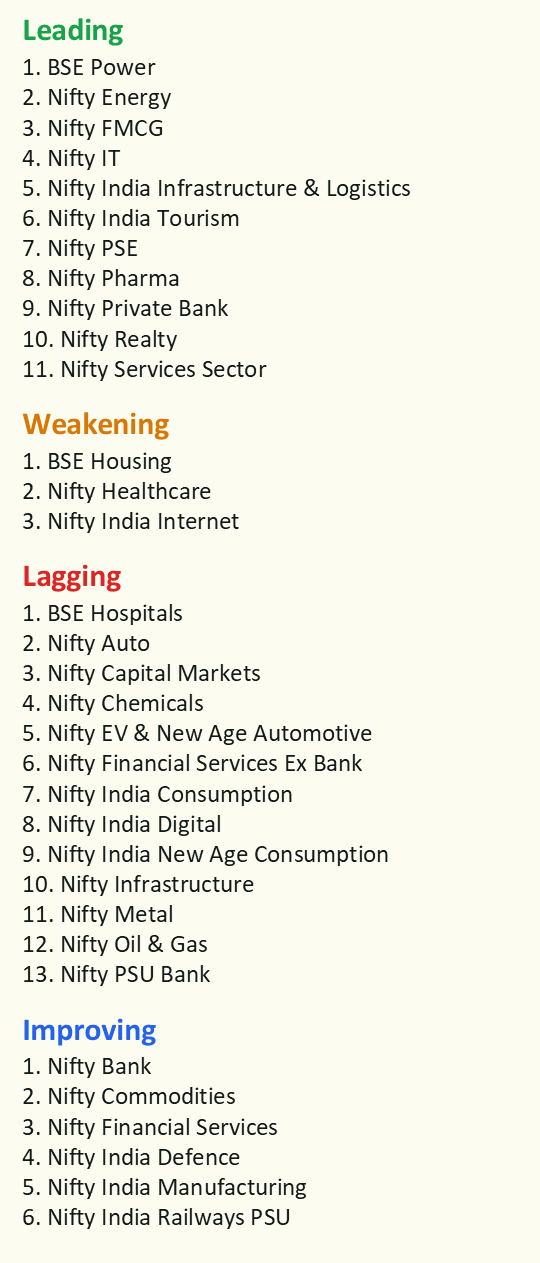
Macro: Brent rises 3.3% to $101; VIX spikes 18.8%
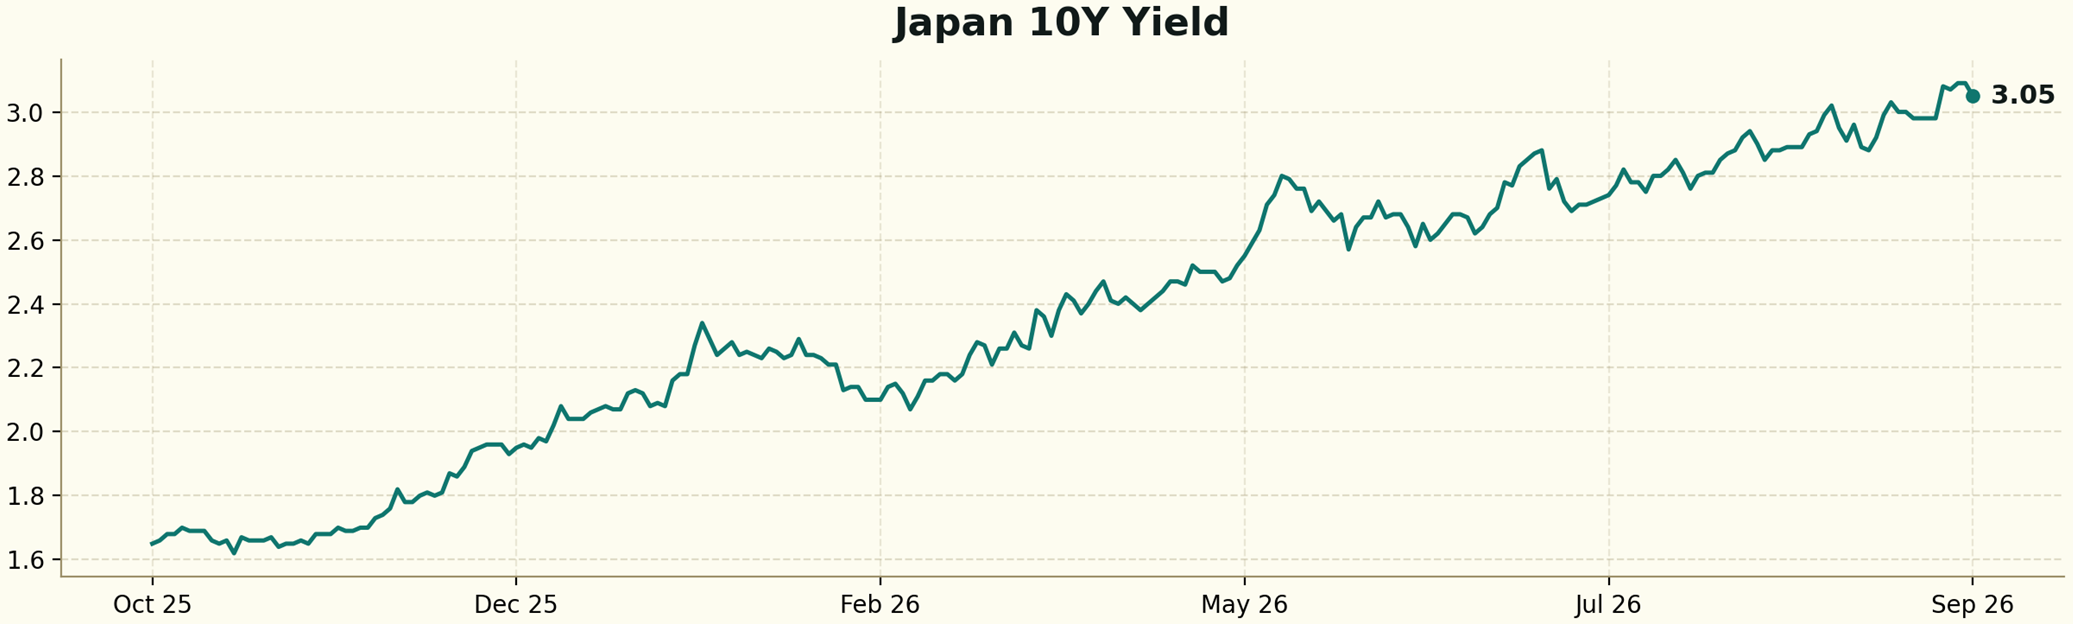
Global 10Y Yields: US surges to 5.29%, multi-decade high
Stocks Showing Positive Quant Signals
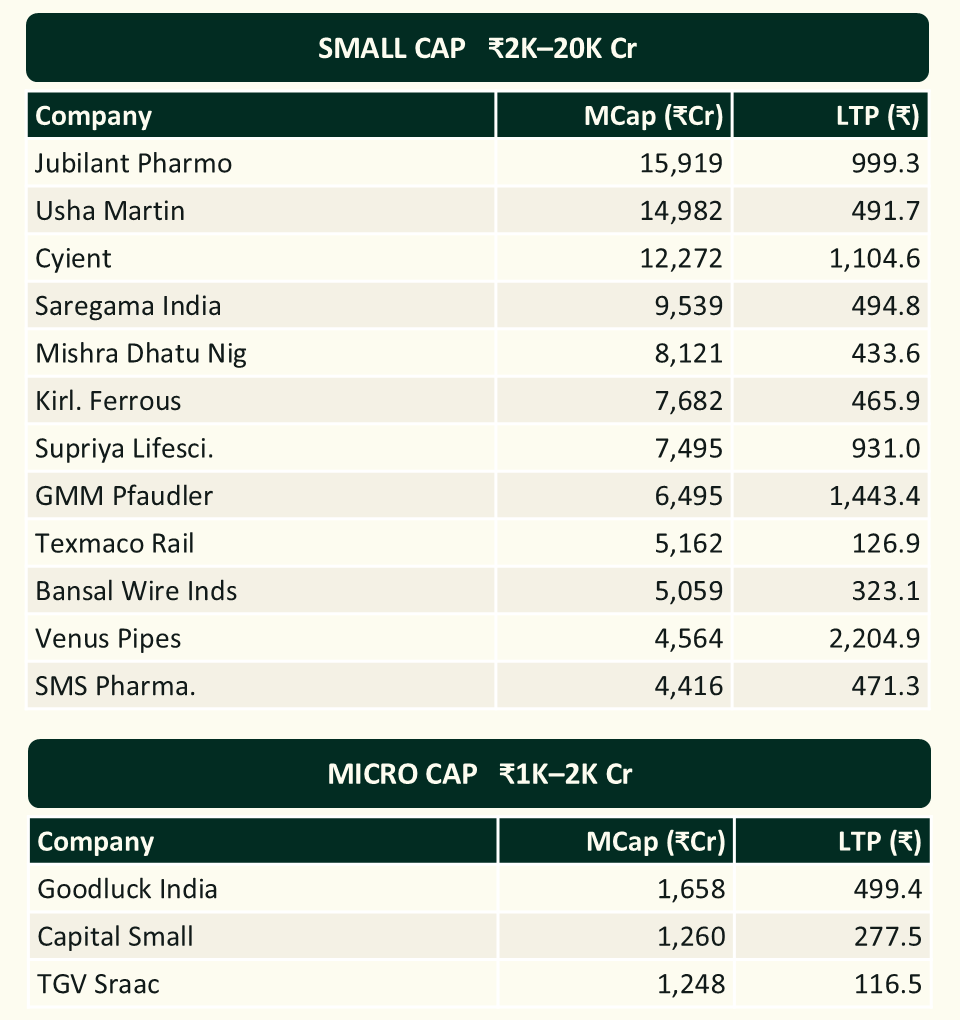
Week of 28 September – 1 October • Native Quant Score – 15 Stocks flagged
Stage 2 Stocks which entered between April-September, 2026 delivered Avg.
Annualized Return of 21.8% with avg. holding period of 36 days
Top 15 Performing ETFs