Insights
Weekly Market Map - 24 October, 2026
Weekly Market Map
In this article
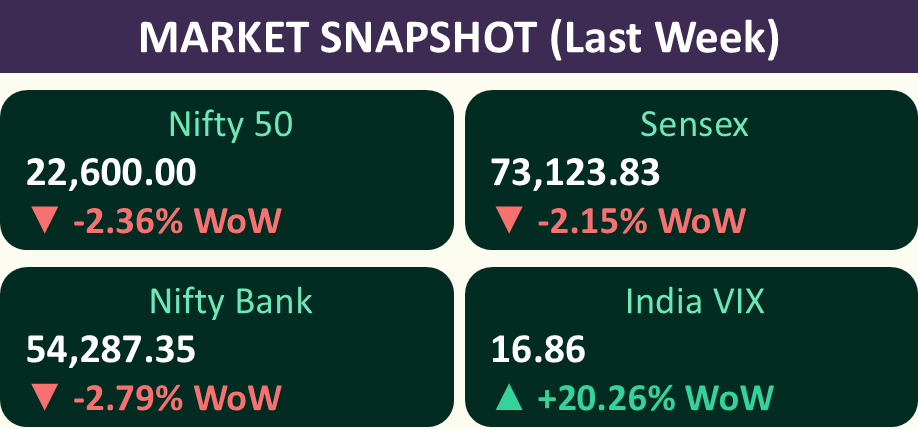
- Nifty falls 2.36% WoW as India VIX spikes 20%
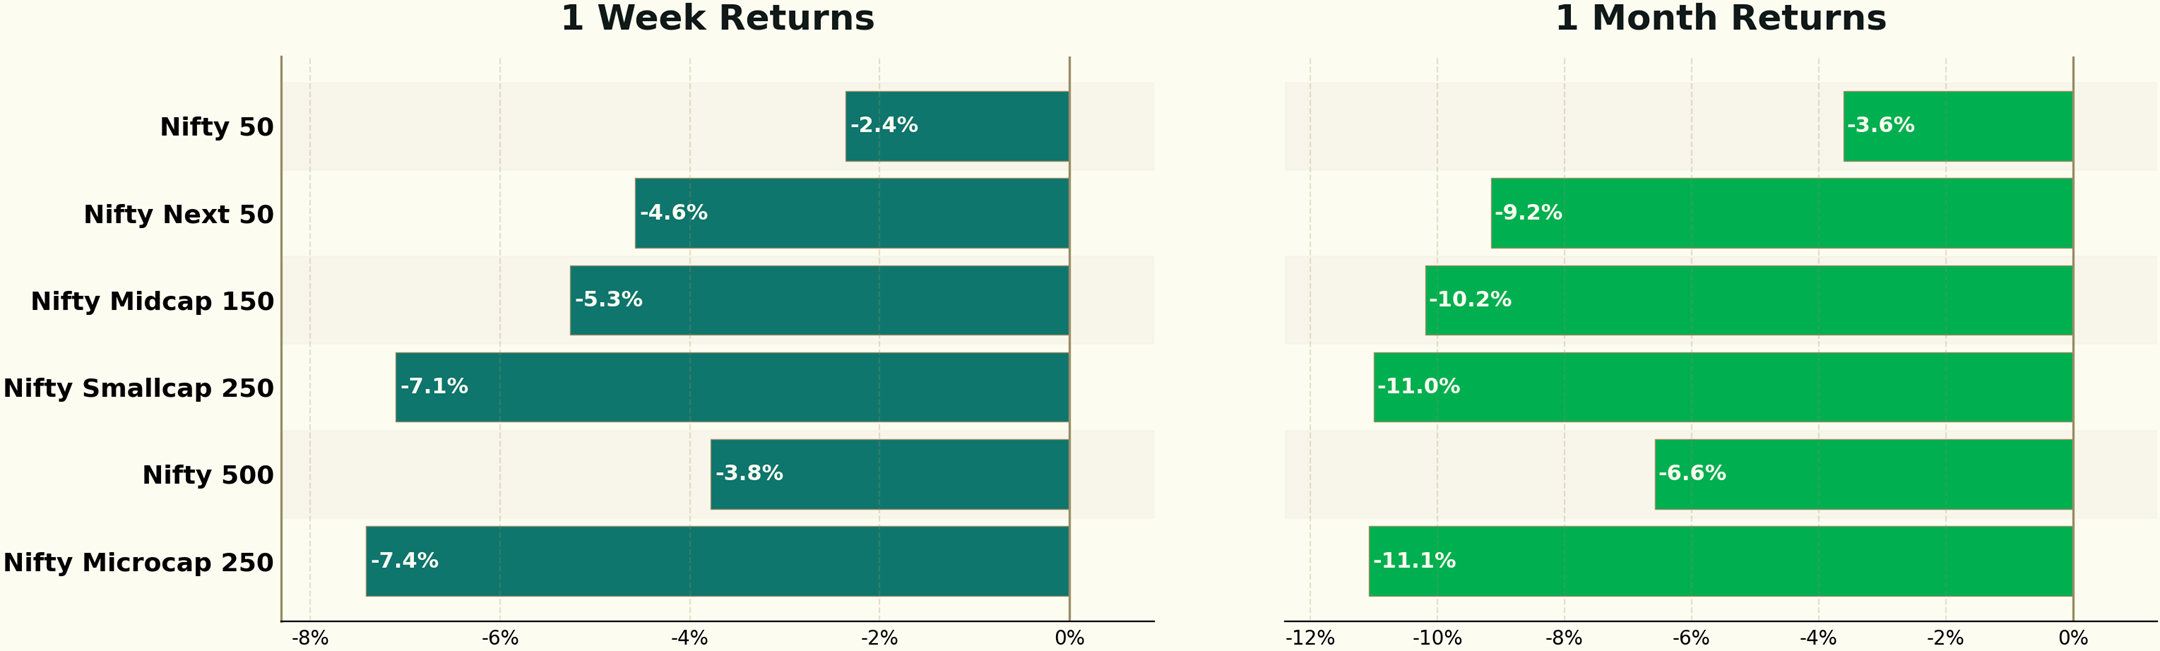
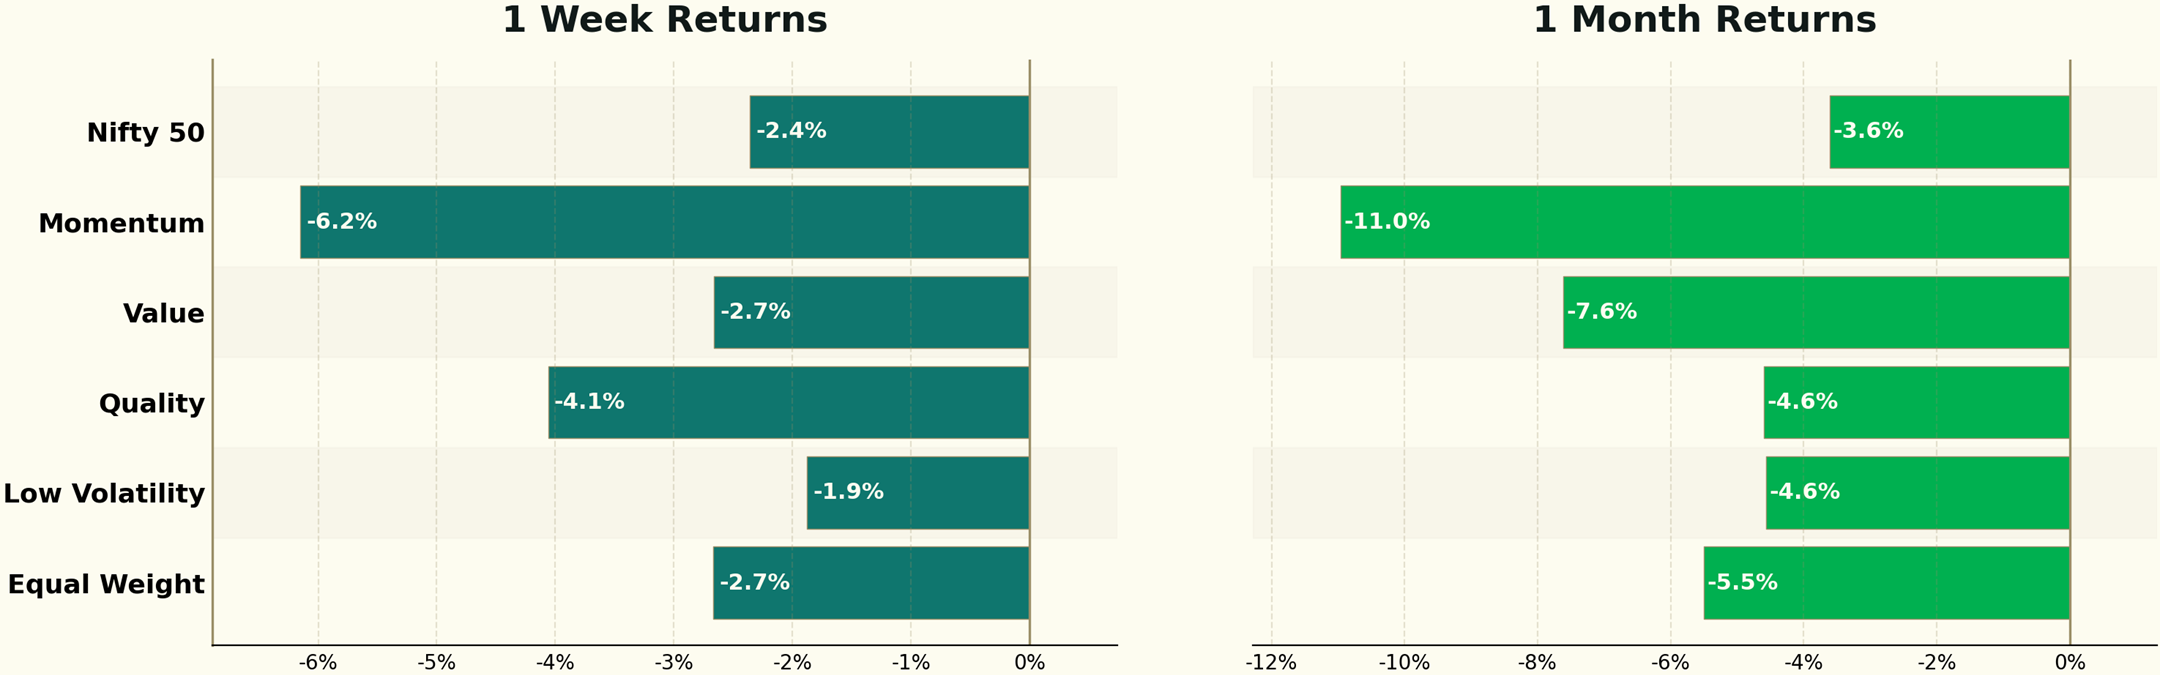
- Broad market sells off this week – microcaps, smallcaps hit hardest; In Factors – Momentum lags sharply, Low Volatility holds up best
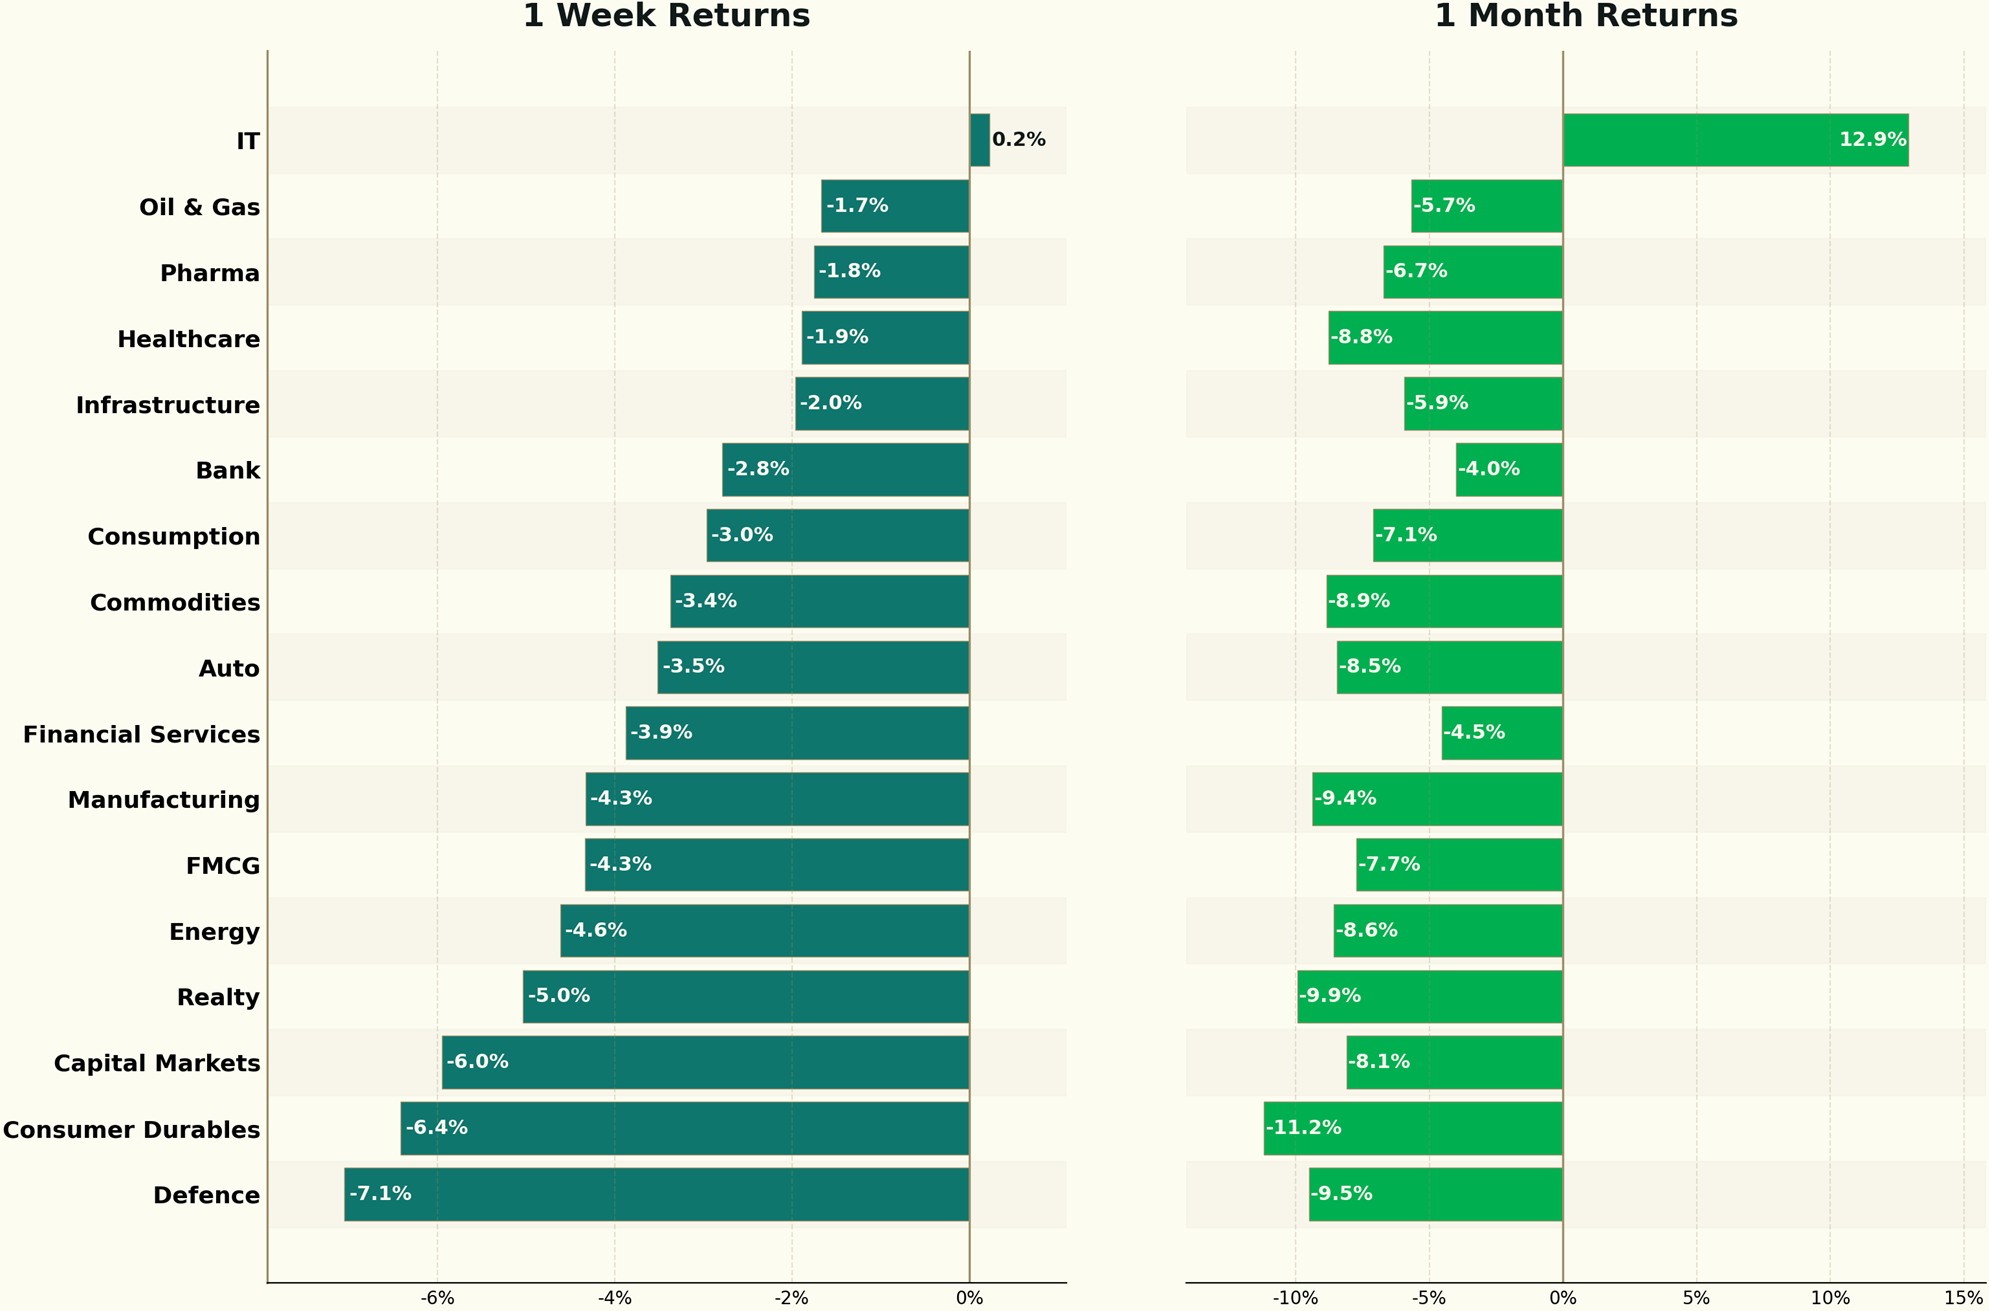
- IT only sector in green this week; Defence, Durables lag sharply
- Sector Rotation: Bank, IT, Oil & Gas lead; Financial Services weakens
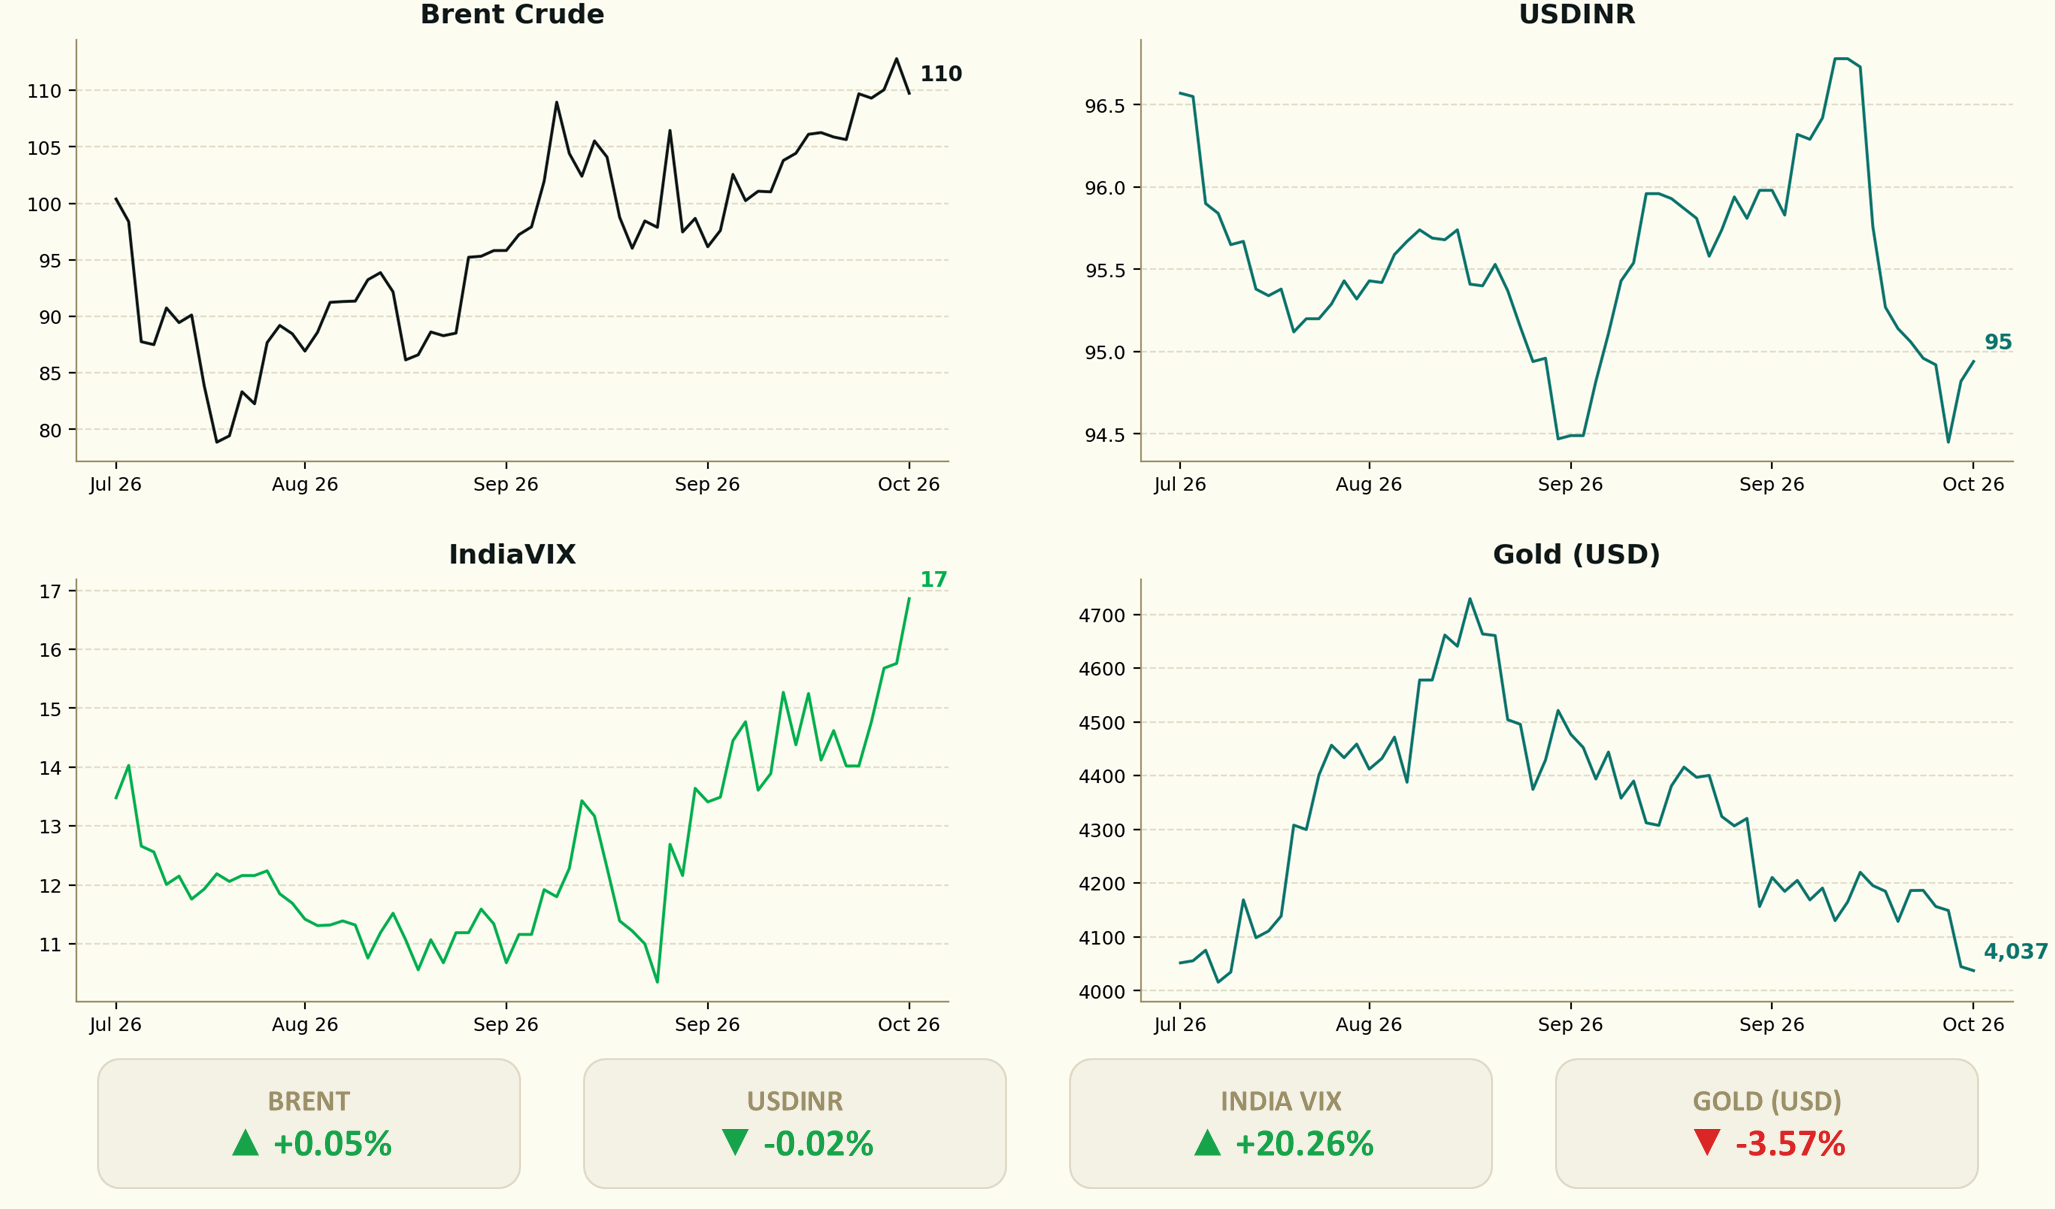
- Macro: India VIX spikes 20.3%; Gold slides 3.6%, Brent flat
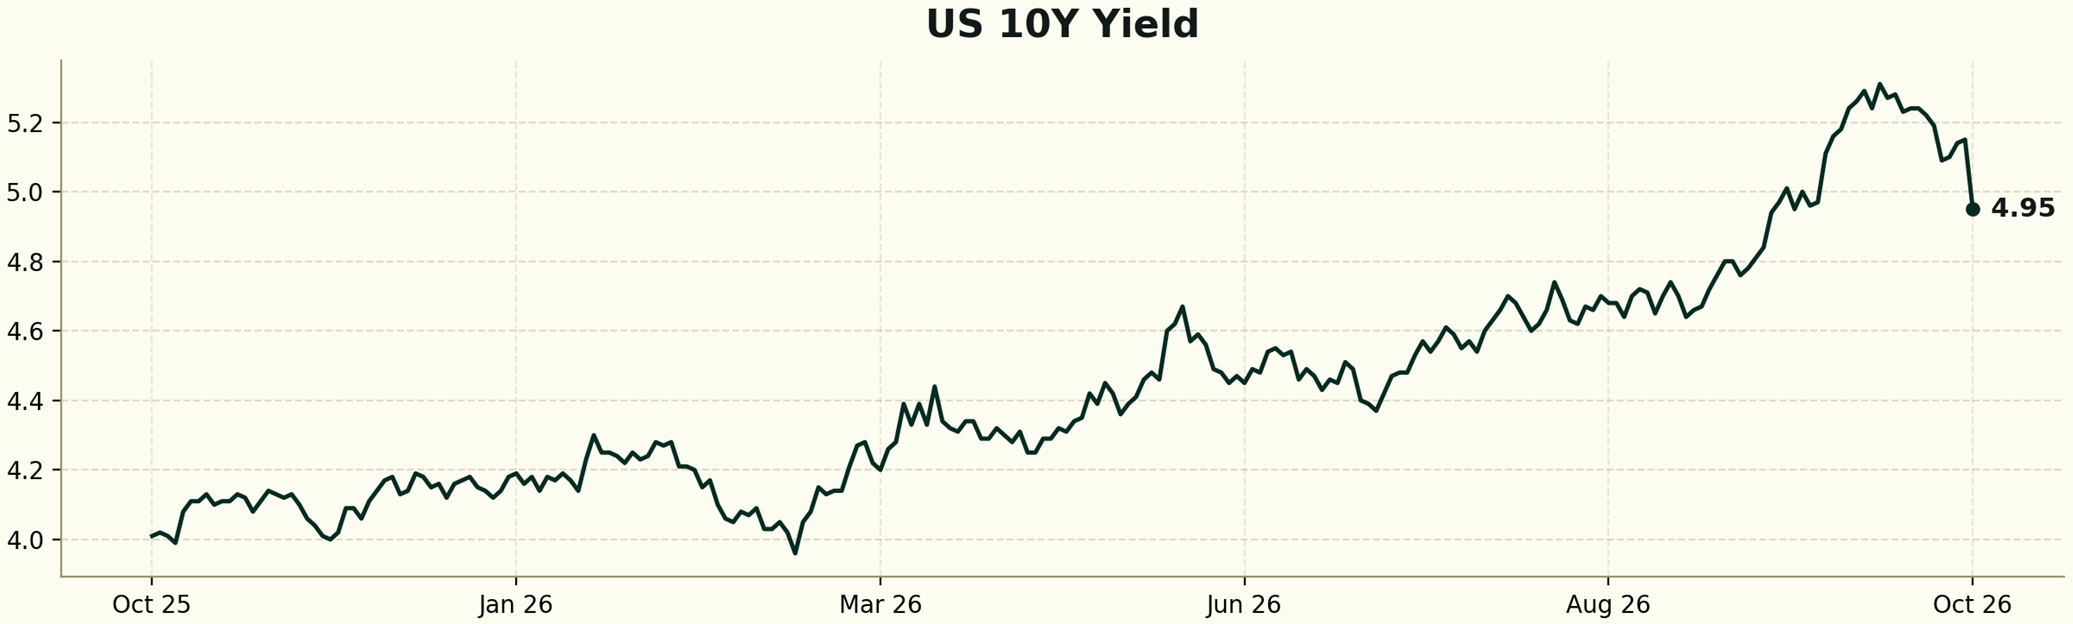
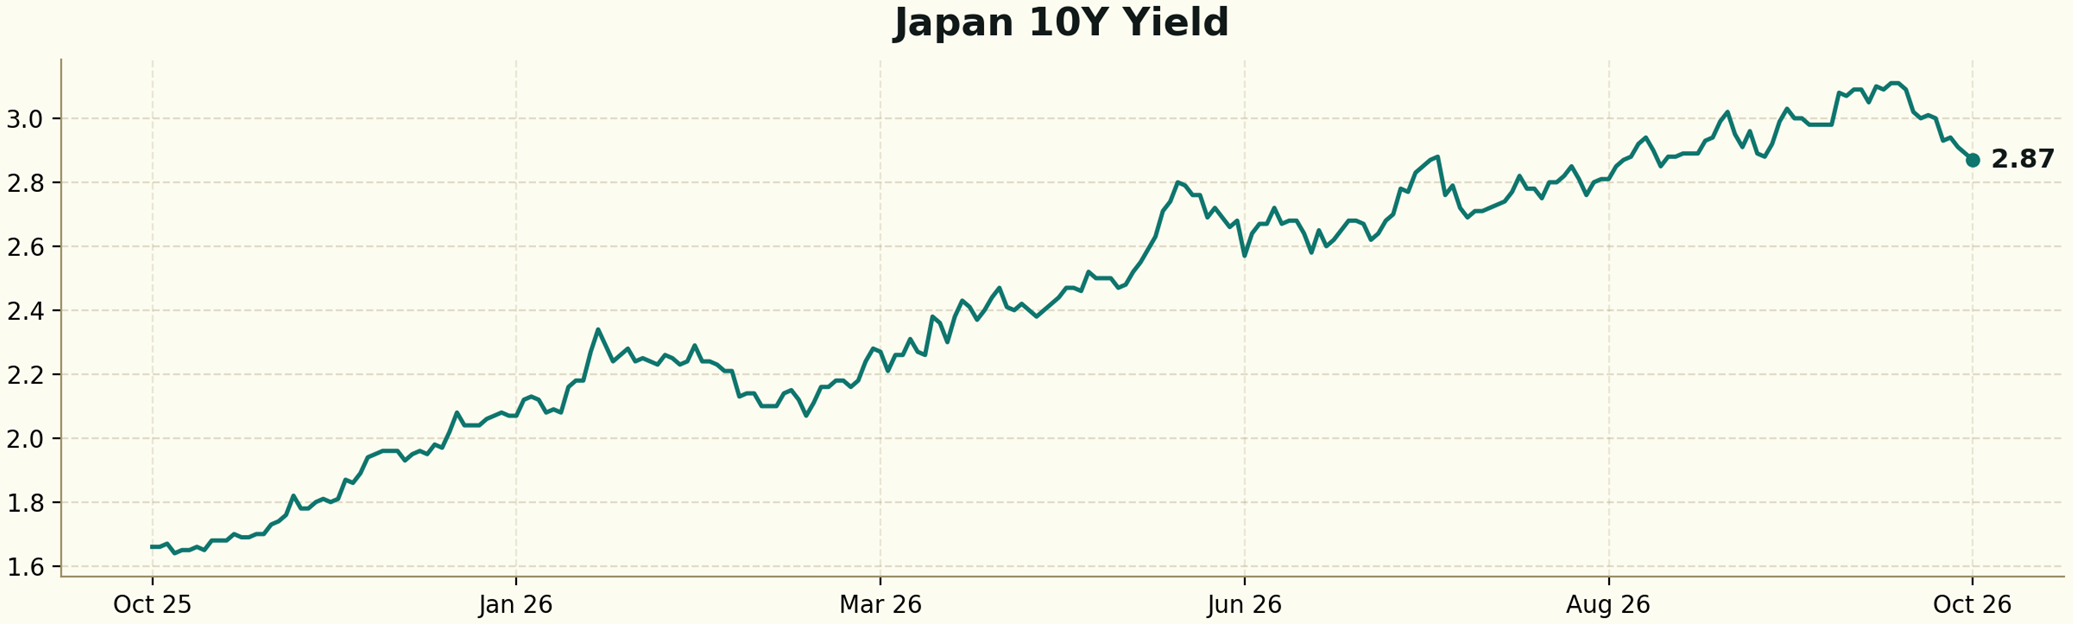
- Global 10Y Yields: US falls to 4.95%, Japan eases to 2.87%
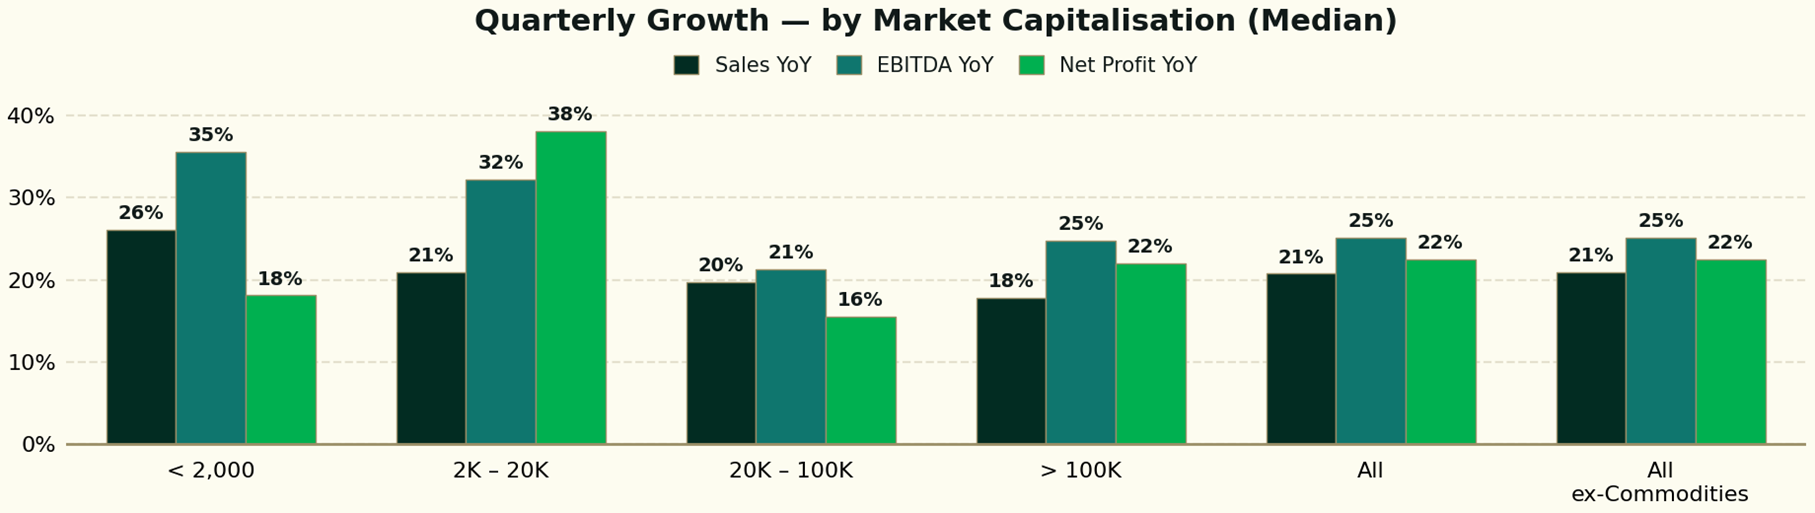
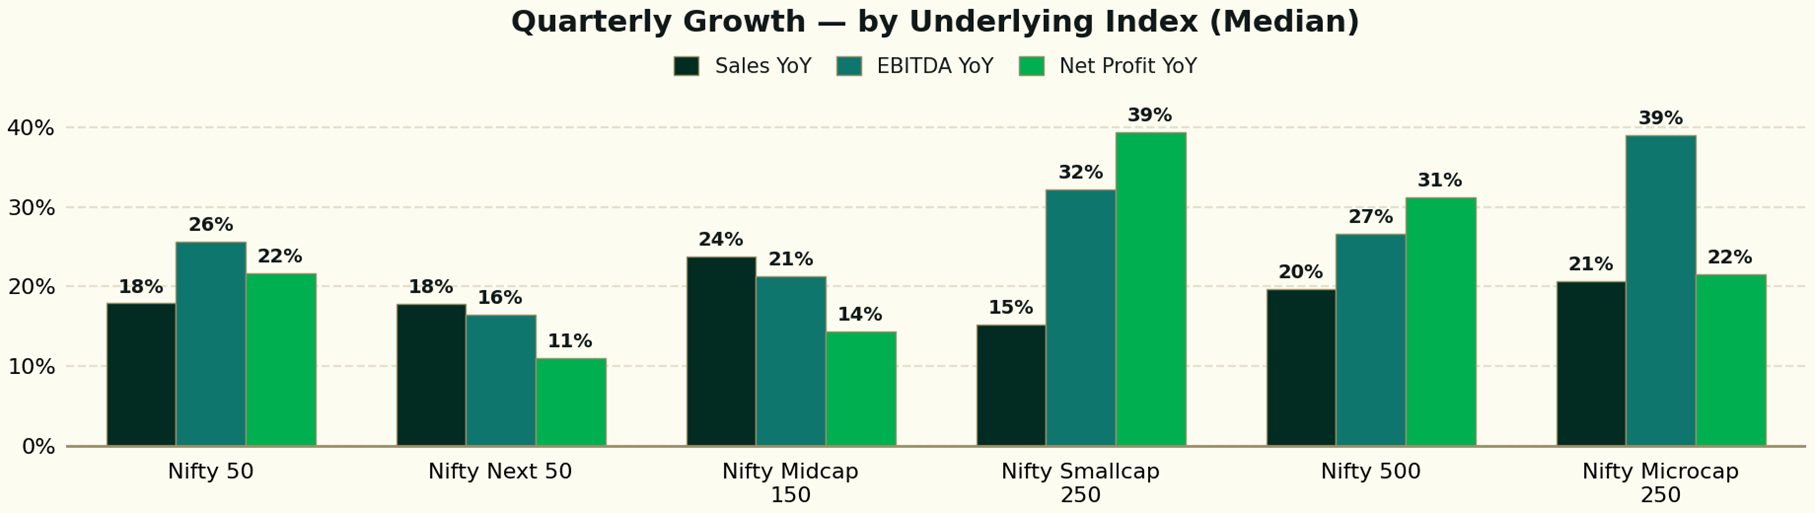
- Median profit up 22% YoY; Smallcap 250 leads at 39%
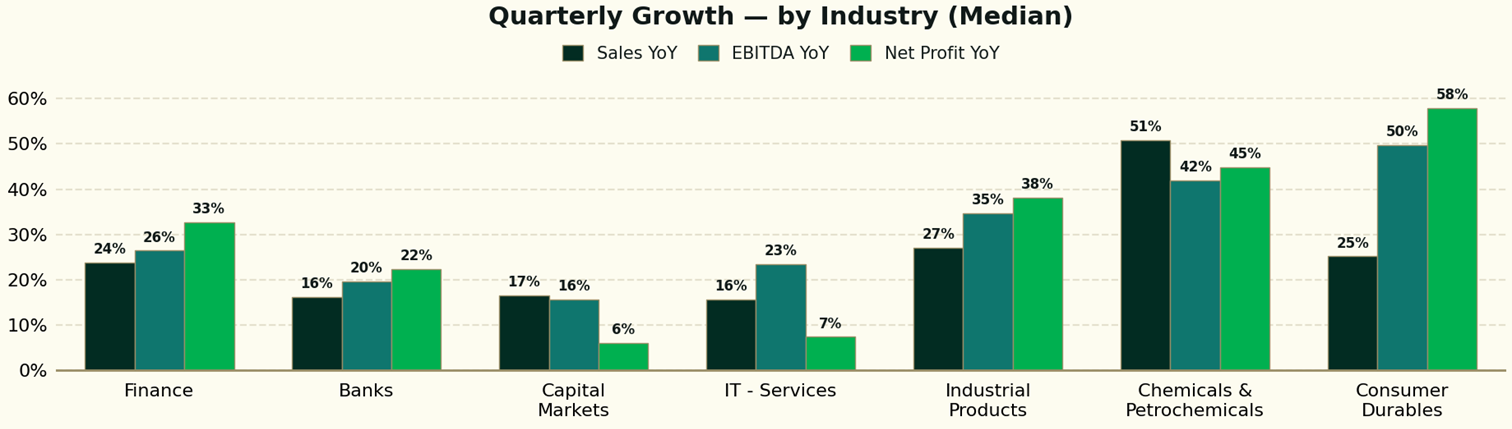
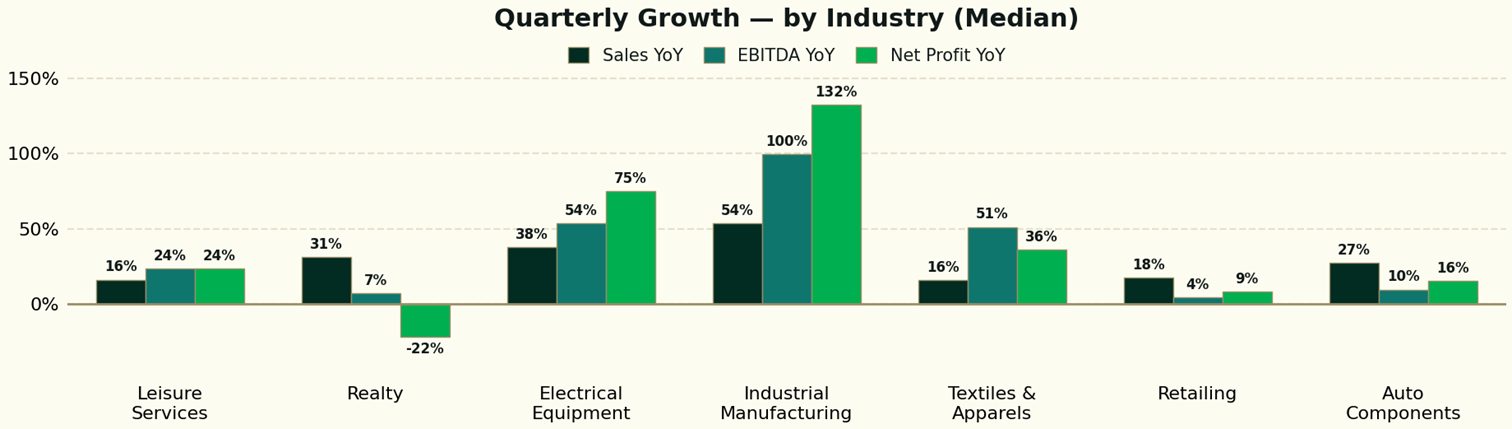
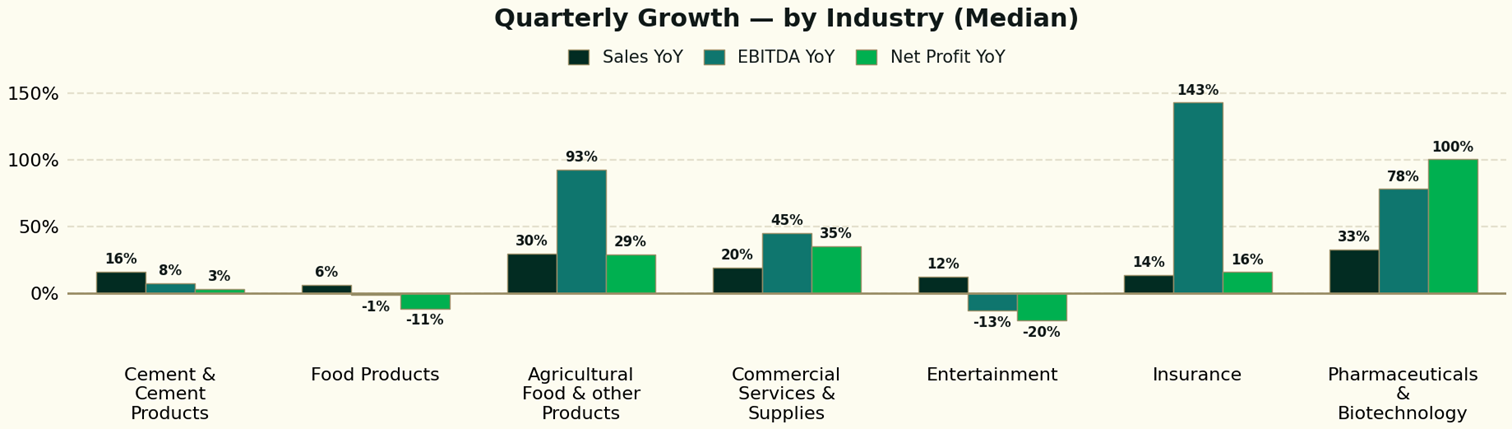
- Industry growth: Industrial Mfg, Pharma profits surge; Realty falls
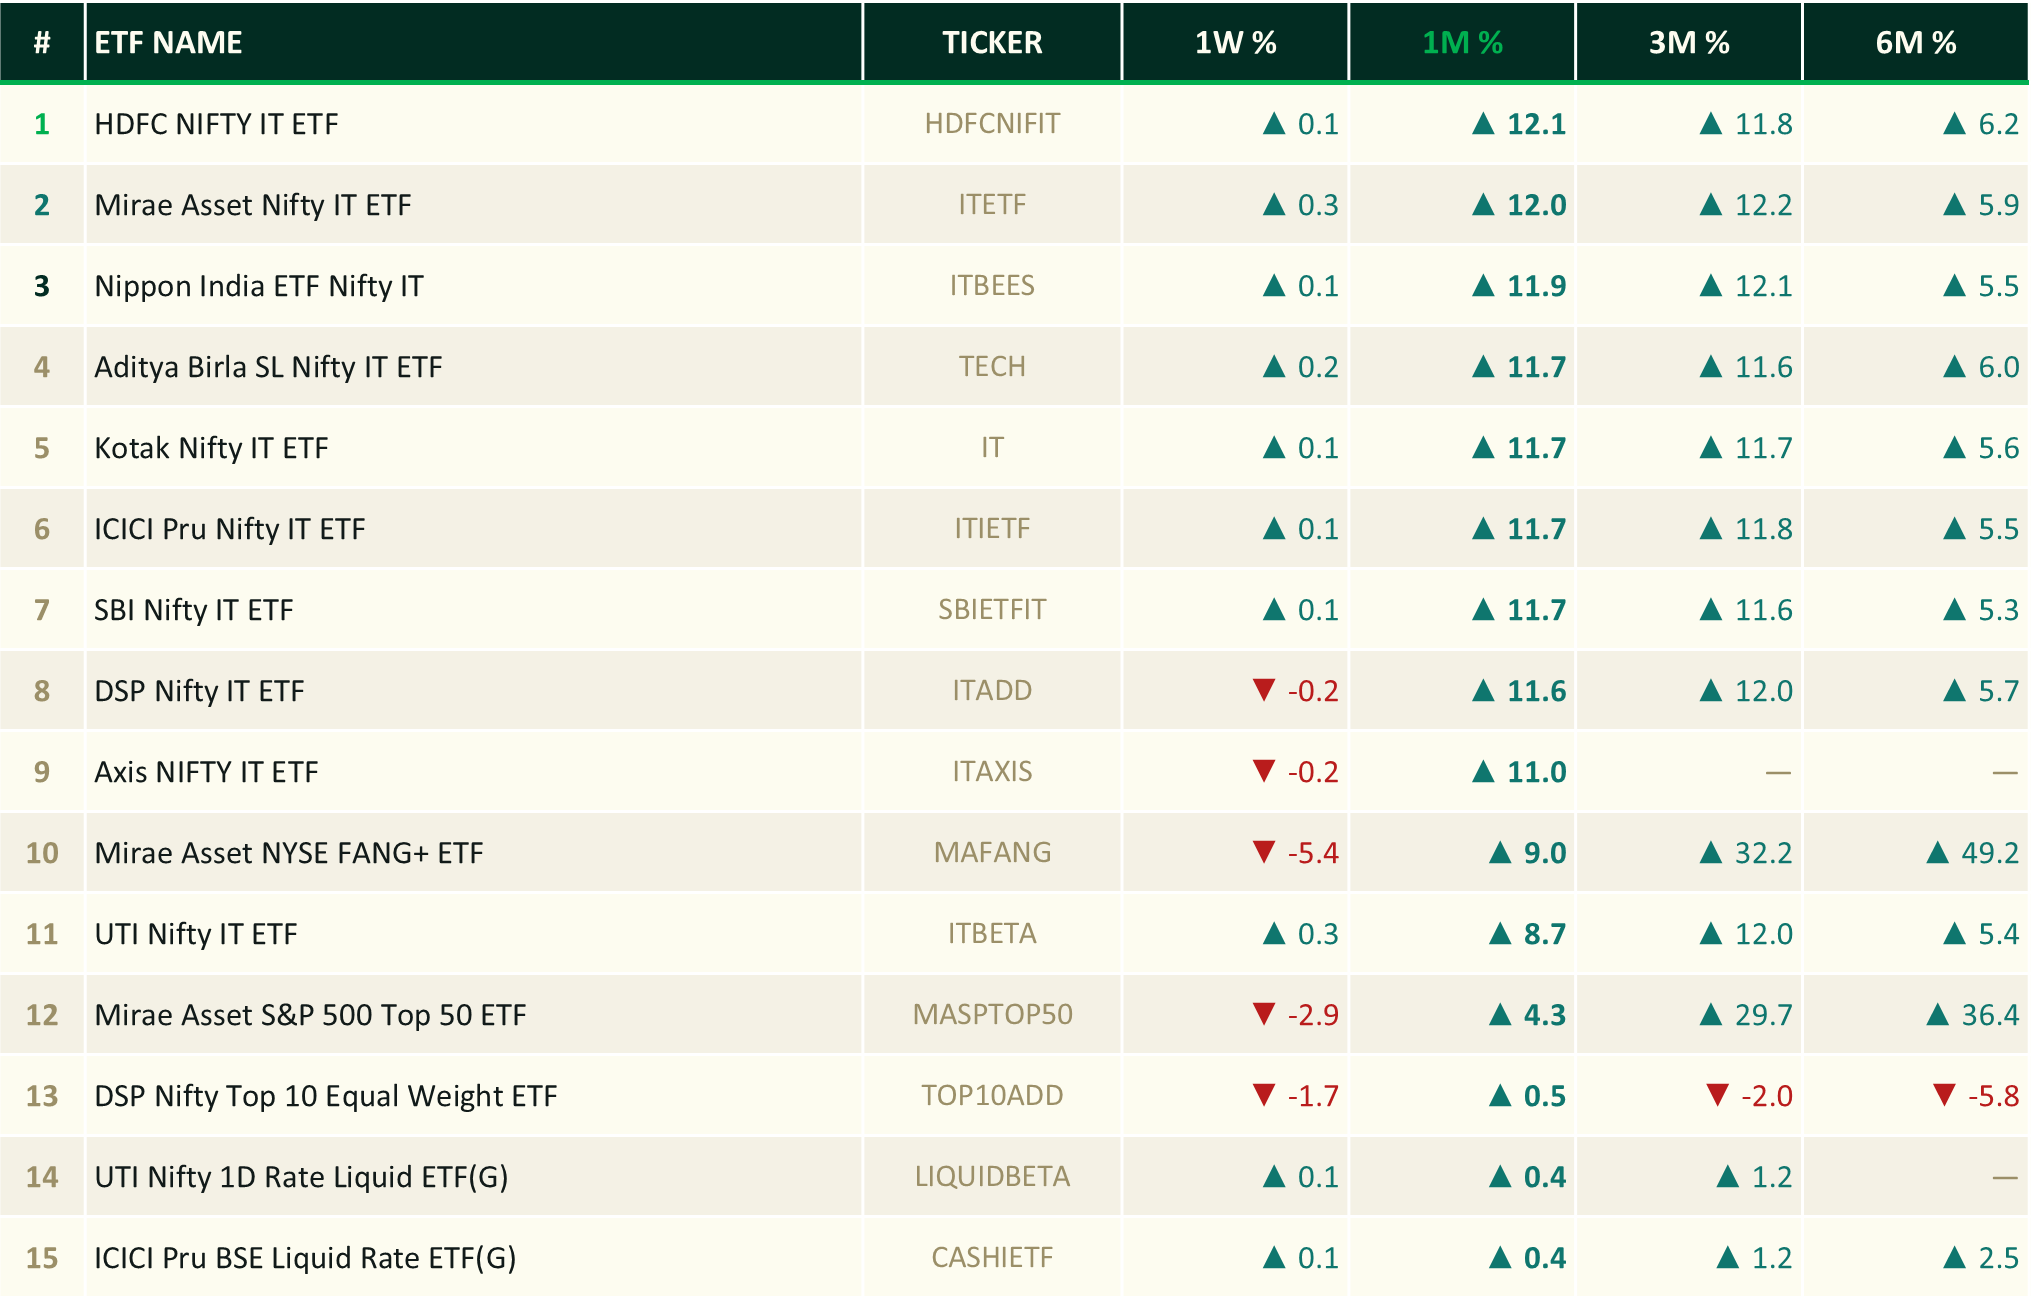
- Top 15 Performing ETFs
Nifty falls 2.36% WoW as India VIX spikes 20%
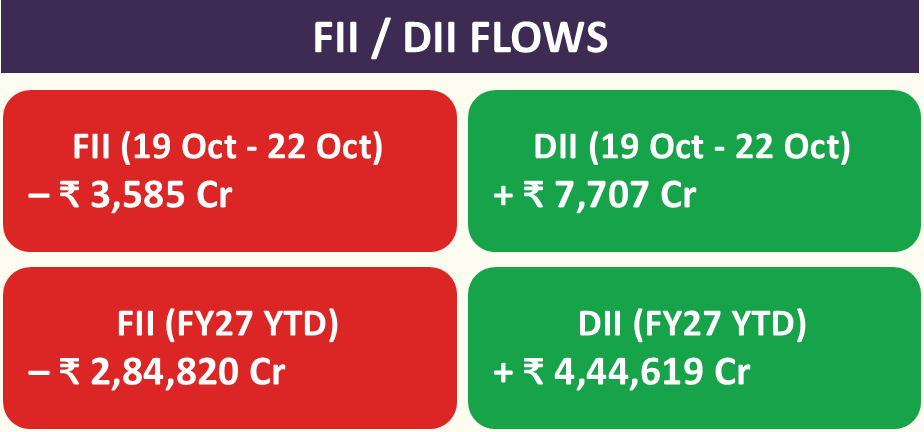
Week’s Recap
Markets Under Pressure: Nifty fell nearly 2% this week on high crude, persistent FII selling and global uncertainty, extending the correction.
Crude Oil Surges: Brent neared $114 per barrel on Middle East tensions, raising risks to inflation, the import bill and corporate margins.
Rupee Weakens: The rupee slipped to around ₹94.96 per dollar on Friday as rising crude offset support from a softer dollar.
Broader Markets Underperform: Midcaps and smallcaps saw heavier selling than the headline indices, reflecting weaker risk appetite.
Strong Q2 Results: ICICI Bank beat estimates on high loan growth and low provisions, Hindustan Zinc gained from firm metal prices, and Central Bank of India’s profit rose 21% to ₹1,469 crore.
IT Stocks Show Resilience: IT shares outperformed on earnings and AI-consulting optimism, though global tech volatility remains a risk.
Earnings Drive Stock-Specific Action: Q2 FY27 results kept steering individual stocks, with focus on revenue growth, margins and guidance.
Jio Platforms IPO: The IPO was subscribed 12.55 times by 23 October, showing strong investor demand.
Next Week Ahead
US Fed Meeting: FOMC meets 27-28 October, decision Wednesday; could move equities, dollar and FII flows.
Crude Oil Risk: Brent near $114 is the biggest risk; easing Middle East tensions could help.
Q2 Earnings Intensify: Bajaj Auto, L&T, Maruti, Tata Steel, HUL and Asian Paints report.
Auto and Festive Demand: Bajaj Auto and Maruti results will show demand, margins and energy-cost impact.
FMCG and Consumer: HUL and Tata Consumer results will show demand, input costs and pricing power.
Jio Platforms IPO Listing (28 October): Lists on NSE and BSE after 12.55x subscription.
Nifty Levels: Support at 22,400 and 22,200, resistance at 22,800 and 23,000.
Broad market sells off this week – microcaps, smallcaps hit hardest; In Factors – Momentum lags sharply, Low Volatility holds up best
IT only sector in green this week; Defence, Durables lag sharply
Sector Rotation: Bank, IT, Oil & Gas lead; Financial Services weakens
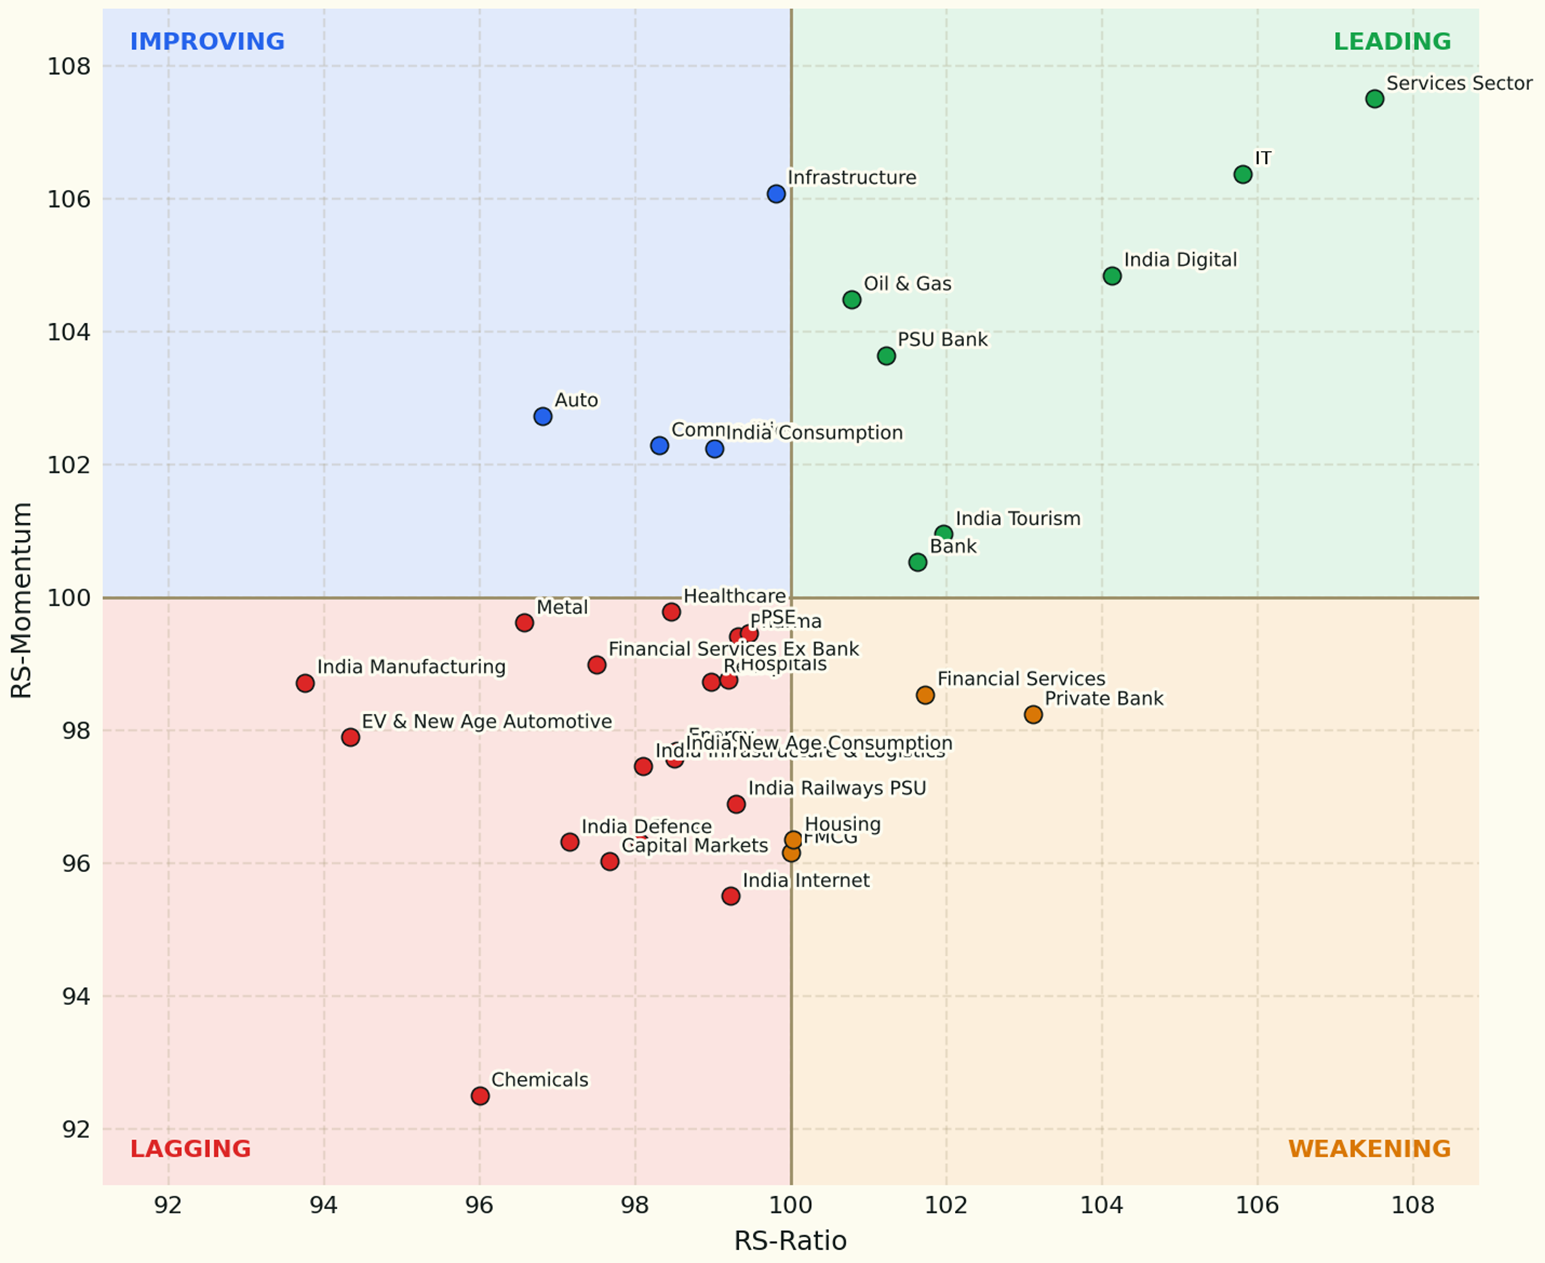
Leading
Nifty Bank
Nifty IT
Nifty India Digital
Nifty India Tourism
Nifty Oil & Gas
Nifty PSU Bank
Nifty Services Sector
Weakening
BSE Housing
Nifty FMCG
Nifty Financial Services
Nifty Private Bank
Lagging
BSE Hospitals
BSE Power
Nifty Capital Markets
Nifty Chemicals
Nifty EV & New Age Automotive
Nifty Energy
Nifty Financial Services Ex Bank
Nifty Healthcare
Nifty India Defence
Nifty India Infrastructure & Logistics
Nifty India Internet
Nifty India Manufacturing
Nifty India New Age Consumption
Nifty India Railways PSU
Nifty Metal
Nifty PSE
Nifty Pharma
Nifty Realty
Improving
Nifty Auto
Nifty Commodities
Nifty India Consumption
Nifty Infrastructure
Macro: India VIX spikes 20.3%; Gold slides 3.6%, Brent flat
Global 10Y Yields: US falls to 4.95%, Japan eases to 2.87%
Median profit up 22% YoY; Smallcap 250 leads at 39%
Industry growth: Industrial Mfg, Pharma profits surge; Realty falls
Top 15 Performing ETFs