Insights
Weekly Market Map - 31 October, 2026
Weekly Market Map
In this article
- Nifty reclaims 23,000, gains 2.00% WoW as India VIX cools 9%
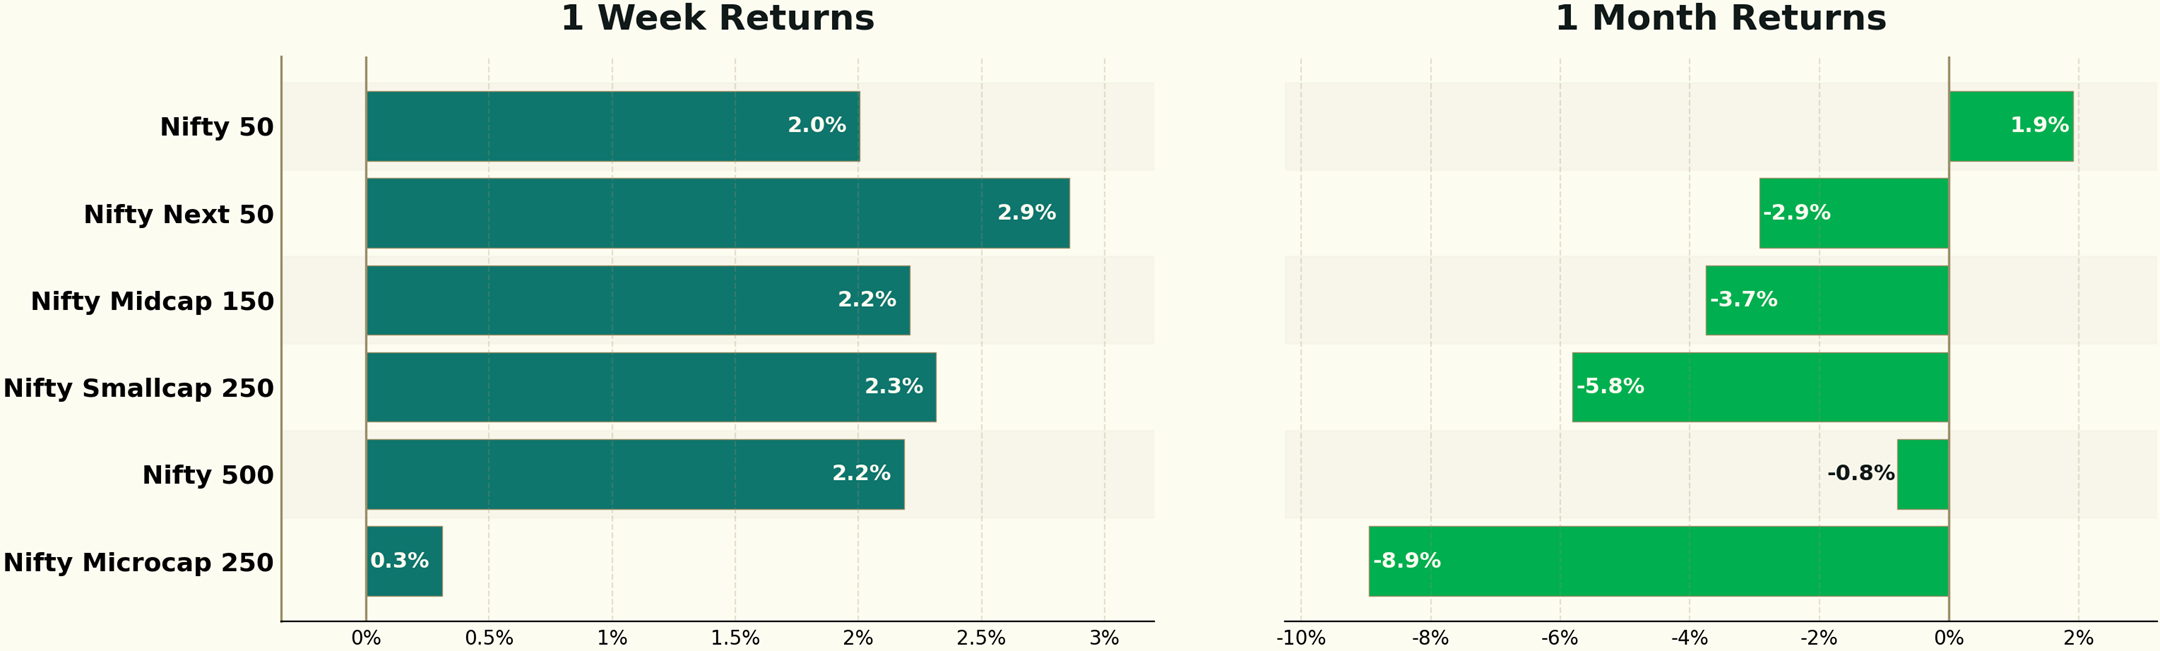
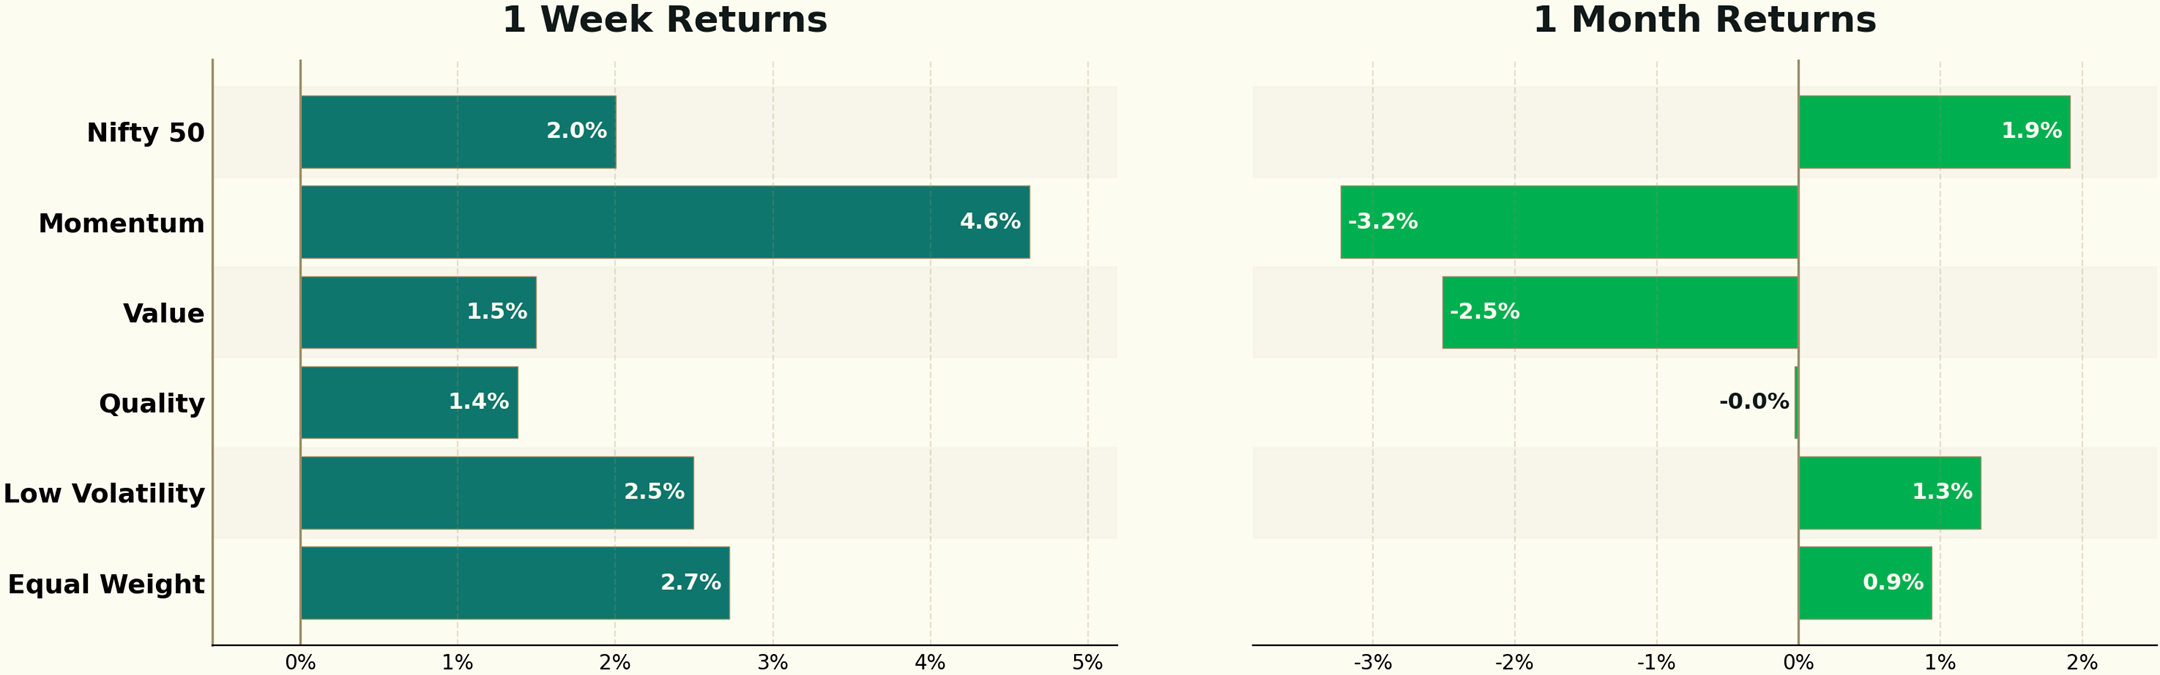
- Broad market rallies this week – Next 50 leads, microcaps lag; In Factors – Momentum surges, Quality lags
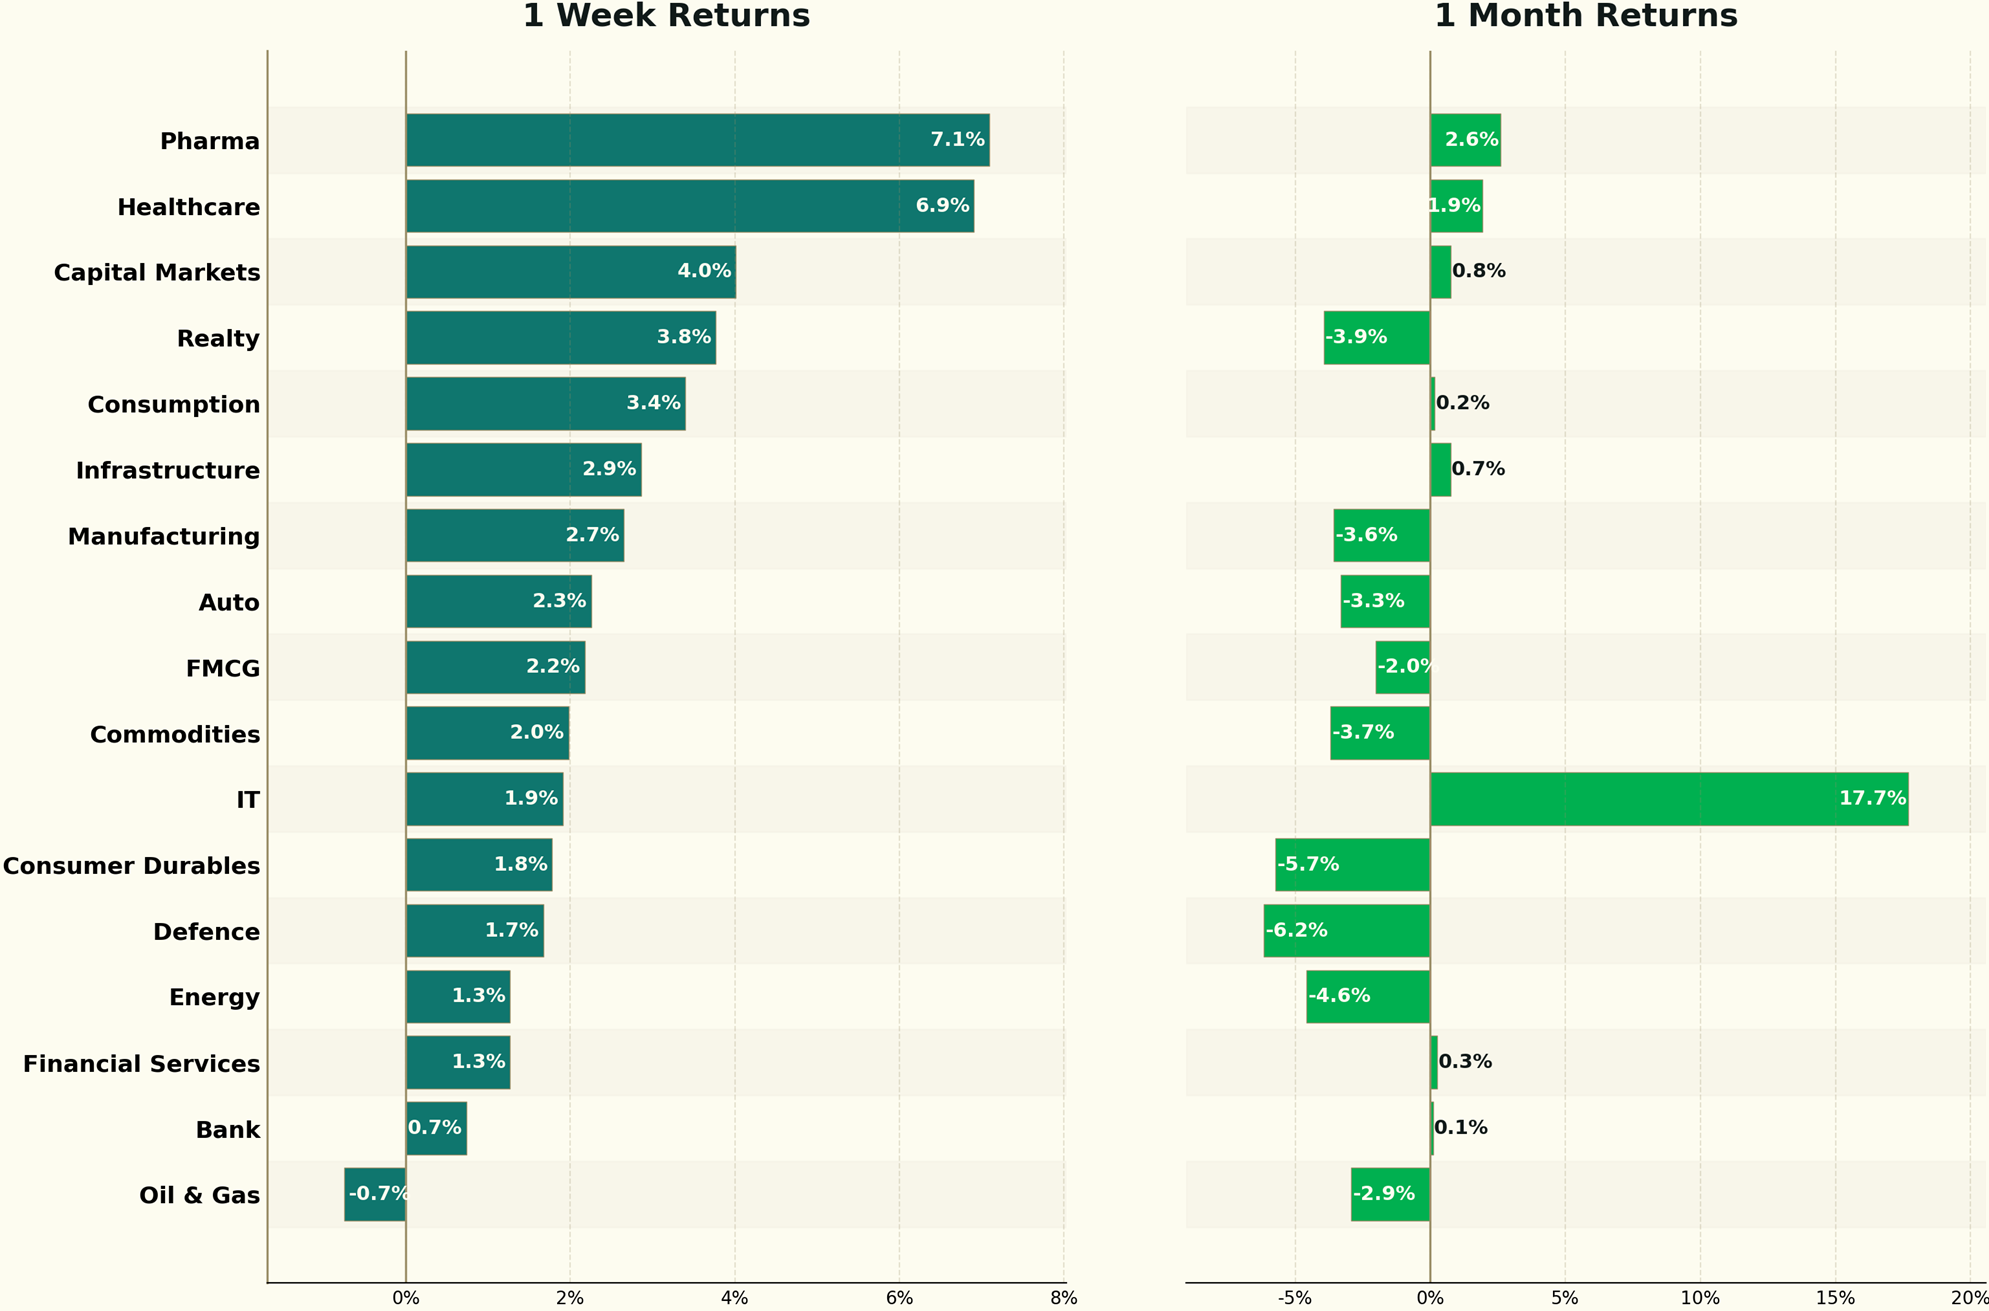
- Pharma, Healthcare surge this week; Oil & Gas only sector in red
- Sector Rotation: Healthcare, Pharma lead; IT weakens
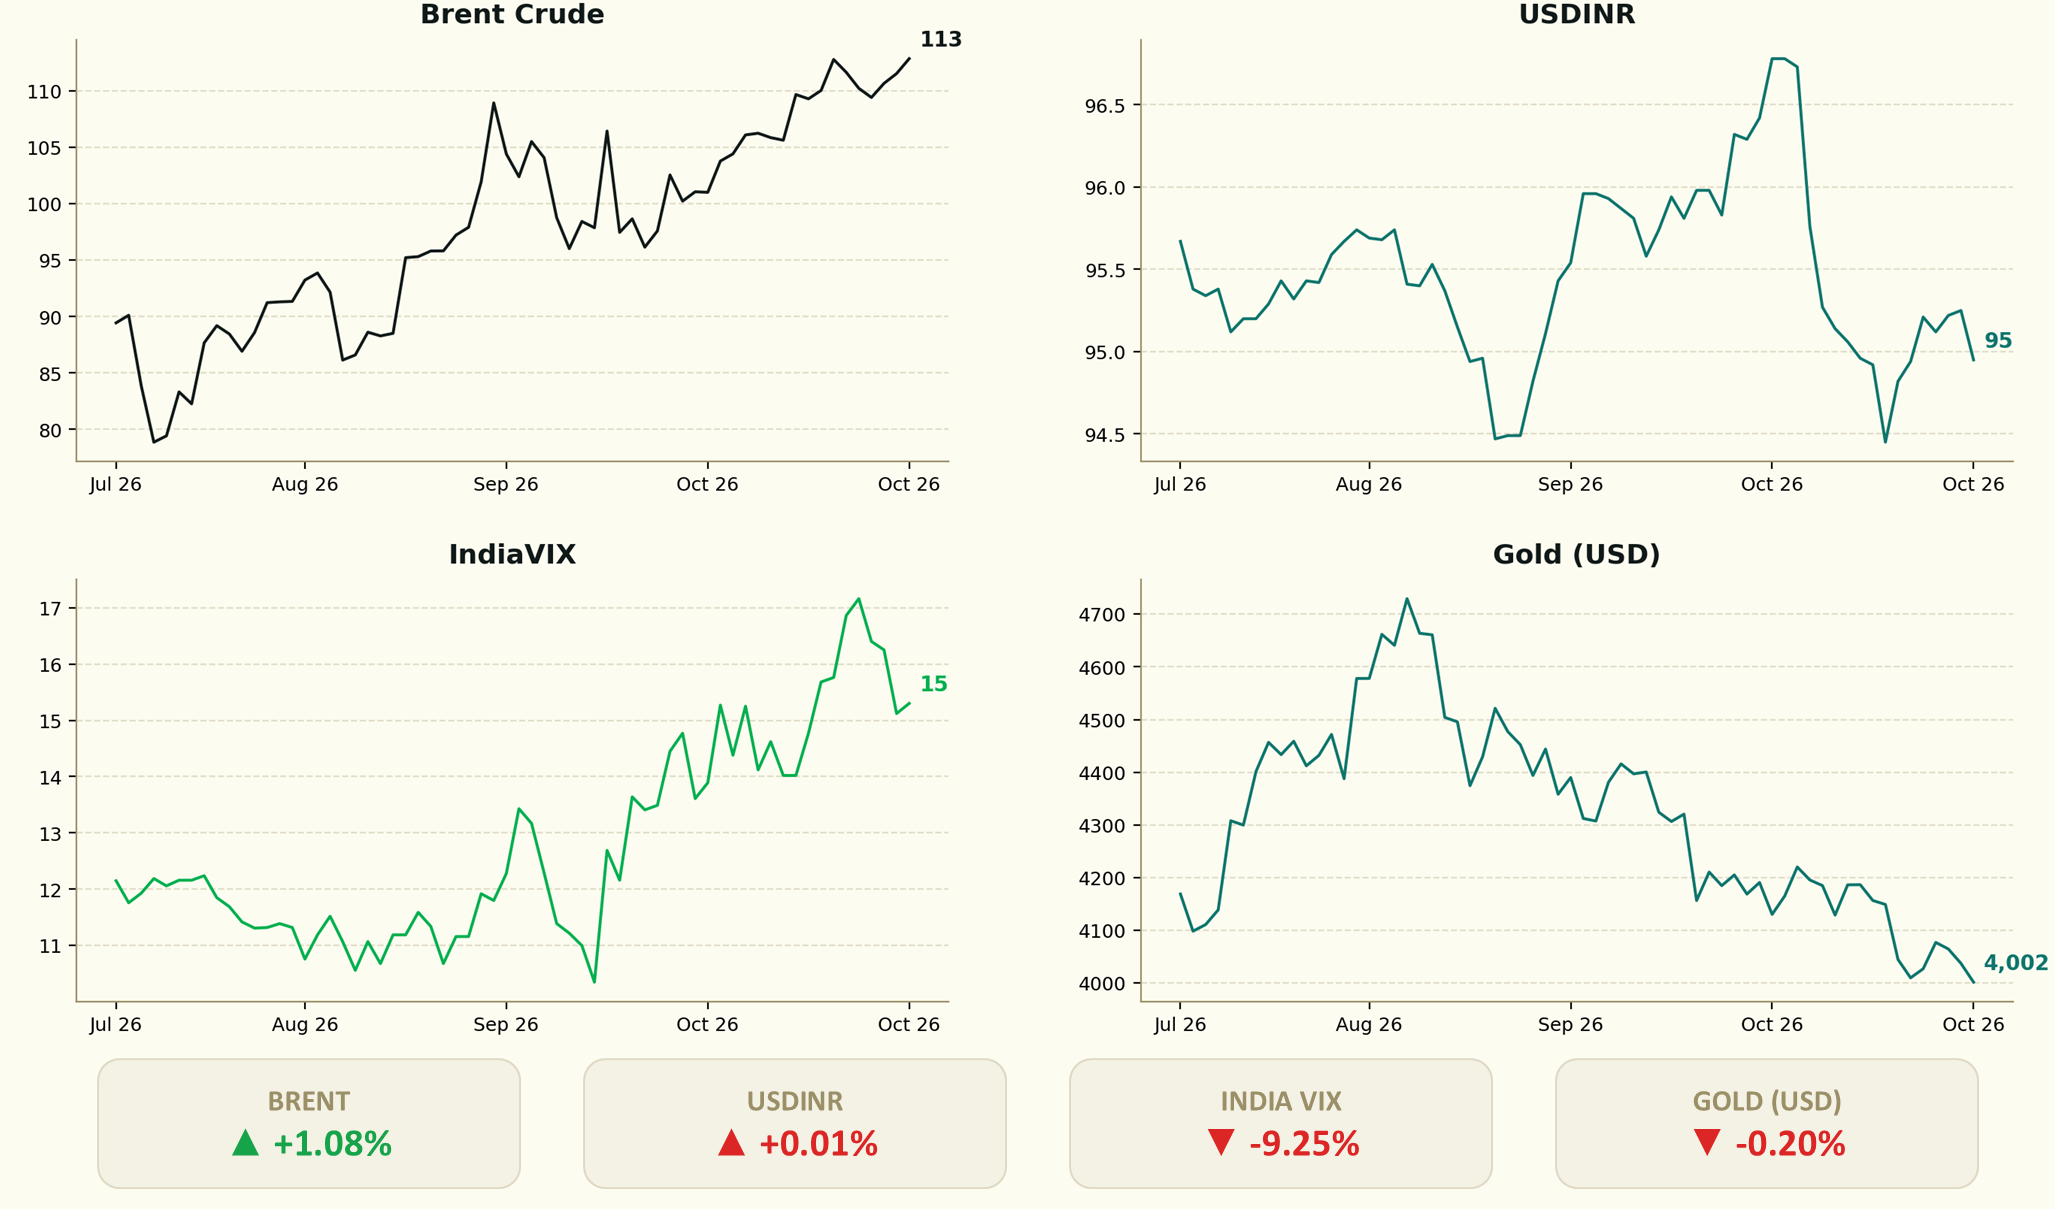
- Macro: India VIX cools 9.3%; Brent up 1.1%, Rupee steady
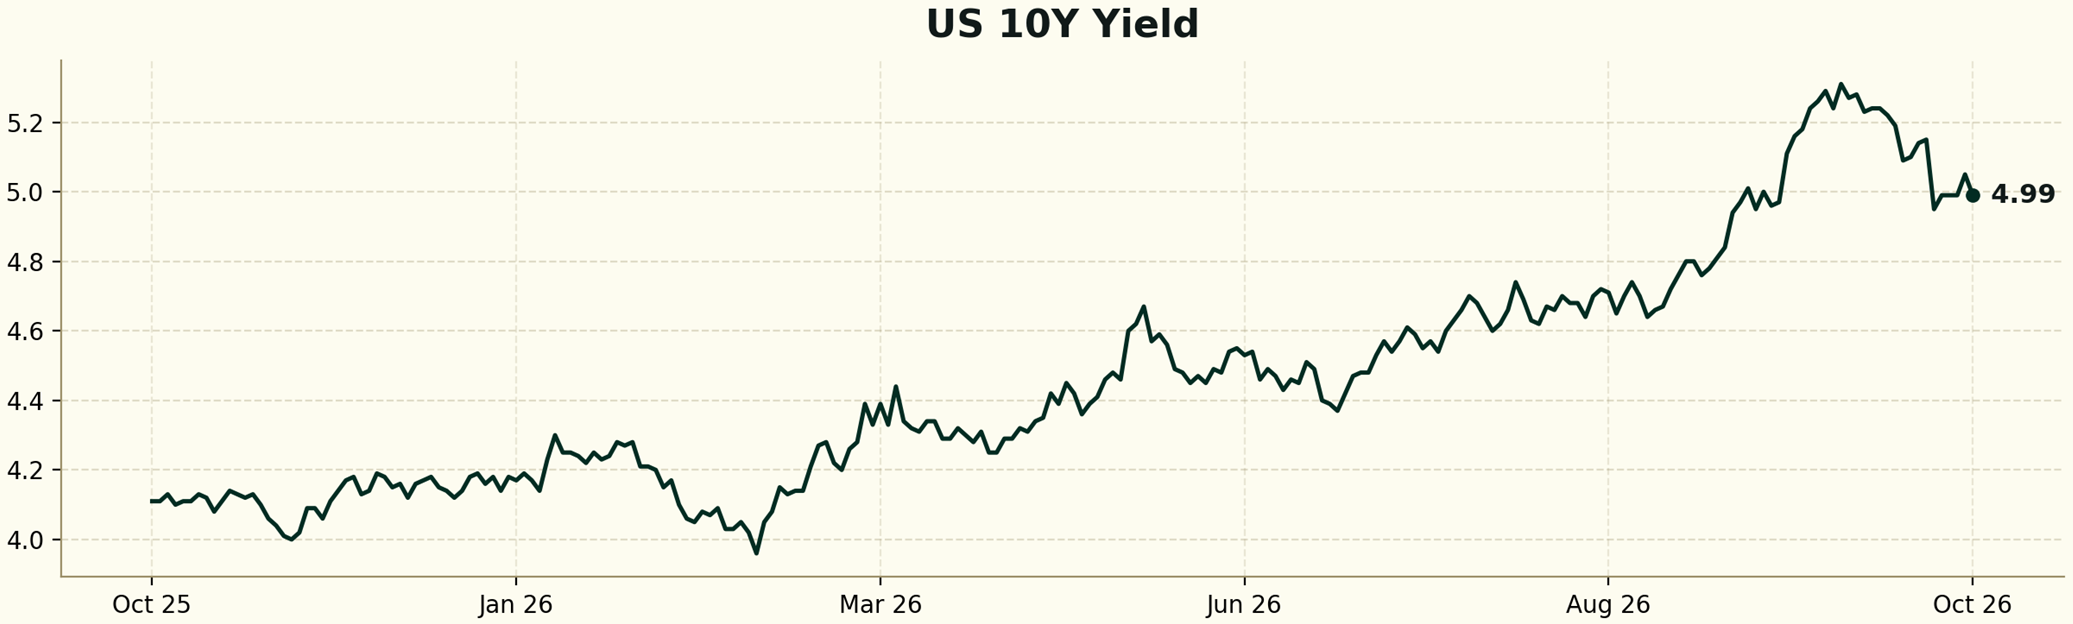
- Global 10Y Yields: US ticks up to 4.99%; Japan eases to 2.83%
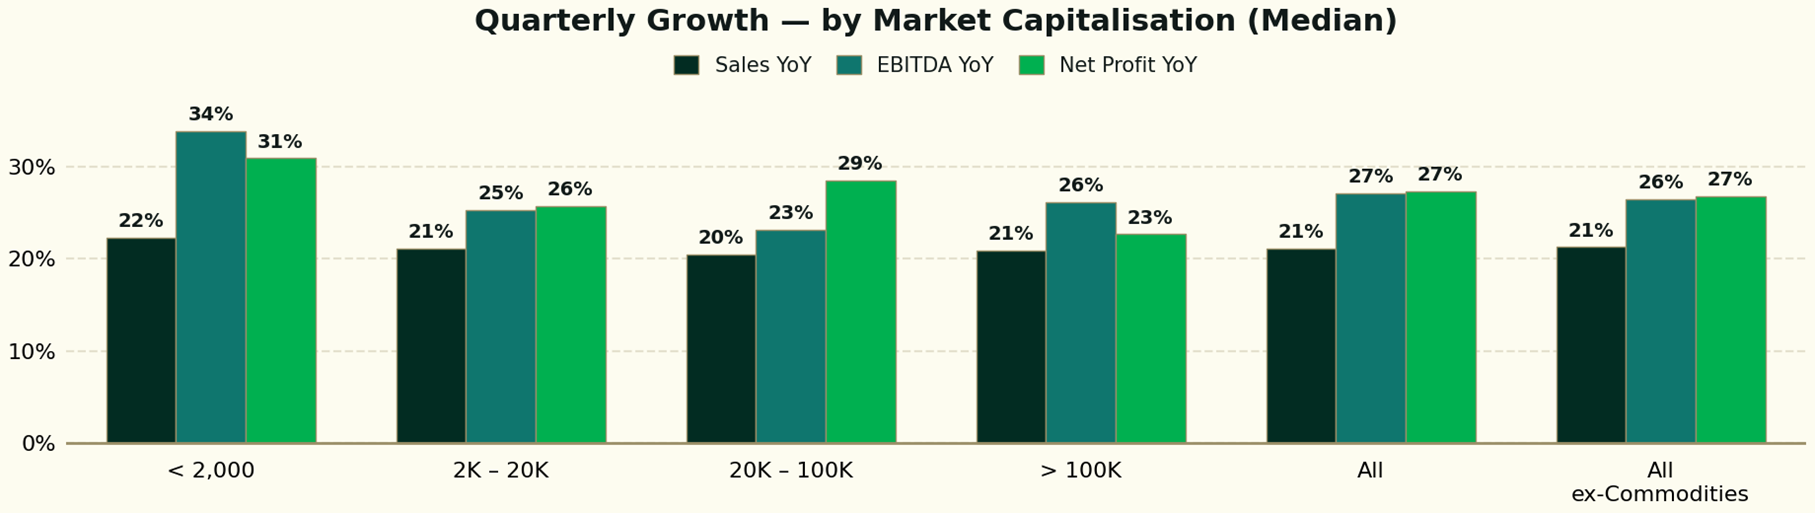
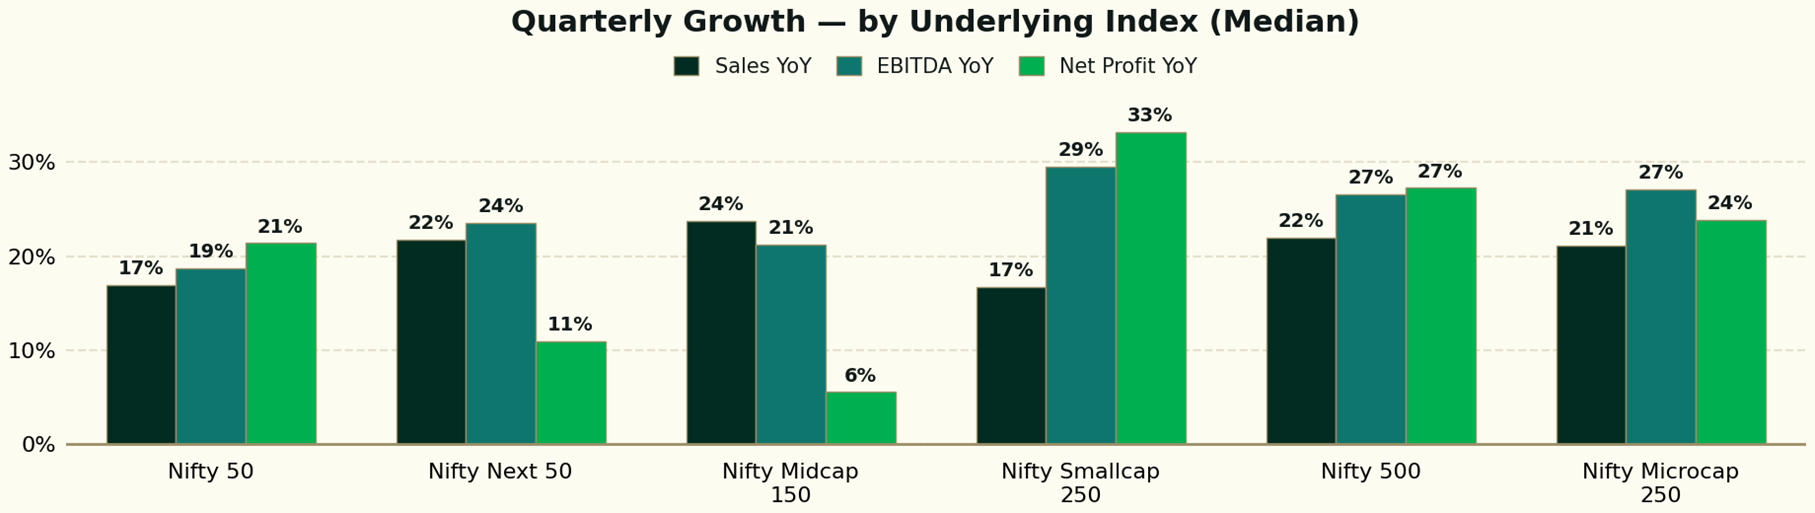
- Median profit up 27% YoY; Smallcap 250 leads at 33%
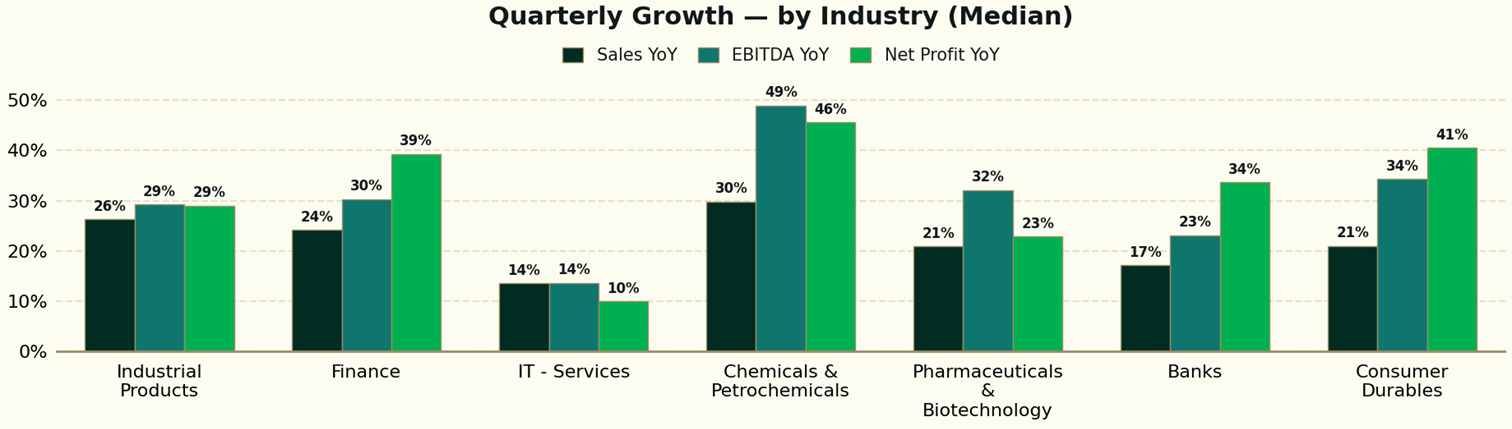
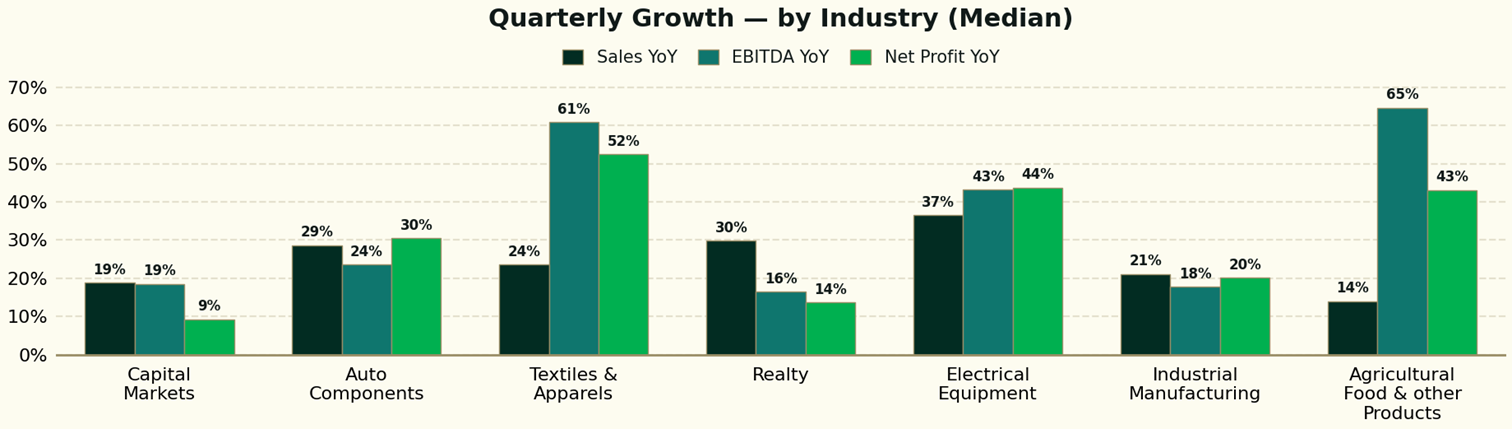
- Industry growth: Textiles, Chemicals, Electricals lead; Cement dips
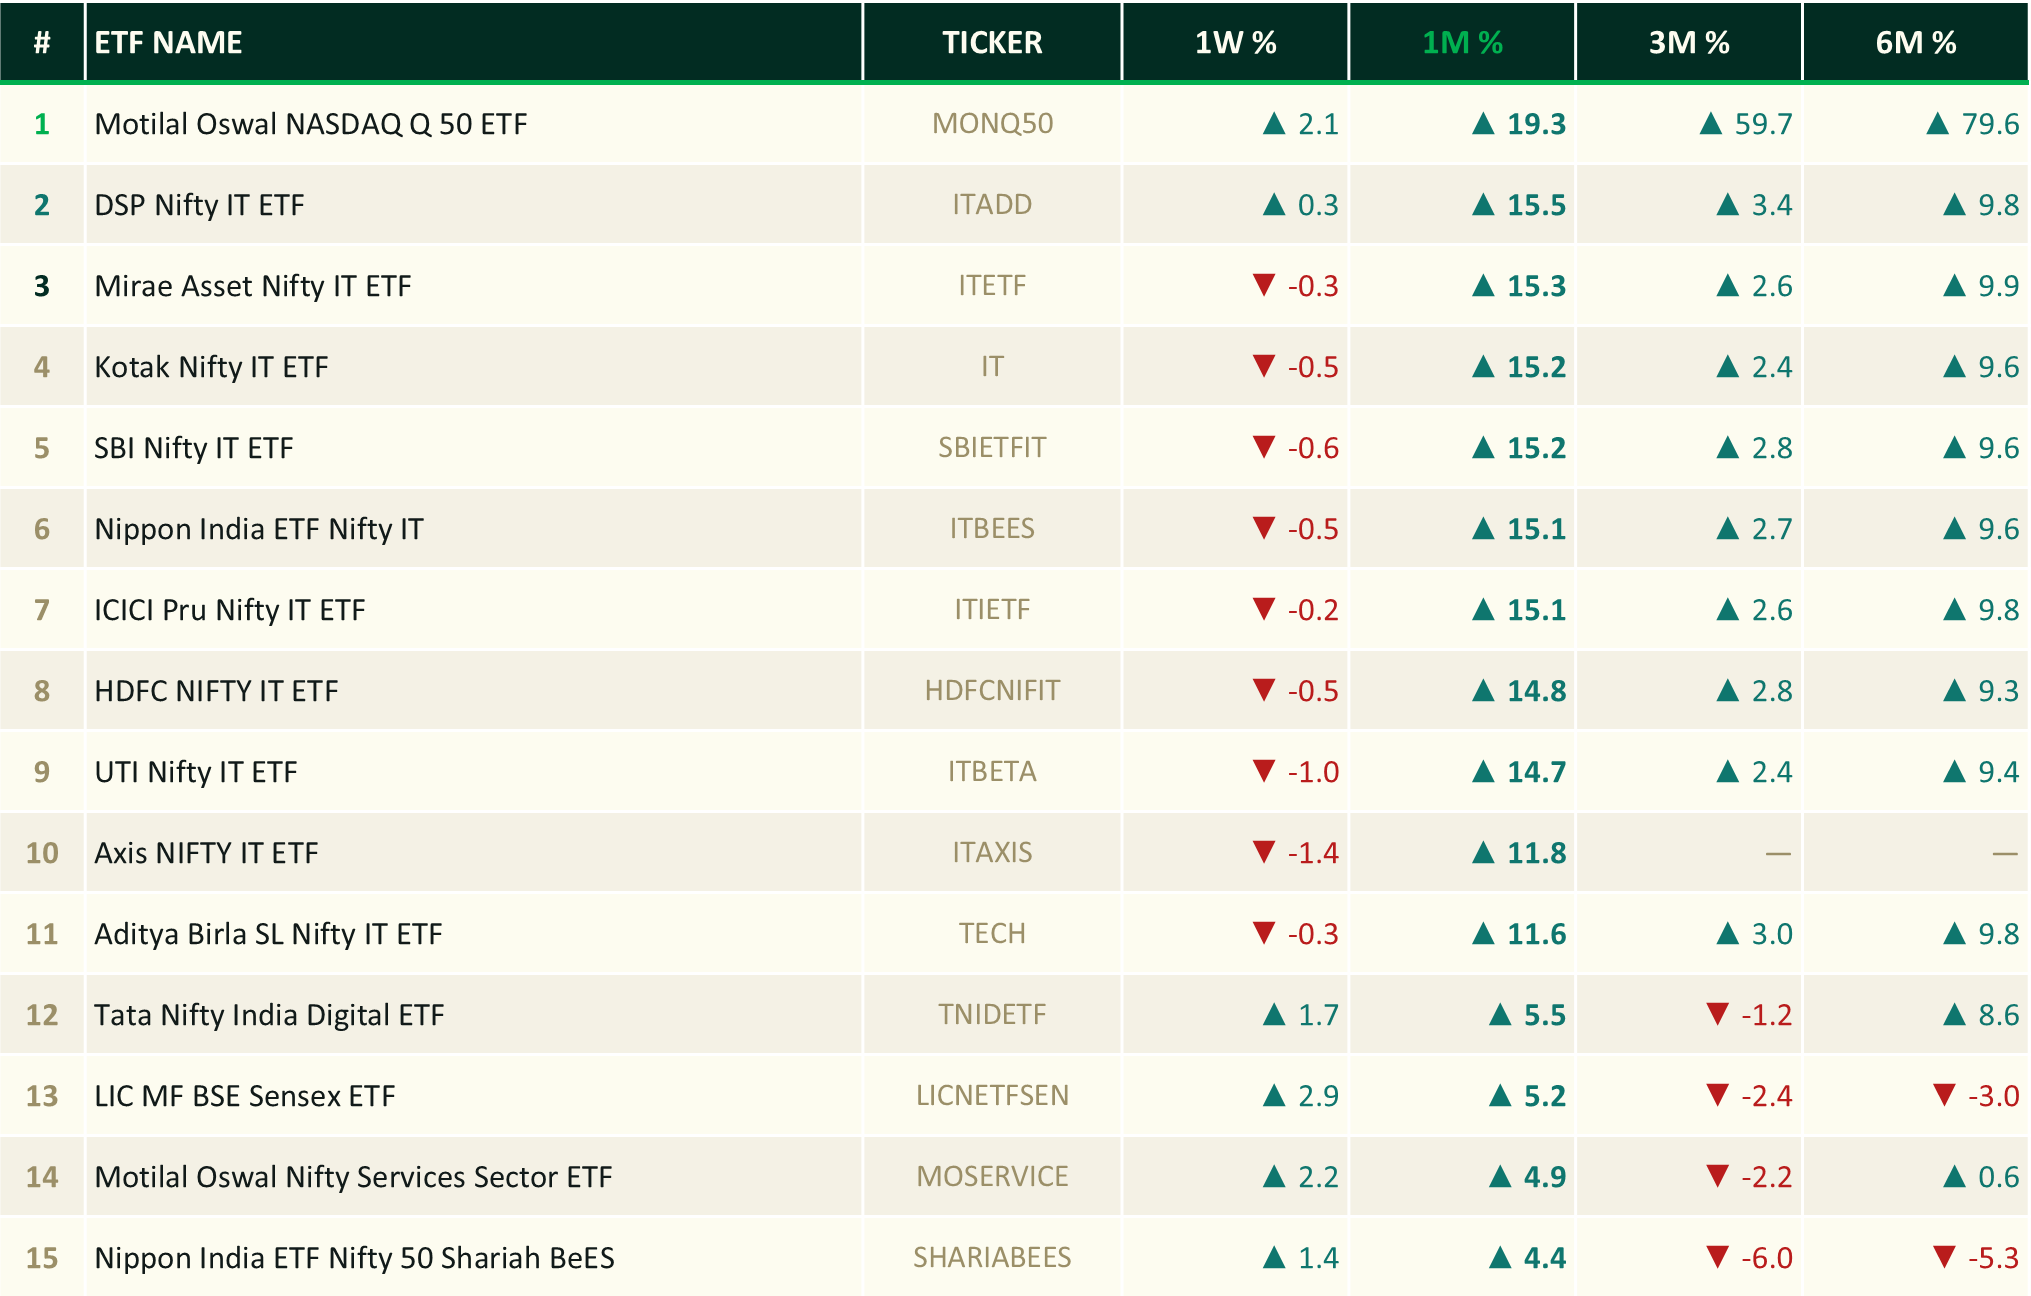
- Top 15 Performing ETFs
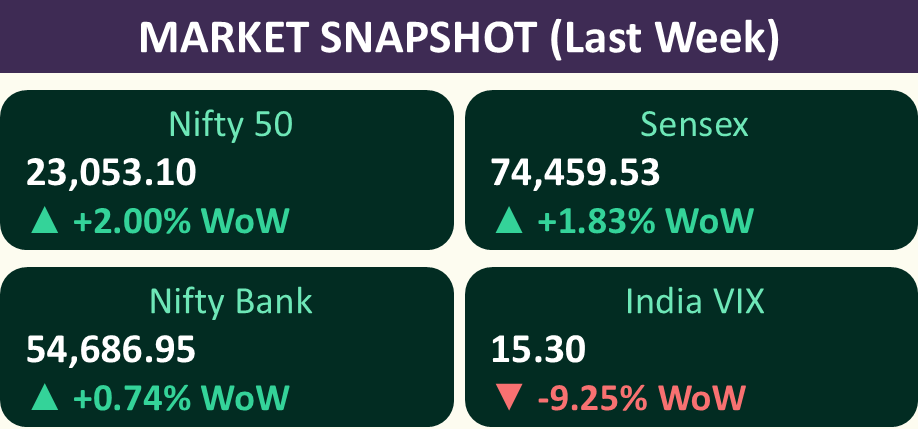
Nifty reclaims 23,000, gains 2.00% WoW as India VIX cools 9%
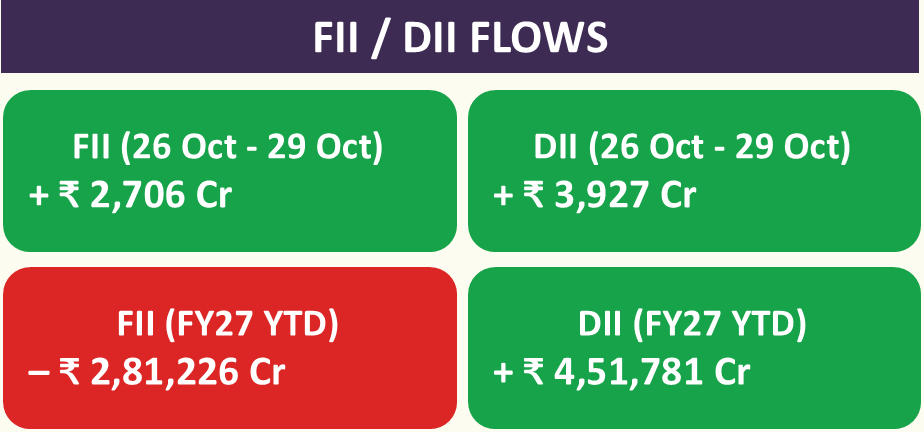
Week’s Recap
Nifty reclaims 23,000: The index closed the week at 23,053.10, recovering from the previous week’s sharp correction.
IT stocks lead the recovery: Technology stocks outperformed on earnings-related buying, supporting the broader market.
Fed holds interest rates: The US Federal Reserve kept rates unchanged, though inflation concerns and policy uncertainty still weigh on global markets.
Crude oil remains elevated: Brent traded around $116 per barrel on Middle East tensions, threatening India’s inflation outlook and import bill.
Rupee and foreign flows in focus: Continued FII outflows in October and currency pressure remain key risks for Indian equities
Midcaps and smallcaps stay volatile: Broader indices saw intermittent selling despite the benchmark recovery, favouring selective stock-specific opportunities.
Jio Platforms lists at ₹1,358: India’s biggest IPO (₹30,188 crore) debuted at a 21.36% premium to the ₹1,119 issue price.
Next Week Ahead
India Manufacturing PMI (2 Nov): Shows industrial demand, production growth and business confidence.
Crude oil and geopolitics: Brent near $116 is a key risk, and easing tensions would help the rupee and equities.
Festive demand and auto sales: November data will show consumption momentum in cars, two-wheelers and tractors.
RBA rate decision (3 Nov): Australia’s central bank guidance could move global currency and bond markets.
Q2 results to watch: ITC, SBI, Bajaj Finserv, Apollo Hospitals, M&M, Titan, Bharti Airtel, ONGC and Hindalco.
Nifty technical levels: Support is at 22,700–22,800 and resistance at 23,200–23,500, and a breakout above resistance would strengthen the recovery.
Broad market rallies this week – Next 50 leads, microcaps lag; In Factors – Momentum surges, Quality lags
Pharma, Healthcare surge this week; Oil & Gas only sector in red
Sector Rotation: Healthcare, Pharma lead; IT weakens
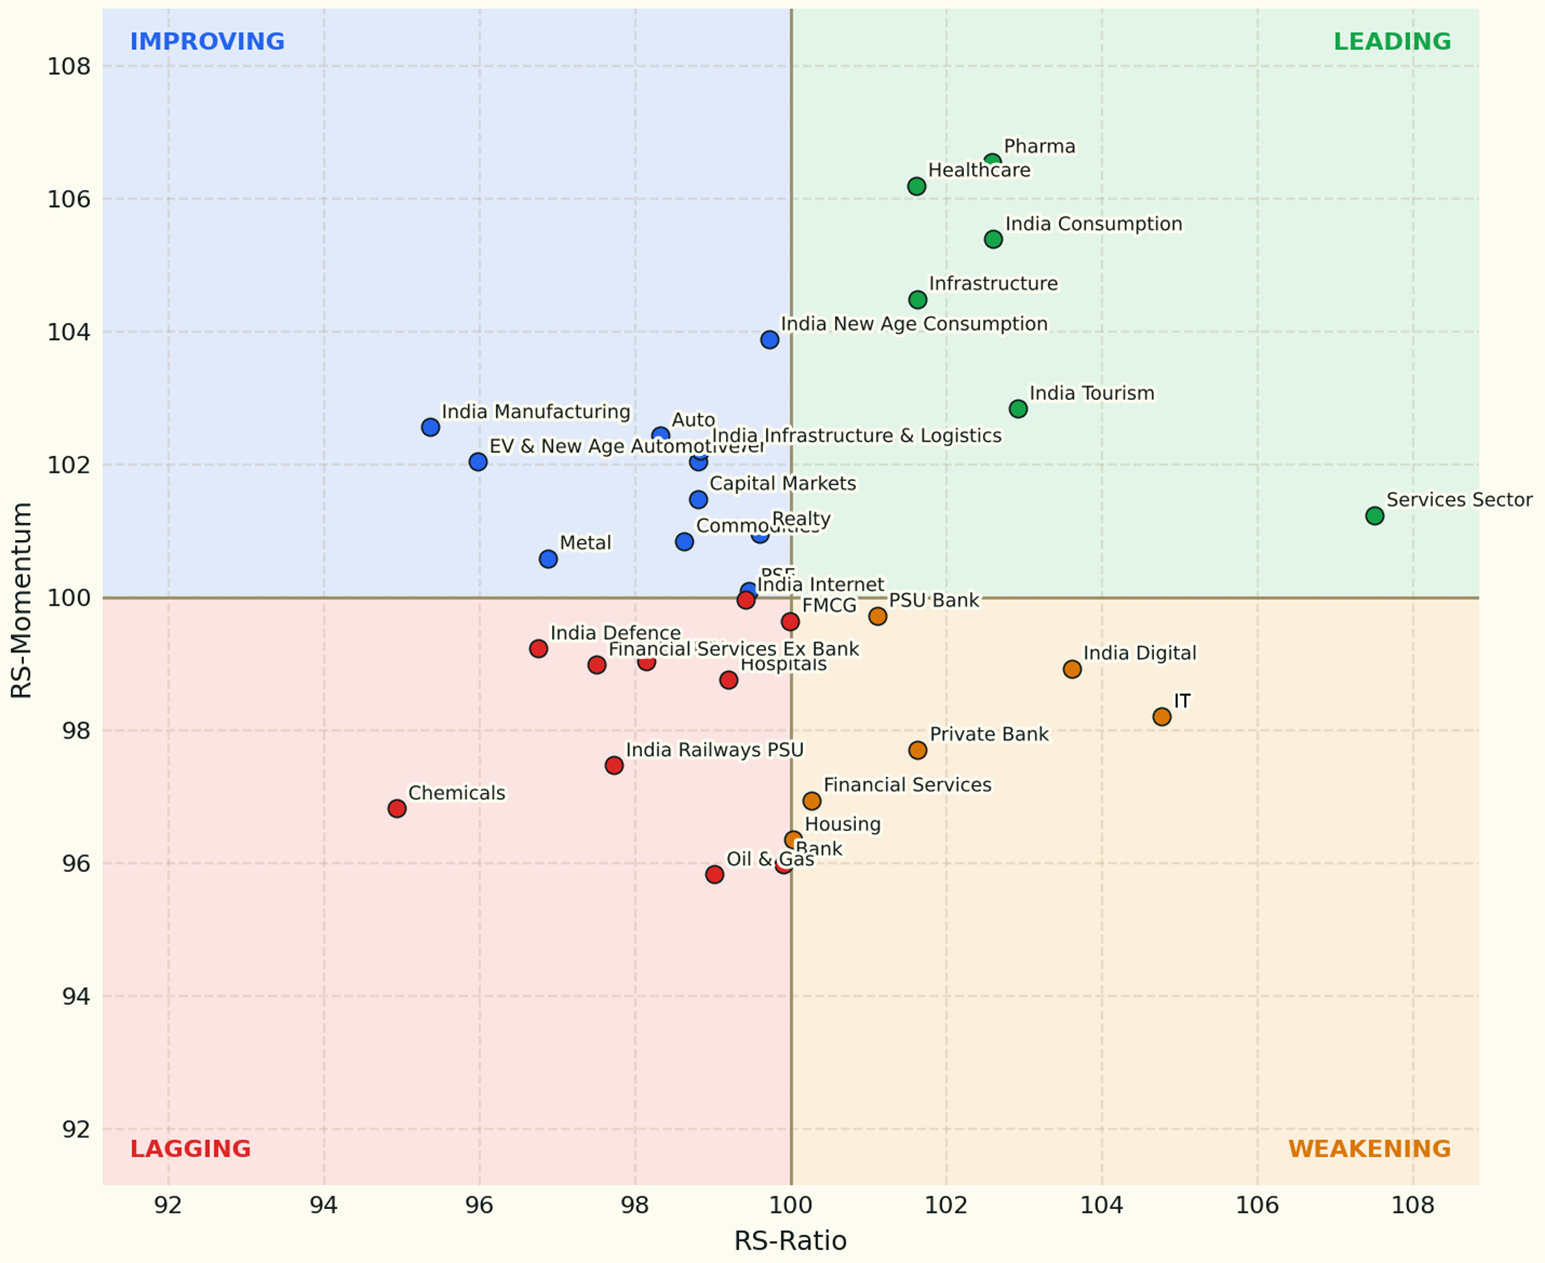
Leading
Nifty Healthcare
Nifty India Consumption
Nifty India Tourism
Nifty Infrastructure
Nifty Pharma
Nifty Services Sector
Weakening
BSE Housing
Nifty Financial Services
Nifty IT
Nifty India Digital
Nifty PSU Bank
Nifty Private Bank
Lagging
BSE Hospitals
Nifty Bank
Nifty Chemicals
Nifty Energy
Nifty FMCG
Nifty Financial Services Ex Bank
Nifty India Defence
Nifty India Internet
Nifty India Railways PSU
Nifty Oil & Gas
Improving
BSE Power
Nifty Auto
Nifty Capital Markets
Nifty Commodities
Nifty EV & New Age Automotive
Nifty India Infrastructure & Logistics
Nifty India Manufacturing
Nifty India New Age Consumption
Nifty Metal
Nifty PSE
Nifty Realty
Macro: India VIX cools 9.3%; Brent up 1.1%, Rupee steady
Global 10Y Yields: US ticks up to 4.99%; Japan eases to 2.83%
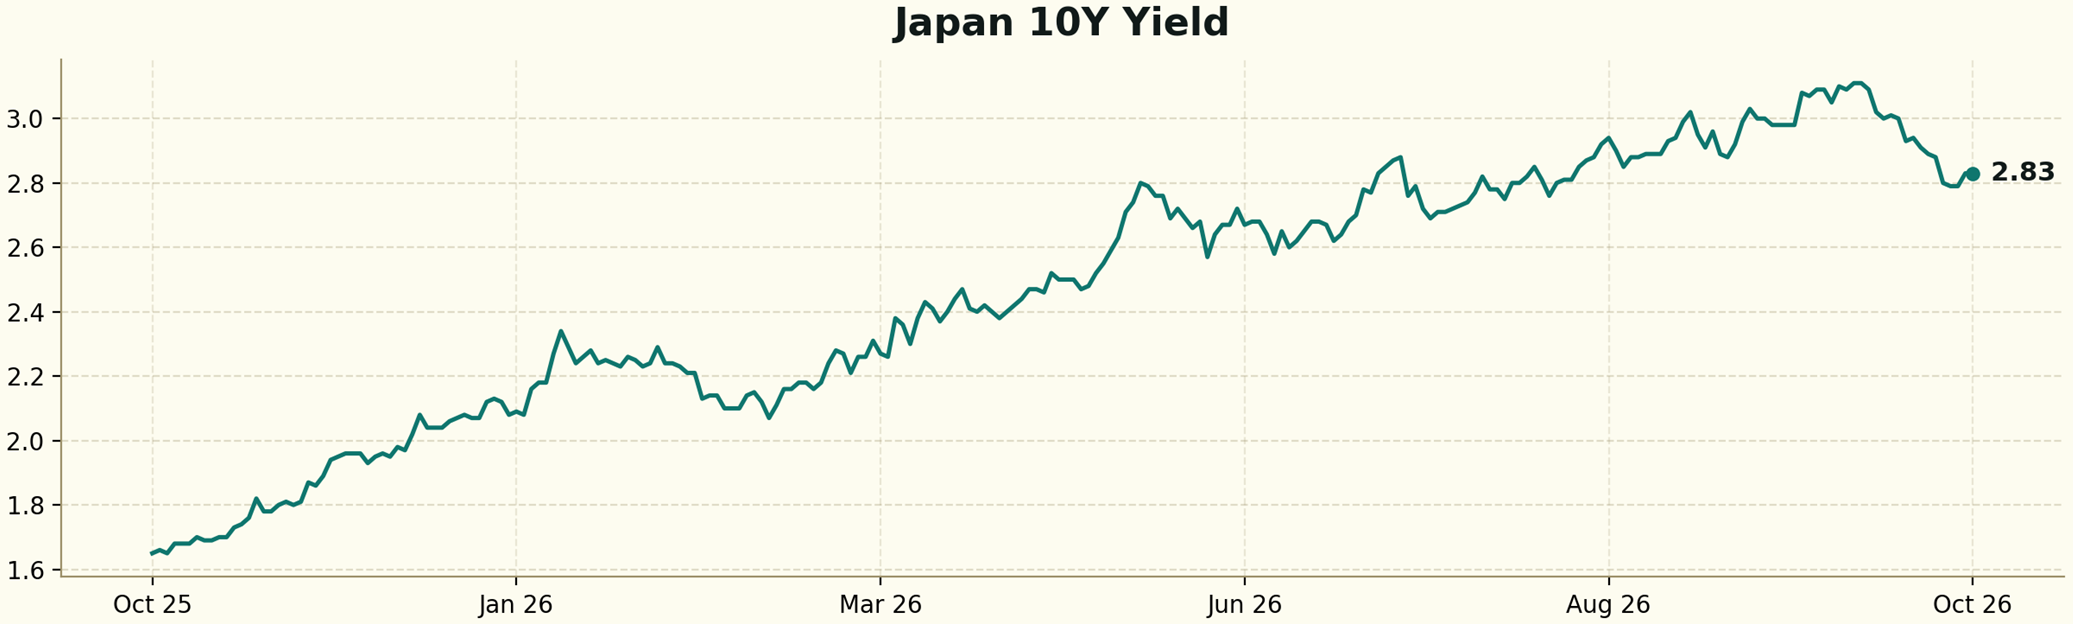
Median profit up 27% YoY; Smallcap 250 leads at 33%
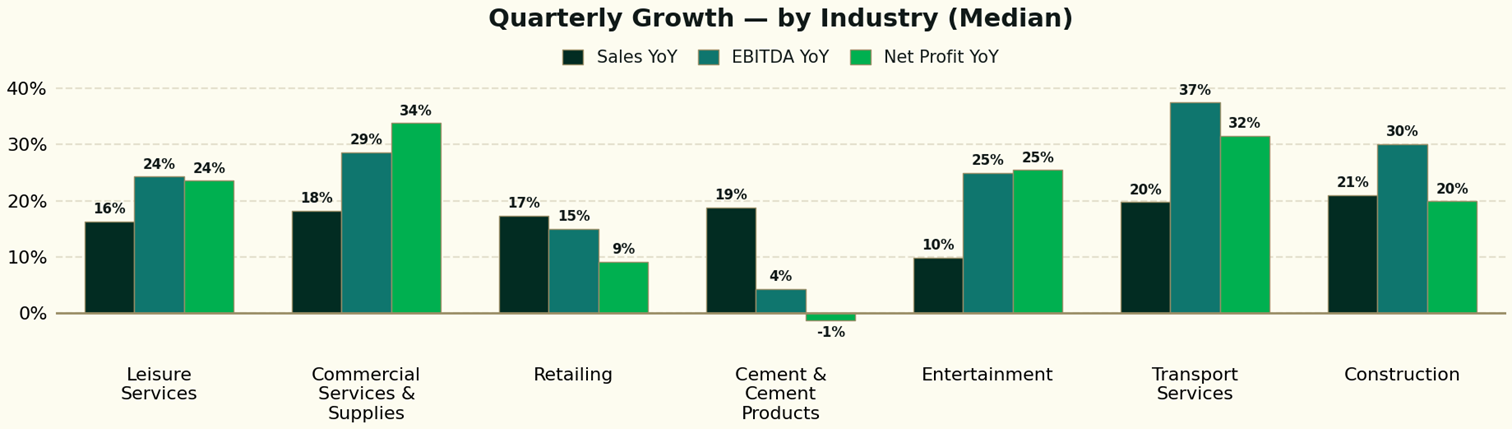
Industry growth: Textiles, Chemicals, Electricals lead; Cement dips
Top 15 Performing ETFs